Apartment equity represents the current market value of your property minus any outstanding mortgage balances or liens. It serves as a primary pillar of personal net worth, providing a tangible asset that increases through principal repayment and market appreciation. Effectively managing this equity allows for wealth compounding and strategic reinvestment opportunities.
The Relationship Between Apartment Equity and Net Worth
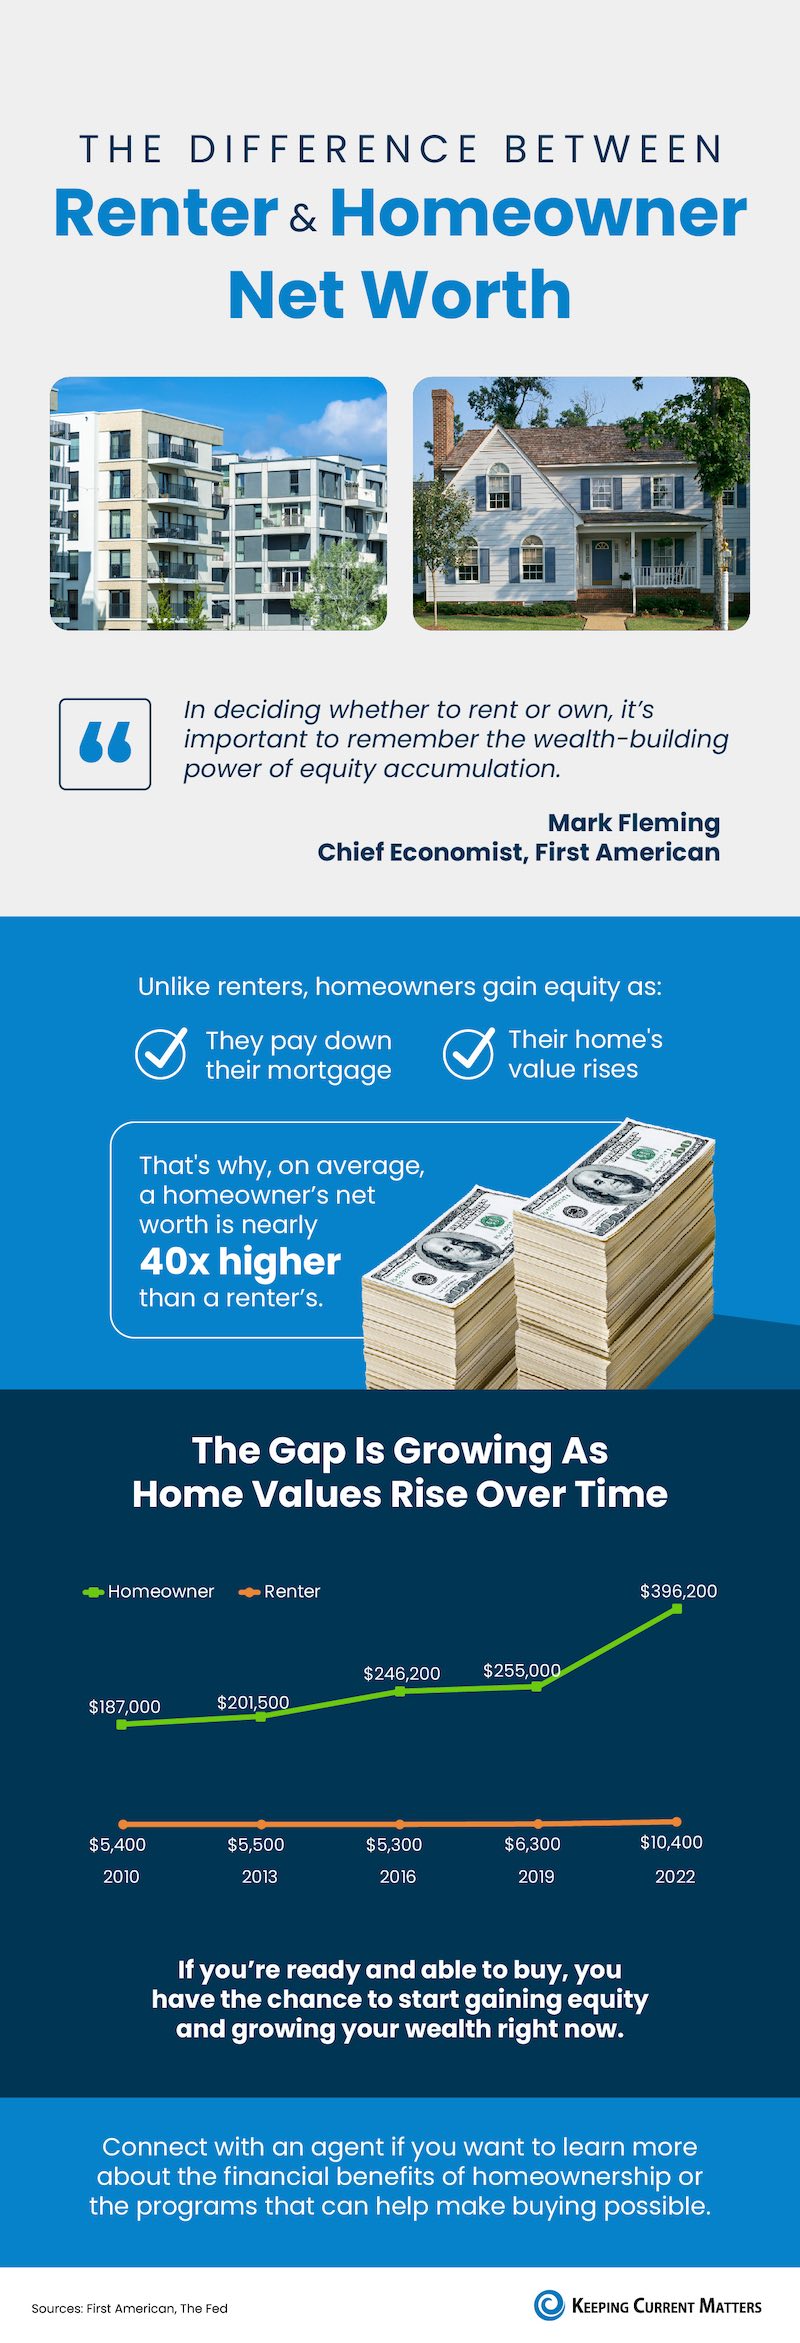
In the financial landscape of 2026, the distinction between holding an asset and possessing true equity is more critical than ever. Net worth is the most comprehensive measure of an individual's financial health, calculated by subtracting total liabilities from total assets. For many individuals, an apartment—whether a primary residence or an investment property—is the single largest component of their asset portfolio.
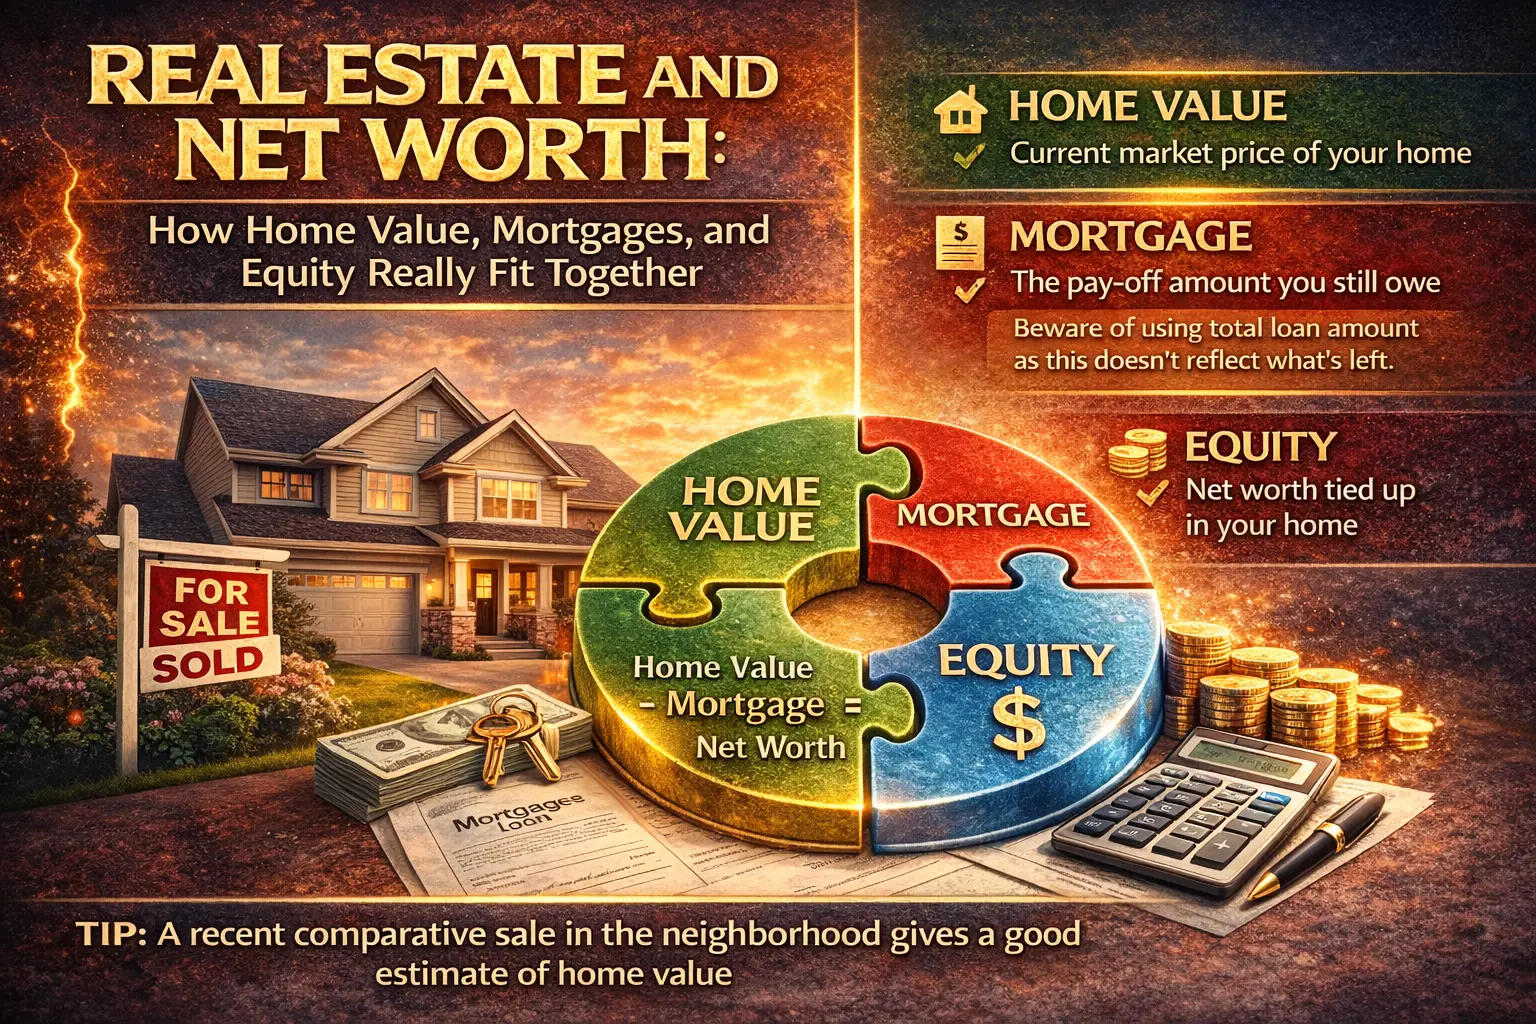
Apartment equity is the specific portion of the property that the owner truly "owns." If a condo is valued at $500,000 and the mortgage balance is $300,000, the owner has $200,000 in equity. When calculating net worth, this $200,000 is the figure that contributes to the final tally, not the full $500,000 market value.
Understanding this relationship is vital for long-term financial planning. Equity is not static; it is a dynamic figure that fluctuates based on local real estate market conditions, the broader economy, and the owner’s debt-reduction strategies. Because real estate is an illiquid asset, equity acts as a "stored" value that can be accessed through a sale, a refinance, or a line of credit, making it a versatile tool for increasing overall net worth.
How Apartment Equity is Calculated and Tracked
To accurately reflect your net worth in 2026, you must employ precise methods for calculating apartment equity. The formula is deceptively simple: Market Value - Outstanding Debt = Equity. However, determining "Market Value" and "Outstanding Debt" requires regular auditing.
Determining Market Value
In 2026, valuation techniques have moved beyond simple neighborhood comparisons. While a professional appraisal remains the gold standard for lending purposes, owners can track their equity using:
- Automated Valuation Models (AVMs): Sophisticated algorithms used by real estate platforms to provide real-time estimates.
- Broker Price Opinions (BPOs): Evaluations provided by real estate professionals based on current local demand and property condition.
- Comparative Market Analysis (CMA): An examination of similar apartments (comparables) that have sold recently in the same building or immediate vicinity.
Accounting for Liabilities
The "Debt" portion of the equation includes the primary mortgage balance, but it must also include secondary liens such as Home Equity Lines of Credit (HELOCs), unpaid property taxes, or specialized assessments common in apartment and condominium living. For a precise net worth statement, these figures should be updated monthly as principal is paid down.
The Three Pillars of Equity Growth
Equity does not grow by chance; it is driven by three distinct mechanisms that owners can monitor and, in some cases, influence.
1. Amortization (Principal Paydown)
Amortization is the process of paying off debt over time through a structured payment schedule. In the early years of a mortgage, a higher percentage of the monthly payment goes toward interest. As the loan matures, a larger portion is applied to the principal. By 2026, many owners who secured low-interest rates in previous years are seeing a significant acceleration in their equity growth as their loans enter the middle or latter stages of the amortization schedule.
2. Market Appreciation
Appreciation is the increase in the property’s value over time due to external factors such as inflation, neighborhood development, and increased demand. While the real estate market can experience periods of volatility, the historical trend for urban apartments has generally been upward. Appreciation is a powerful driver of net worth because it applies to the entire value of the property, not just the portion owned outright—a concept known as leverage.
3. Forced Equity
Forced equity refers to the increase in value generated by physical improvements or strategic management. For apartment owners, this might include:
- Interior Renovations: Updating kitchens and bathrooms or installing modern flooring.
- Energy Efficiency: Upgrading to smart HVAC systems or high-efficiency windows, which are highly valued in the 2026 market.
- Functional Improvements: Adding storage solutions or optimizing floor plans to increase the unit's utility.
Comparing Equity Types: Primary Residence vs. Investment
The role of apartment equity in your net worth varies significantly depending on how the property is used. The tax implications and liquidity options differ based on whether the apartment is your home or a source of rental income.
| Feature | Primary Residence Equity | Investment Apartment Equity |
|---|---|---|
| Primary Goal | Shelter and long-term savings | Cash flow and capital gains |
| Tax Treatment | Potential capital gains exclusion (e.g., Section 121) | Subject to capital gains and depreciation recapture |
| Impact on Cash Flow | Generally neutral (mortgage is an expense) | Positive (equity supports higher rental rates) |
| Liquidity Access | HELOCs or Home Equity Loans | Refinancing or 1031 Exchange |
| Net Worth Stability | Usually high; less likely to sell in a downturn | Moderate; subject to investor market sentiment |
The Role of Leverage in Building Net Worth
Leverage is the use of borrowed capital to increase the potential return of an investment. In the context of apartment equity, leverage allows you to control a high-value asset with a relatively small amount of your own money (the down payment).
If you purchase a $400,000 apartment with a $80,000 down payment (20%), and the property appreciates by 5% in one year ($20,000), your return on the actual cash invested is 25% ($20,000 / $80,000). This accelerated growth is why real estate is a preferred vehicle for increasing net worth. However, leverage is a double-edged sword; if the property value decreases, the loss is also magnified relative to your equity.
Accessing and Reinvesting Apartment Equity
A high net worth on paper is beneficial, but the true power of apartment equity lies in its utility. In 2026, several methods exist for "harvesting" equity without necessarily selling the property.
Home Equity Lines of Credit (HELOC)
A HELOC functions as a revolving line of credit secured by your apartment. It allows you to borrow against your equity as needed, pay it back, and borrow again. This is often used for home improvements or as an emergency fund, though it should be used cautiously to avoid over-leveraging.
Cash-Out Refinancing
This involves replacing your existing mortgage with a new, larger loan and taking the difference in cash. This is a common strategy for investors who want to use the equity from one apartment to provide the down payment for a second property, thereby expanding their portfolio and total net worth.
The 1031 Exchange (For Investment Apartments)
Under U.S. tax law, the Internal Revenue Service (IRS) allows investors to defer paying capital gains taxes when they sell an investment property and reinvest the proceeds into a "like-kind" property. This allows the full amount of equity to be rolled into a more valuable asset, compounding net worth without the immediate friction of taxation.
Risks to Apartment Equity and Net Worth
To protect your financial position in 2026, you must be aware of the factors that can erode apartment equity.
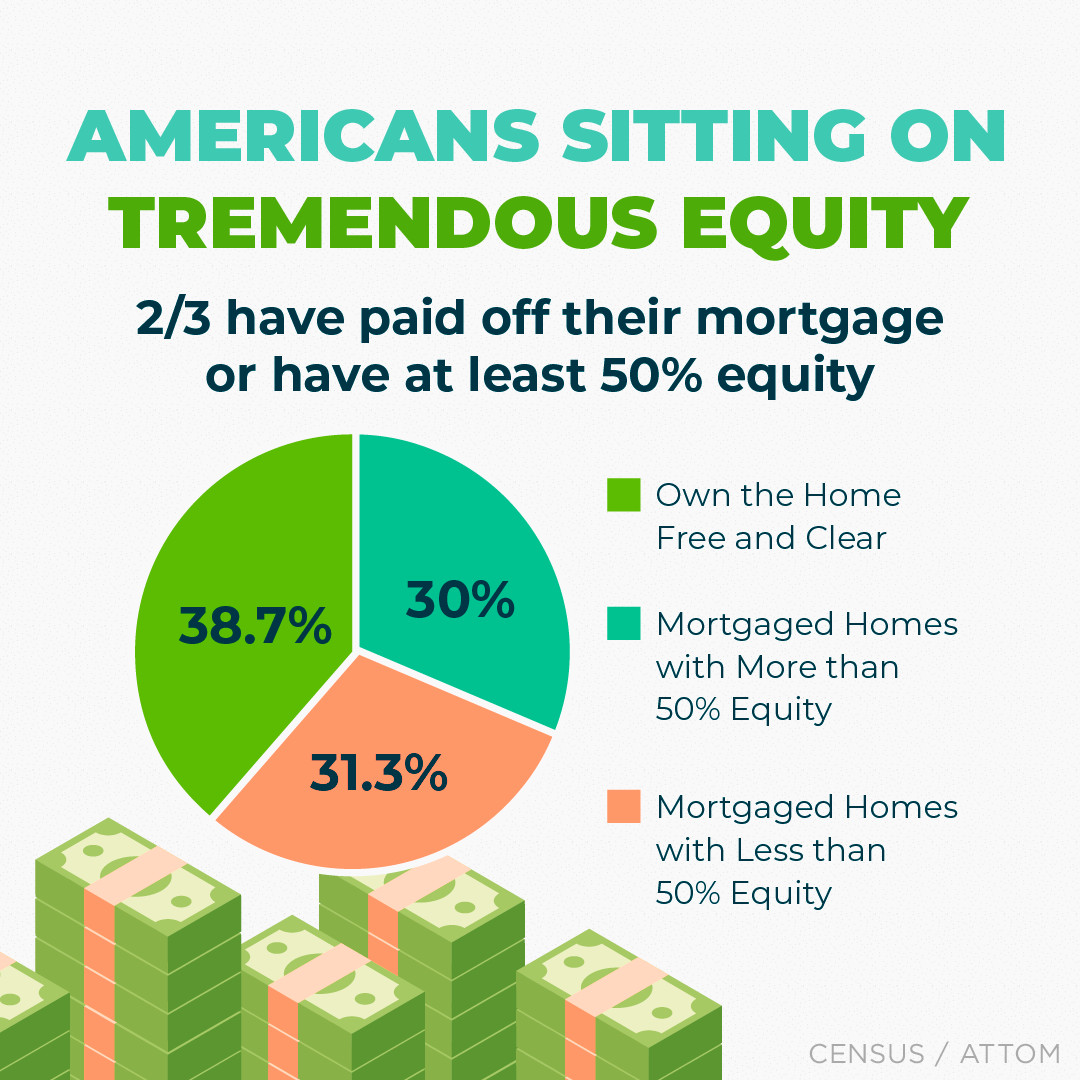
- Market Downturns: Economic recessions can lead to a drop in property values. If your equity margin is slim, a market correction could result in "negative equity" (being underwater), where the mortgage balance exceeds the home's value.
- Deferred Maintenance: For apartments, the condition of the unit is paramount. Neglecting repairs can lead to a decrease in market value relative to the rest of the building.
- Special Assessments: Condominium and cooperative buildings may require large, one-time payments for major repairs (e.g., roof replacement, elevator upgrades). If an owner cannot pay, a lien may be placed against the property, reducing net equity.
- Inflation and Interest Rates: High interest rates can cool demand for apartments, slowing appreciation. While the equity you have already built remains, the growth of that equity may stall.
Strategies for Optimizing Net Worth via Equity
For those looking to maximize their financial standing in 2026, a proactive approach to equity management is required.
- Accelerate Principal Payments: Making one extra mortgage payment per year or rounding up monthly payments can shave years off a loan and significantly boost equity.
- Monitor Local Zoning: Changes in local zoning or new infrastructure (like a new transit line) can lead to rapid appreciation. Staying informed allows you to time a sale or refinance for maximum gain.
- Balance the Portfolio: Avoid having 100% of your net worth tied up in apartment equity. Financial advisors generally recommend a diversified mix of real estate, equities (stocks), and liquid assets to mitigate risk.
- Audit HOA Health: If your apartment is part of a Homeowners Association (HOA), review their reserve studies and financial statements. A poorly managed HOA can lead to high fees and lower property values, directly impacting your equity.
FAQ
Does apartment equity include the value of furniture and upgrades?
Generally, no. Apartment equity is based on the "real property" value. While permanent upgrades like new flooring or cabinets increase the market value of the apartment, moveable assets like furniture, electronics, and décor are considered personal property and do not contribute to real estate equity or the core valuation used by lenders.
How often should I update the equity value in my net worth statement?
For a standard financial review, updating your equity figures quarterly or annually is sufficient. However, if you are planning a major financial move, such as applying for a loan or selling the property, you should seek a more frequent and precise valuation.
Can I lose my equity if the building is managed poorly?
Yes. In an apartment or condo setting, the value of your individual unit is tethered to the condition and reputation of the entire building. If the building’s management fails to maintain common areas or faces legal issues, the market value of all units can decline, thereby reducing your equity.
Is equity the same as profit?
No. Equity is a measure of ownership at a specific point in time. Profit is only realized once the property is sold and all closing costs, commissions, and taxes are paid. It is possible to have $200,000 in equity but only $150,000 in actual profit after the expenses of a sale.
How do interest rates in 2026 affect my existing equity?
If you have a fixed-rate mortgage, changes in interest rates do not affect your debt balance or your principal paydown schedule. However, higher market interest rates can lower the "buying power" of potential future buyers, which may slow the rate of market appreciation or even lead to a slight decline in your apartment’s market value.
Summary and Recommendations
Apartment equity is a cornerstone of modern wealth building, offering a path to increased net worth through both forced and natural appreciation. In 2026, the key to financial success lies in viewing your apartment not just as a place to live, but as a strategic asset.
Next Actions:
- Verify your current balance: Check your latest mortgage statement for the exact principal remaining.
- Get a "Pulse" Valuation: Use at least two different online valuation tools to get a baseline for your apartment's current market value.
- Review your Amortization Schedule: Understand how much of your monthly payment is currently going toward building equity versus paying interest.
- Consult a Professional: If your equity has grown significantly, speak with a financial advisor or tax professional about whether a 1031 exchange or a cash-out refinance aligns with your 2026 financial goals.