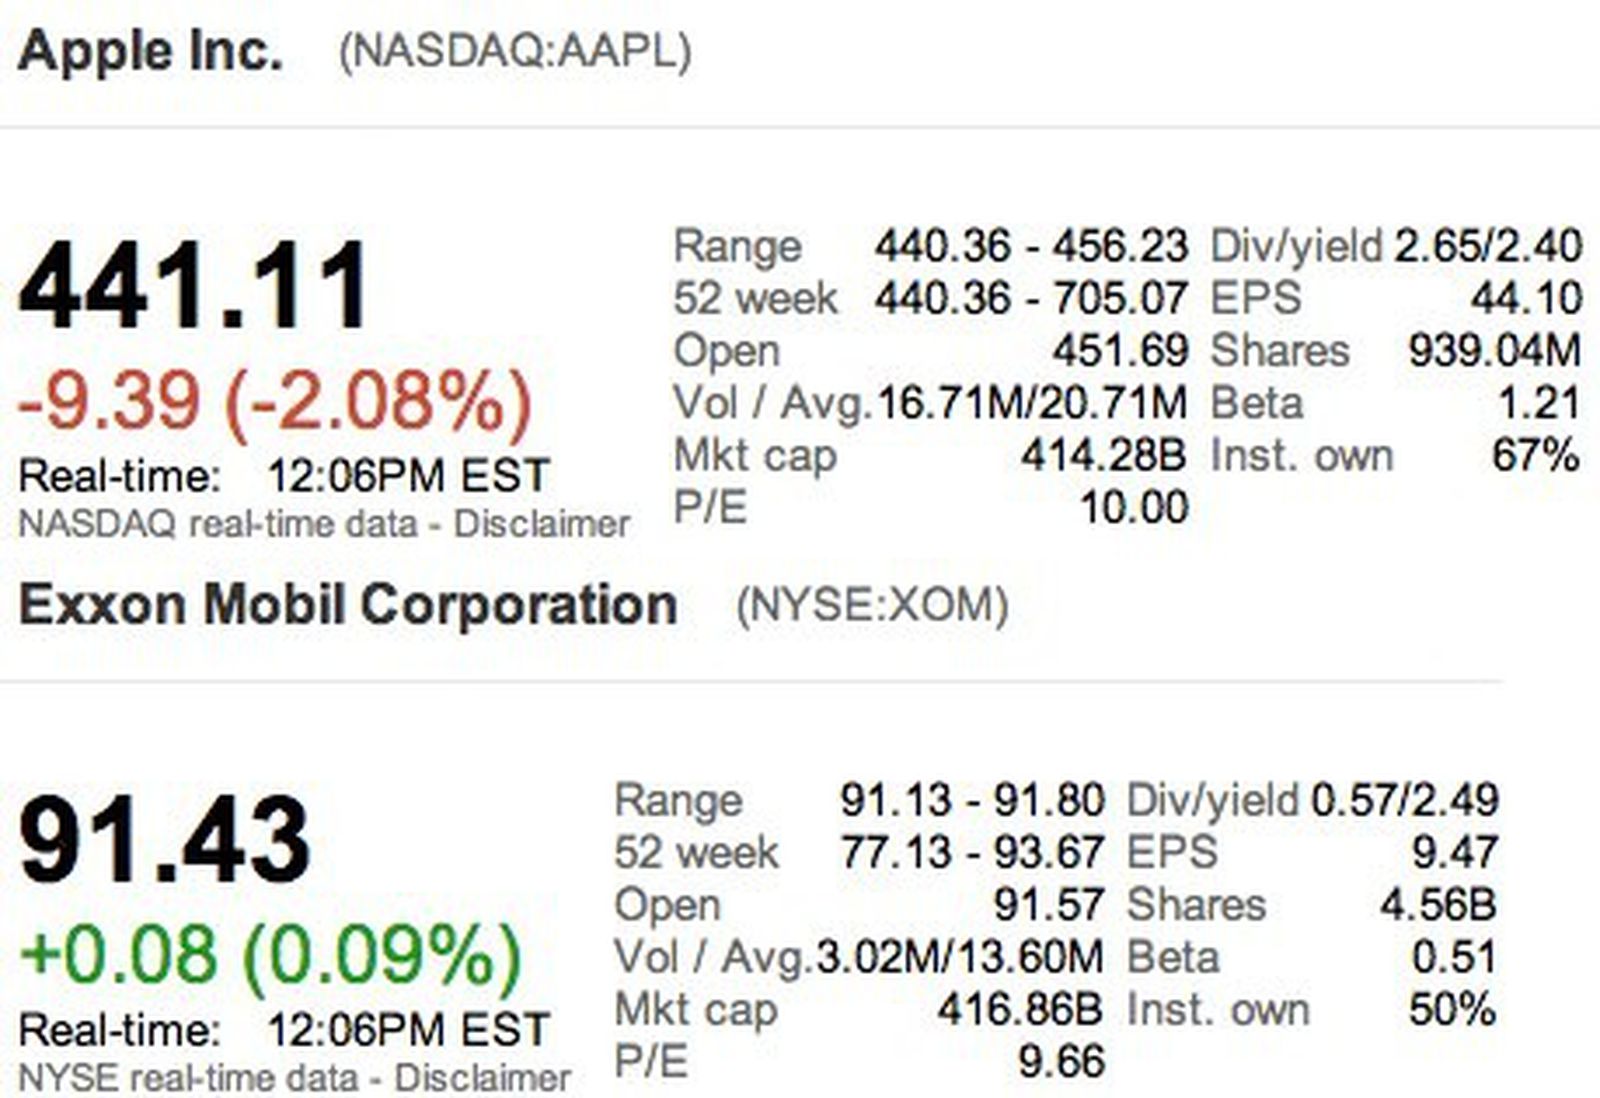
Apple Inc. became publicly traded on December 12, 1980, listing on the NASDAQ stock exchange under the ticker symbol AAPL. The company offered 4.6 million shares at an initial public offering (IPO) price of $22.00 per share, raising approximately $101 million and valuing Apple at roughly $1.78 billion in the largest corporate debut since Ford Motor Company went public in 1956.
The Historical Context of Apple’s 1980 Initial Public Offering
When Apple Computer, Inc. filed its preliminary prospectus with the U.S. Securities and Exchange Commission (SEC) in late 1980, the personal computing industry was still in its infancy. Founded on April 1, 1976, by Steve Jobs, Steve Wozniak, and Ronald Wayne in the Jobs family garage in Los Altos, California, Apple transitioned rapidly from an hobbyist outfit assembling the Apple I circuit board into a commercial enterprise.
The catalyst for Apple's commercial viability was the introduction of the Apple II computer in 1977. Designed primarily by Wozniak, the Apple II featured an integrated keyboard, color graphics capability, expansion slots, and an external floppy disk drive interface. The platform gained unprecedented enterprise traction following the 1979 release of VisiCalc, the first electronic spreadsheet program, which transformed personal computers from hobby items into essential business tools.
- 1976: Apple Founded
- 1977: Apple II Launch
- 1979: VisiCalc Release
- 1980: NASDAQ IPO
To finance its rapid operational expansion, Apple secured venture capital investment prior to its public market listing. Early financial backing arrived from A.C. "Mike" Markkula Jr., a former Intel executive who provided $92,000 in equity funding alongside a $250,000 credit line in 1977. Additional venture investment followed from prominent Silicon Valley financiers, including Arthur Rock and Don Valentine’s Sequoia Capital. By late 1980, with annual revenues climbing from $774,000 in fiscal year 1977 to over $117 million in fiscal year 1980, Apple sought public capital to expand its manufacturing infrastructure, fund research and development for new computing architectures, and strengthen its balance sheet.
Regulatory Challenges and State Blue-Sky Laws
Apple’s path to the public market encountered regulatory friction at the state level. Regulators in Massachusetts, enforcing strict local state securities statutes ("blue-sky laws"), initially prohibited retail investors within the state from purchasing shares of Apple’s IPO. State officials deemed the offering "too risky" and overpriced relative to traditional financial metrics.
Under Massachusetts regulatory standards of the era, the combination of a high price-to-earnings ratio (the IPO price represented roughly 100 times the previous year’s earnings) and significant equity allocation to company insiders failed to satisfy state investor-protection tests. Although institutional investors in Massachusetts could participate, individual retail purchasers in the state were restricted until secondary-market trading established broader price discovery.
Key IPO Statistics, Underwriting, and Immediate Market Impact
Apple’s public offering was co-underwritten by investment banking firms Morgan Stanley & Co. Incorporated and Hambrecht & Quist. The demand for shares severely outstripped the available allocation of 4.6 million shares, leading the underwriting syndicate to exercise overallotment options and price the offering at the high end of initial expectations ($22.00 per share).
On the morning of December 12, 1980, trading opened under the ticker AAPL on the NASDAQ National Market. Within minutes, the entire allotment of shares was absorbed by institutional and retail investors. By the closing bell, the stock price had surged to $29.00 per share, delivering a single-day gain of 31.8%.
| Metric / Event | IPO Baseline (Dec 12, 1980) | Subsequent Milestone / Current Context |
|---|---|---|
| Ticker Symbol | AAPL (NASDAQ) | AAPL (NASDAQ) |
| IPO Price per Share | $22.00 | $0.0982 (Split-Adjusted Basis) |
| Shares Offered | 4.6 Million | Over 15 Billion (Post-Splits / Buybacks) |
| Capital Raised | ~$101.2 Million | N/A (Initial Equity Capitalization) |
| Day-One Closing Price | $29.00 | Variable (Historical ATH Exceeds $230/share) |
| Market Capitalization | ~$1.778 Billion | Exceeded $3.0 Trillion Valuation |
| Cumulative Stock Splits | 1:1 (Original) | 224:1 (Across 5 Historical Splits) |
The successful IPO generated immense paper wealth for early shareholders and employees. Apple’s public debút created more than 300 instant millionaires, a record for an industrial or technology listing at that time.
- Steve Jobs, who held 7.5 million shares, saw his net worth rise to approximately $217 million at the end of the first trading day.
- Mike Markkula, owning roughly 7 million shares, held a stake valued at approximately $203 million.
- Steve Wozniak, holding roughly 4 million shares, achieved a valuation of approximately $116 million.
Apple Stock Splits: Understanding the Cumulative Split Ratio
When evaluating historical stock prices from Apple’s 1980 offering, simple price comparisons between historical nominal figures and modern share prices are misleading. Apple has executed five separate stock splits throughout its history as a publicly traded corporation.
A stock split increases the total number of outstanding shares while proportionally reducing the nominal price per share, leaving the company's overall market capitalization and an individual investor’s total equity value unchanged.
- Original IPO Share (1)
- 1987: 2-for-1 (2 shares)
- 2000: 2-for-1 (4 shares)
- 2005: 2-for-1 (8 shares)
- 2014: 7-for-1 (56 shares)
- 2020: 4-for-1 (224 shares)
- 2014: 7-for-1 (56 shares)
- 2005: 2-for-1 (8 shares)
- 2000: 2-for-1 (4 shares)
- 1987: 2-for-1 (2 shares)
Complete History of Apple Stock Splits
- June 16, 1987 (2-for-1 Split): Executed during the expansion of the Macintosh computer line to lower the nominal share price for individual investors and improve market liquidity.
- June 21, 2000 (2-for-1 Split): Following the corporate restructuring led by Steve Jobs upon his return and the commercial success of the iMac G3, Apple split its stock to bring market prices back into a standard retail trading range.
- February 28, 2005 (2-for-1 Split): Driven by rapid growth in the digital music market sparked by the iPod and the iTunes Music Store, which significantly elevated Apple’s public equity valuation.
- June 9, 2014 (7-for-1 Split): Designed to make AAPL shares accessible to a broader base of retail investors after the stock price surpassed $600 per share following global iPhone adoption.
- August 31, 2020 (4-for-1 Split): Implemented to lower nominal share costs and balance the weighting of constituent stocks within the price-weighted Dow Jones Industrial Average, to which Apple was added in 2015.
Calculating the Cumulative Split Factor
To determine the equivalent number of shares today resulting from a single share purchased at the 1980 IPO, multiply each split ratio sequentially:
$$\text{Cumulative Split Ratio} = 2 \times 2 \times 2 \times 7 \times 4 = 224$$
Consequently, one single share of Apple stock purchased at the December 12, 1980 IPO for $22.00 has expanded into 224 shares.
To calculate the split-adjusted original purchase price per share used on modern financial charts, divide the initial $22.00 IPO price by the cumulative factor of 224:
$$\text{Split-Adjusted IPO Cost Basis} = \frac{$22.00}{224} \approx $0.09821 \text{ (approx. 9.8 cents)}$$
Financial Evolution: From Desktop Maker to Multi-Trillion-Dollar Giant
Apple’s trajectory as a public company spans distinct corporate eras, characterized by innovation, structural restructuring, near-insolvency, and unprecedented capital expansion.
- 1980-1985: Early Growth & Mac Launch
- 1985-1997: Internal Turbulence & Restructuring
- 1997-2011: Return of Jobs (iMac, iPod, iPhone)
- 2011-Present: Tim Cook Era (Services, Capital Return, $3T+ Cap)
The Post-IPO Era and Departure of Founders (1981–1996)
Following its IPO, Apple faced rising competition from IBM personal computers running Microsoft DOS. Internal operational disagreements between Steve Jobs and Chief Executive Officer John Sculley led to Jobs's departure from Apple in 1985.
During the late 1980s and early 1990s, Apple maintained profitability through high product margins on the Macintosh family. However, expanding software fragmentation, inventory misallocations, and aggressive market share expansion by Windows-based PC manufacturers pushed Apple toward severe financial distress by 1996.
The Acquisition of NeXT and the Corporate Turnaround (1996–2011)
In December 1996, Apple acquired NeXT Software, Inc. for $429 million, bringing Steve Jobs back to the company he co-founded. Operating initially as interim CEO, Jobs streamlined Apple’s product line, canceled unprofitable projects, and secured a $150 million non-voting equity investment from Microsoft to stabilize cash reserves.
The core technology of NeXTSTEP formed the underlying foundation for Mac OS X. Apple introduced a sequence of consumer electronic breakthroughs that re-defined corporate hardware manufacturing:
- 1998 (iMac G3): Restored profitability through industrial design and simplified consumer internet connectivity.
- 2001 (iPod & iTunes): Transformed the music distribution model and shifted Apple from a computer manufacturer to a broader consumer technology company.
- 2007 (iPhone): Created the modern smartphone economy, establishing a long-term revenue engine driven by hardware sales and mobile software licensing.
- 2010 (iPad): Established a market segment in tablet computing.
The Tim Cook Era: Market Capitalization Milestones (2011–Present)
Following Steve Jobs’s passing in October 2011, Tim Cook assumed leadership as Chief Executive Officer. Under Cook’s tenure, Apple scaled global supply chain operations, expanded wearable technology (Apple Watch, AirPods), and built a massive high-margin Services segment encompassing the App Store, iCloud, Apple Pay, and subscription media.
Driven by compound earnings growth and aggressive share buyback programs, Apple achieved historically unprecedented market capitalizations on major public exchanges:
- August 2, 2018: Became the first publicly traded U.S. company to reach a $1 Trillion market capitalization.
- August 19, 2020: Reached a $2 Trillion market valuation, doubling its enterprise market value in just two years.
- January 3, 2022: Briefly crossed the $3 Trillion market capitalization threshold during intraday trading, a benchmark re-confirmed and sustained in subsequent trading periods.
Calculating Historical Investment Returns
To illustrate the long-term wealth creation of Apple's stock since it became publicly traded, consider a hypothetical investment made at the IPO price on December 12, 1980.
Scenario: A $2,200 Initial Purchase at the IPO
- Initial Investment: $2,200.00
- Initial Share Count: 100 shares at $22.00 per share
- Post-Split Share Volume: $100 \times 224 = 22,400 \text{ shares}$
If Apple stock trades at an illustrative market price of $200.00 per share, the market value of those original 100 shares is calculated as:
$$\text{Current Market Value} = 22,400 \text{ shares} \times $200.00 = $4,480,000.00$$
This represents a nominal capital appreciation return of over 203,000%, excluding cash dividend disbursements.
Dividend History and Reinvestment Impact
Apple paid quarterly cash dividends throughout the 1980s and early 1990s before suspending payments in 1995 to preserve working capital during its financial crisis. Under Tim Cook, Apple reinstated its dividend program in 2012 alongside a broad Capital Return Program.
Investors who continuously reinvested cash dividends into additional shares of AAPL through a Dividend Reinvestment Plan (DRIP) earned higher compound returns than calculations based on share price appreciation alone.
Capital Allocation and Corporate Finance Precedents
Apple’s performance after going public reshaped modern institutional investment management, venture capital structures, and corporate capital allocation policies.
- High Gross Margins
- Massive Free Cash Flow
- Strategic Share Buybacks
- Increased EPS
1. Validation of Venture Capital Models
Apple's successful public listing demonstrated the financial viability of funding early-stage technology companies with institutional private equity in exchange for minority equity stakes. The outsized returns generated for Sequoia Capital and Rock Management established the institutional blueprint for Silicon Valley corporate finance.
2. Large-Scale Corporate Share Repurchases
Beginning in 2012, Apple initiated one of the largest share buyback programs in corporate history. By purchasing hundreds of billions of dollars of its own common stock on the open market, Apple systematically reduced its total diluted share count. This capital deployment strategy increases per-share net income (EPS) and optimizes capital efficiency without relying solely on top-line revenue growth.
Frequently Asked Questions
What exact date did Apple go public, and on which exchange?
Apple Inc. went public on December 12, 1980. The shares listed on the NASDAQ exchange under the ticker symbol AAPL.
What was Apple's original share price at its IPO?
The official initial public offering price was $22.00 per share. Adjusted for five subsequent stock splits (amounting to a 224-for-1 ratio), the original IPO cost basis is equivalent to approximately $0.0982 per share.
How many stock splits has Apple completed since going public?
Apple has executed five stock splits: a 2-for-1 split in June 1987, a 2-for-1 split in June 2000, a 2-for-1 split in February 2005, a 7-for-1 split in June 2014, and a 4-for-1 split in August 2020.
Why did regulators in Massachusetts temporarily ban retail sales of Apple's IPO?
Massachusetts securities regulators applied strict state "blue-sky" laws that deemed the offering overly speculative. They cited Apple’s high price-to-earnings multiple and substantial insider equity ownership as risks that failed state investor-protection standards for retail buyers.
Who were the largest individual financial beneficiaries of Apple’s IPO?
Co-founder Steve Jobs held 7.5 million shares valued at approximately $217 million on day one. Early investor Mike Markkula held roughly 7 million shares worth about $203 million, and co-founder Steve Wozniak held stock valued at roughly $116 million.
Investor Takeaways and Evaluation Frameworks
Analyzing Apple's transition to a public company offers critical lessons for evaluating modern technology IPOs and public equity investments:
- Distinguish Between Revenue Expansion and Margin Quality: Apple’s early public valuation was supported by strong hardware gross margins from the Apple II rather than unproven revenue projections. Evaluate whether contemporary IPO candidates demonstrate clear unit economics.
- Account for Share Structure and Dilution: Long-term equity appreciation depends on capital management. While stock splits lower share prices to improve liquidity, ongoing equity issuances dilute existing owners. Contrast historical share expansion with stock buyback activity.
- Evaluate Ecosystem Expansion: Apple evolved from a single-product hardware maker into a integrated hardware, software, and services ecosystem. Long-term corporate endurance relies on building multi-product ecosystems that create high customer retention and recurring revenue streams.
Financial Disclaimer: Historical performance and past market data are presented for informational and educational purposes only and should not be construed as investment advice or a recommendation to buy or sell securities.