Securing affordable senior life insurance in Zebulon, North Carolina, involves navigating state-regulated premium structures, identifying your specific coverage needs, and understanding the underwriting requirements for applicants aged 65 and older. By comparing final expense policies, term structures, and guaranteed-issue options, residents can find a policy that balances long-term fiscal stability with the practical necessity of covering end-of-life costs.
Understanding the Market for Senior Life Insurance in North Carolina
When seeking life insurance as a senior in Zebulon, you are operating within a framework dictated by the North Carolina Department of Insurance (NCDOI). The state regulates insurers to protect policyholders, ensuring that companies maintain the capital reserves necessary to pay out claims. However, the price you pay—your premium—is determined by a combination of your age, health history, and the type of policy selected.
For many seniors in Zebulon, the objective is not to provide a massive inheritance or complex estate planning, but to secure "final expense" insurance. These are typically smaller, whole life policies designed to cover funeral costs, medical bills, and outstanding debts. Because Zebulon is a smaller community within Wake County, local residents often find that while the local cost of living influences the necessary coverage amount, the insurance products available are generally consistent with statewide North Carolina standards.
Determining Your Coverage Needs
Before approaching an agent or an online quote engine, you must quantify your financial requirements. Insurance is a tool meant to transfer risk, and you should only transfer the risk that you cannot self-insure.
- Funeral and Burial Costs: In North Carolina, the average cost of a funeral and burial can range significantly based on the chosen mortuary services and cemetery. Checking with funeral directors in the Zebulon and greater Eastern Wake County area provides a realistic estimate of the capital needed.
- Outstanding Debts: Consider remaining medical expenses, credit card balances, or personal loans. If these debts could become the responsibility of your survivors, a life insurance policy acts as a buffer.
- Estate Liquidity: If your assets are largely tied up in real estate or non-liquid investments, a life insurance policy provides cash liquidity to your heirs, preventing them from having to liquidate property quickly during an emotionally difficult time.
Types of Policies Available to Seniors
Not all life insurance policies serve the same function. Understanding the technical distinctions between these products is critical for finding an affordable premium.
1. Simplified Issue Whole Life
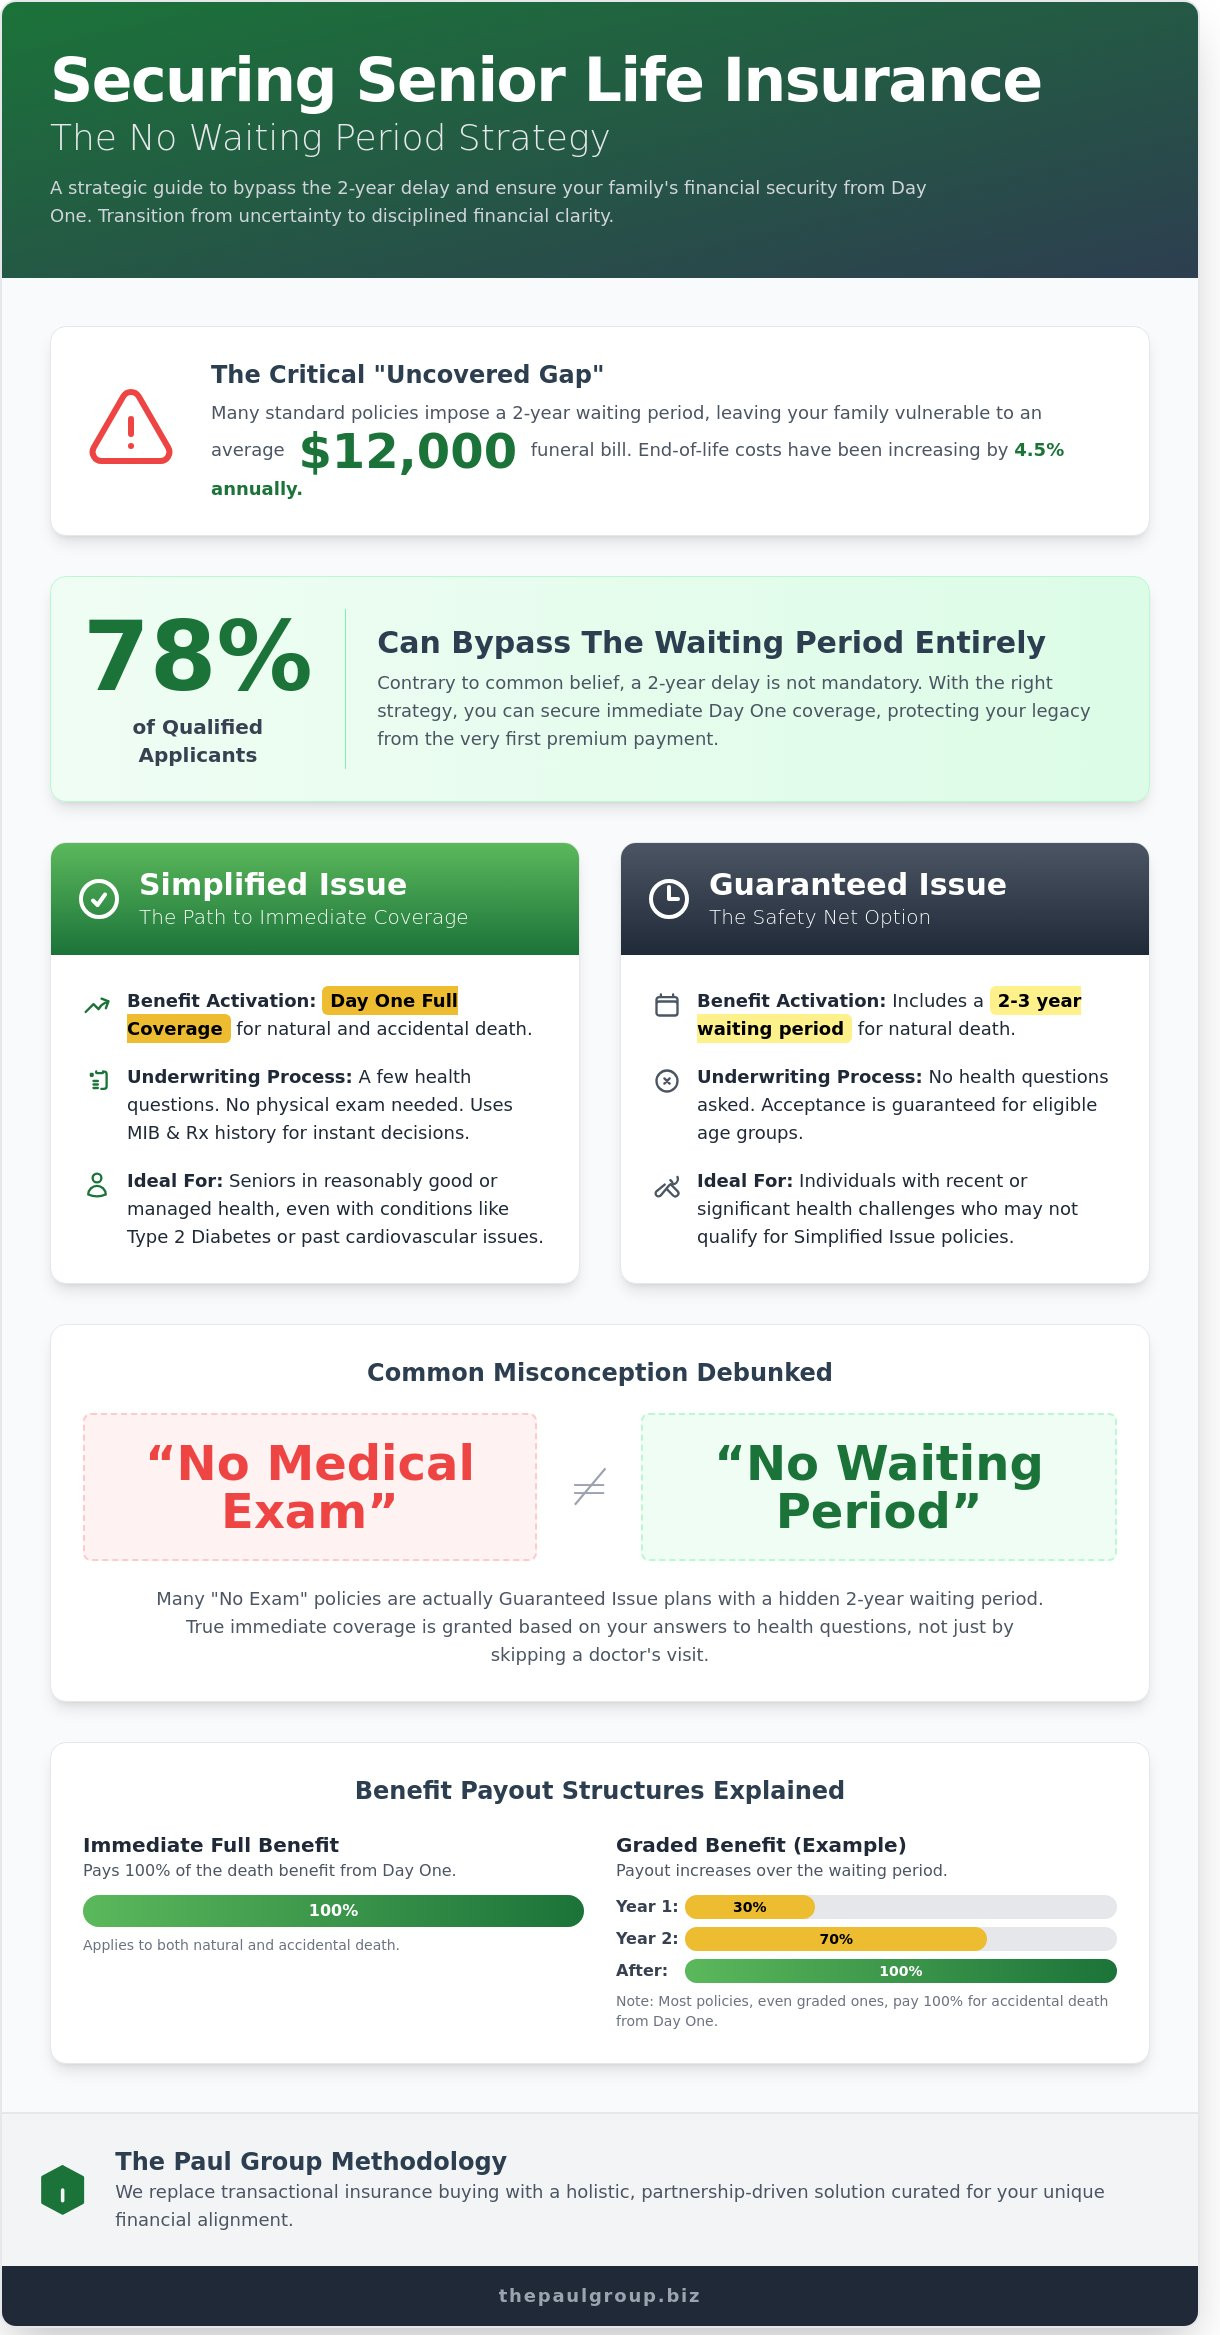
This is the most common product for seniors. It requires answering a few health questions but typically avoids a full medical examination. It is "simplified" in that the application process is fast, though premiums are higher than fully underwritten policies.
2. Guaranteed Issue Life Insurance
If you have significant pre-existing health conditions, you might be denied a standard policy. Guaranteed issue policies require no medical questions and no exam. However, they are generally the most expensive per thousand dollars of coverage and often feature a "graded death benefit," meaning if you pass away from natural causes within the first two or three years of the policy, the insurer may only refund premiums plus interest rather than the full face value.
3. Term Life Insurance
Term insurance provides coverage for a set period (e.g., 10, 15, or 20 years). While the premiums are initially the lowest, the coverage ends when the term expires. For seniors, finding term insurance beyond age 80 is increasingly rare, and the renewal premiums can become prohibitively expensive.
Comparison of Common Senior Insurance Products
The following table outlines the general characteristics of the primary insurance options available in the North Carolina market.
| Feature | Simplified Issue Whole Life | Guaranteed Issue Whole Life | Term Life Insurance |
|---|---|---|---|
| Medical Exam | Generally No | No | Sometimes |
| Health Questions | Yes | No | Yes |
| Premium Stability | Level (Fixed) | Level (Fixed) | Increases at Renewal |
| Approval Speed | Fast (Days/Weeks) | Immediate | Slower (Weeks) |
| Best For | Healthy/Mild Health Issues | Significant Health Issues | Short-term Coverage Needs |
The Role of Underwriting and Health Classes
Even at an older age, your "health class" plays a significant role in affordability. Insurance carriers use underwriting—the process of assessing risk—to assign you a rate. In North Carolina, insurers look at:
- Age: The primary driver of cost.
- Tobacco Usage: Smokers typically pay two to three times more for the same amount of coverage as non-smokers. If you have quit, many insurers require you to be nicotine-free for at least 12 months to qualify for non-smoker rates.
- Chronic Conditions: Conditions such as diabetes, heart disease, or past stroke incidents will significantly impact your eligibility for simplified issue plans.
- Prescription Medication History: Insurers in 2026 often utilize the MIB (Medical Information Bureau) and pharmacy benefit databases to verify the medications you are taking, which acts as a proxy for your overall health status.
Tips for Finding Affordable Premiums in Zebulon
Affordability is relative to the face value of the policy. To keep costs manageable while ensuring your needs are met, follow these strategic steps:
- Shop Around via Independent Agents: Do not rely on a single company’s captive agent. Independent agents in North Carolina can pull quotes from multiple A-rated carriers to compare pricing structures.
- Avoid Over-insuring: Do not purchase a $50,000 policy if your end-of-life expenses will realistically only cost $15,000. Every thousand dollars of death benefit increases your monthly premium.
- Annual Review: If your financial situation changes—such as paying off a mortgage or a child becoming financially independent—you may be able to reduce your coverage amount, thereby lowering your monthly premium.
- Automatic Payments: Many insurers offer a discount if you set up your premiums to be paid via automated bank draft (EFT) rather than receiving paper bills.
Common Pitfalls to Avoid
The senior life insurance market is rife with marketing tactics that can lead to poor decisions. Avoid these common mistakes:
- Missing the "Graded Benefit" Fine Print: Always read the policy document to see if there is a waiting period. If a policy advertises "no questions asked," it almost certainly has a graded benefit period. Ensure you understand what happens if you pass away shortly after the policy start date.
- Replacing Existing Policies: Never cancel an existing, older life insurance policy to buy a new one without a thorough, documented reason. Older policies often have lower rates and different cash value growth potential that cannot be replicated in a new policy issued at an older age.
- Falling for "No Exam" Myths: While "no exam" is convenient, it is not always the cheapest. If you are in excellent health, applying for a fully underwritten policy (with a paramedical exam) might secure you a "preferred" or "super-preferred" rate that is significantly cheaper than the "no exam" simplified issue alternatives.
FAQ: Common Questions Regarding Senior Coverage
1. Does my North Carolina residency affect my life insurance rates? State of residence primarily affects the regulatory environment and the specific insurers licensed to do business in the state. While your specific zip code in Zebulon may be used by actuaries to assess risk, the primary drivers of your rate remain your age, health, and the type of policy selected.
2. Can I get life insurance if I have a pre-existing condition? Yes. You may qualify for simplified issue or guaranteed issue policies. These plans are designed specifically for individuals who would not qualify for traditional, fully underwritten life insurance due to medical history.
3. When is the best time to purchase a policy? The best time is now. Life insurance rates increase with every passing year. Waiting to buy coverage will only result in a higher permanent premium once you finally do apply.
4. Can I change my policy after I buy it? Generally, you can decrease the death benefit of a whole life policy to reduce premiums, but you cannot increase it without undergoing new underwriting. Because of this, it is vital to estimate your needs accurately from the start.
5. Are my life insurance benefits taxable in North Carolina? Typically, life insurance death benefits are income-tax-free for the beneficiaries. However, the proceeds may be included in your gross estate for federal estate tax purposes if you own the policy, which is a consideration for very large estates.
Recommendation for Next Steps
If you are a resident of Zebulon looking for coverage, your first step should be to compile a list of your monthly income, your existing savings, and the estimated costs of your final arrangements. Once you have a clear picture of your budget and your goal, contact a licensed North Carolina life insurance broker. Ask them to run a comparison of "Simplified Issue" whole life plans from at least three different highly rated carriers.
Ensure that the agent explains any potential waiting periods and confirms that the premiums are "level," meaning they will not increase as you age. By taking a methodical approach to evaluating these products, you can secure the necessary coverage to protect your loved ones while maintaining your financial independence.
Disclaimer: This article is for informational purposes only and does not constitute financial, legal, or medical advice. Insurance requirements and eligibility are subject to the specific terms of the insurance contract and the regulations of the North Carolina Department of Insurance. Consult with a qualified insurance professional regarding your personal situation.