Determining whether SafeInsurance auto insurance plans are worth the investment requires balancing your individual risk profile, coverage requirements, and budgetary constraints against the company’s service model. For many drivers, these plans offer a competitive middle ground, providing essential liability and comprehensive protection while maintaining a streamlined digital interface that appeals to modern, cost-conscious consumers.
Understanding the SafeInsurance Model
SafeInsurance operates primarily as a technology-forward provider, leveraging digital underwriting and automated claims processing to reduce overhead costs. By minimizing the need for traditional brick-and-mortar agency networks, the company often passes those savings to the policyholder in the form of lower premiums compared to legacy insurers.
However, the "worth" of an insurance policy extends beyond the initial monthly or semi-annual quote. To evaluate the value proposition, one must look at the structural components of their offerings: liability coverage, collision and comprehensive segments, and the availability of supplemental riders such as roadside assistance, rental car reimbursement, and gap insurance.
Analyzing Coverage Adequacy
The most critical factor in assessing any insurance plan is not its cost, but its capacity to protect your financial assets. SafeInsurance follows industry-standard coverage definitions, which simplifies the comparison process for most consumers.
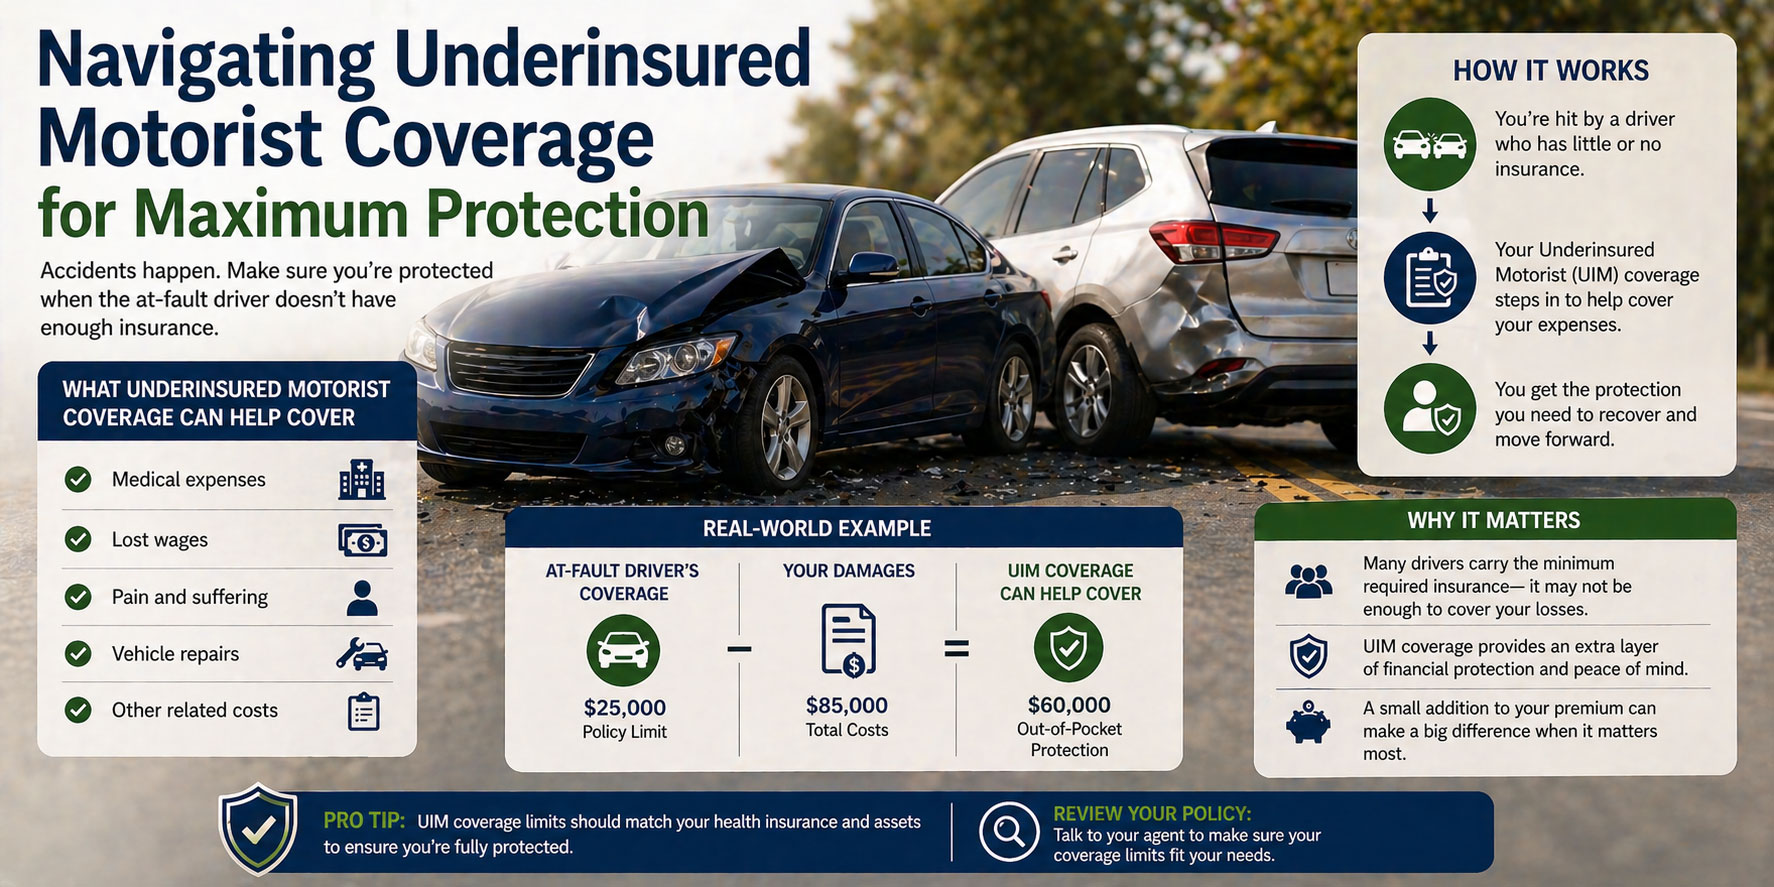
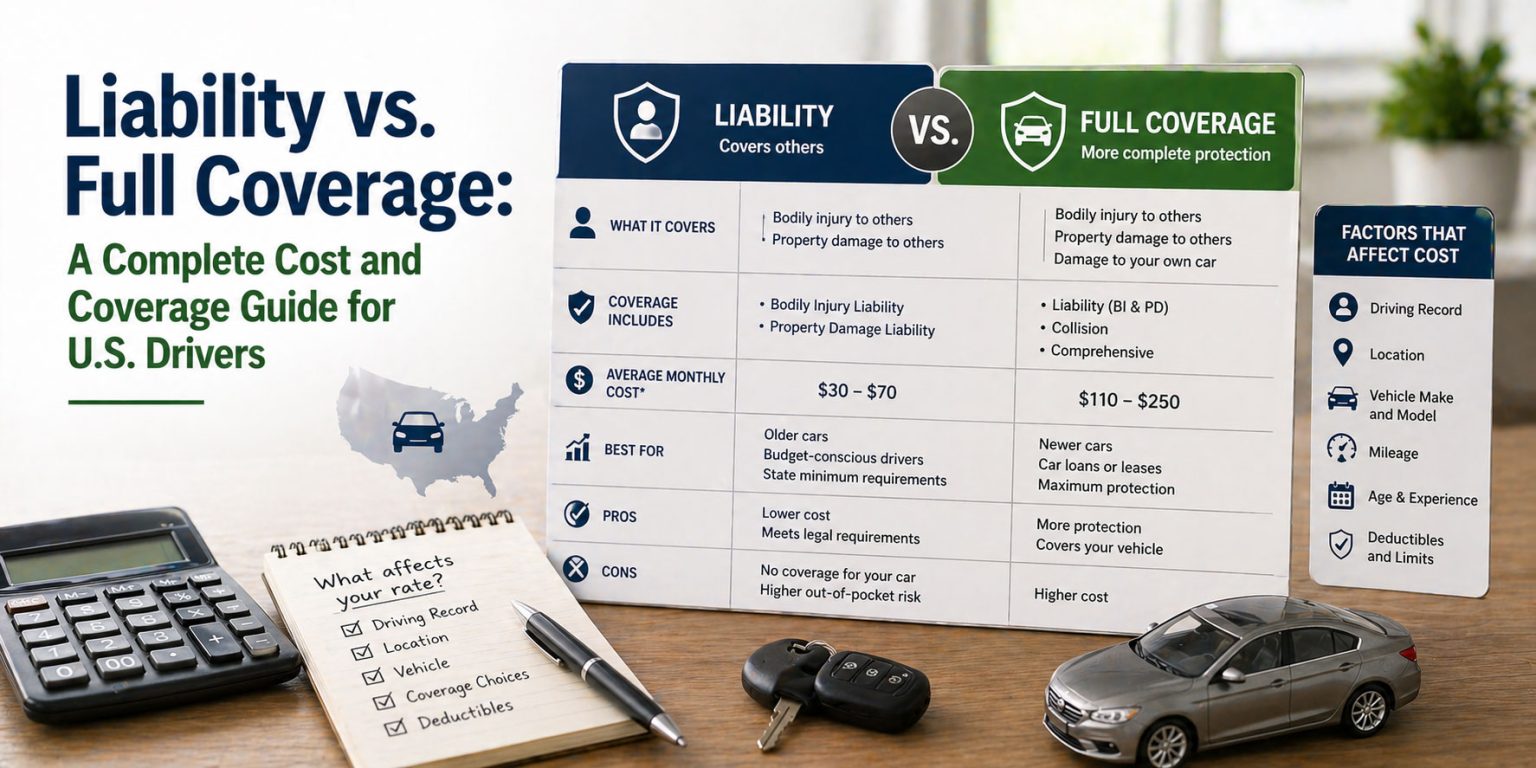
- Liability Coverage: This covers bodily injury and property damage for which you are legally responsible. SafeInsurance plans generally allow for flexible limits, enabling drivers to exceed state-mandated minimums to protect personal net worth.
- Collision and Comprehensive: These are the "physical damage" components. If you have an auto loan, your lender likely requires these. SafeInsurance offers customizable deductibles—the amount you pay out-of-pocket before insurance kicks in—which is a primary lever for adjusting your premium cost.
- Medical Payments (MedPay) and PIP: Depending on your state, SafeInsurance provides Personal Injury Protection (PIP) or MedPay to cover immediate medical expenses for you and your passengers regardless of fault.
Cost vs. Value: The 2026 Perspective
As of 2026, the auto insurance market is characterized by fluctuating loss costs driven by the rising complexity of vehicle repair. Modern vehicles equipped with advanced driver-assistance systems (ADAS) utilize expensive sensors and specialized electronics, meaning a minor collision now carries a higher repair bill than it did a decade ago.
SafeInsurance’s value lies in its ability to offer competitive rates for drivers with clean records. Because their underwriting is heavily data-driven, they tend to reward policyholders who demonstrate safe driving habits. If you are a driver with a low risk profile, you are likely to find their pricing to be highly favorable. Conversely, high-risk drivers—those with multiple recent claims or significant moving violations—may find that the lack of personalized agency support makes the transition to a more traditional, high-touch insurance carrier more beneficial.
The Role of Digital Claims Processing
One of the defining features of SafeInsurance is its mobile-first approach. For a digitally savvy user base, the ability to initiate a claim, upload photos of vehicle damage, and track repair status through an application is a significant time-saver.
- Efficiency: Automated intake systems can lead to faster initial assessments of claims.
- Transparency: Real-time updates via the customer portal reduce the anxiety associated with the "waiting game" of traditional insurance adjustments.
- Limitations: The reliance on digital tools can be a drawback during complex, multi-vehicle, or high-liability accidents where legal representation or human negotiation is necessary. If you prefer speaking to a dedicated local agent who knows your history, you may find the digital interface limiting.
Comparative Analysis: SafeInsurance vs. Traditional Carriers
| Feature | SafeInsurance | Traditional Carriers |
|---|---|---|
| Premium Costs | Generally lower due to tech-efficiency | Often higher due to agent commissions |
| Claim Support | Digital-first; app-based | Hybrid; agent and call center |
| Customization | Standardized, easy-to-select tiers | High level of manual policy tailoring |
| Customer Service | Automated, fast, high volume | Personalized, relationship-based |
Determining If SafeInsurance Is Right for You
To decide if these plans are worth it, conduct an audit of your current situation using these three criteria:
- Vehicle Age and Value: If you drive an older vehicle with low market value, the premiums for comprehensive and collision coverage may not be worth the payout in the event of a total loss. In this scenario, SafeInsurance’s competitive base liability rates make them a strong choice.
- Driving History: If you have a clear record, the algorithmic pricing of SafeInsurance often provides lower rates than companies that bake the cost of "risky customers" into their universal pricing tiers.
- Communication Preference: If you value the ability to handle your insurance entirely via smartphone, SafeInsurance is likely a perfect fit. If you find comfort in having a physical office or a personal agent to contact during a crisis, you may find the lack of face-to-face interaction a point of contention.
Frequently Asked Questions
Does SafeInsurance offer multi-policy discounts? Yes. SafeInsurance typically provides incentives for bundling auto insurance with other products like renters or homeowners insurance. Bundling is often the most effective way to lower your overall cost, as it reduces the insurer's customer acquisition costs and improves retention, which they pass back to the consumer.
How does SafeInsurance handle total loss claims? When a vehicle is declared a total loss, SafeInsurance uses market-value assessments based on comparable vehicle sales in your specific region. It is always recommended to review the "stated value" or "agreed value" clauses in your policy documentation to understand how your specific car will be valued before an accident occurs.
Is it difficult to switch to SafeInsurance? The transition is generally seamless. Because they operate as a digital-first organization, their onboarding process allows for instant quote generation and policy activation. It is essential to ensure you do not cancel your existing policy until your SafeInsurance coverage is fully active to avoid any gaps in financial responsibility.
Does SafeInsurance cover rental cars? Yes, optional rental car reimbursement is available. This rider pays for a rental vehicle while your primary vehicle is undergoing covered repairs. This is worth considering if you rely on your car for daily commuting and do not have access to alternative transportation.
Are their roadside assistance plans worth adding? If your vehicle is older or lacks a manufacturer-provided roadside service, this add-on is often very affordable. It typically covers lockout services, flat tire changes, and towing, which can save you significant money in a single emergency incident compared to paying for a third-party service provider out-of-pocket.
Next Steps for Policyholders
Before committing to a policy, request a "declarations page" from your current provider and compare it line-by-line with a quote from SafeInsurance. Pay close attention to the liability limits; ensure that you are not under-insuring yourself just to chase a lower monthly premium.
If you decide to proceed, verify that the coverage effective date aligns with your current policy expiration to ensure continuous coverage. If you are financing your vehicle, remember to update your lienholder information within the SafeInsurance portal immediately upon policy issuance to satisfy the legal requirements of your loan agreement.