AIG Direct senior life insurance for ages 55 and older provides specialized coverage options ranging from term life to guaranteed-issue whole life policies. These products, now primarily issued through Corebridge Financial, offer financial protection for final expenses, outstanding debts, and legacy planning without the traditional requirement of rigorous medical examinations for many senior-specific plans.
As of 2026, the landscape of senior life insurance has evolved to prioritize digital accessibility and "living benefits." For individuals aged 55 and older, securing life insurance is no longer just about a death benefit; it is increasingly about flexible financial tools that can assist with long-term care or critical illness during one's lifetime. AIG Direct remains a prominent distribution channel for these products, offering a streamlined interface for seniors to compare rates and select coverage that aligns with their specific health profile and financial goals.
Understanding the Relationship Between AIG Direct and Corebridge Financial
To navigate the current market, it is essential to understand the institutional branding. While many consumers still search for "AIG Direct," the underlying insurance carrier is Corebridge Financial. AIG completed the separation of its life and retirement business into this independent entity over the last few years. Consequently, when you apply through AIG Direct in 2026, you are typically purchasing a policy underwritten by American General Life Insurance Company (AGL) or The United States Life Insurance Company in the City of New York (US Life), both of which are Corebridge Financial subsidiaries.
This transition has not diminished the product quality; rather, it has allowed for a more focused approach to senior-specific risk pools. Corebridge maintains high financial strength ratings from agencies like A.M. Best and Standard & Poor’s, ensuring that the long-term promises made to policyholders aged 55 and older remain secure.
Primary Insurance Options for Seniors 55 and Older
When exploring AIG Direct, seniors generally encounter three primary categories of life insurance. Choosing the right one depends on your health status, budget, and the specific reason for seeking coverage.
1. Guaranteed Issue Whole Life Insurance (GIWL)
This is perhaps the most popular product for seniors between the ages of 50 and 80 who may have moderate to significant health issues. The defining characteristic of GIWL is that there are no medical exams and no health questions. If you meet the age requirements, you cannot be turned down.
- Graded Death Benefit: A critical technical detail of GIWL is the two-year graded death benefit. If the insured passes away from natural causes within the first two years of the policy, the beneficiaries do not receive the full face value. Instead, they receive 110% of the premiums paid. After the two-year mark, the full death benefit is payable for any cause of death.
- Fixed Premiums: Once the policy is issued, the monthly or annual premium is locked in for life. It will never increase regardless of your age or changes in health.
- Cash Value Accumulation: As a form of whole life insurance, these policies build a small amount of cash value over time, which can be accessed via policy loans if necessary.
2. Term Life Insurance
For seniors aged 55 to 75 who are in relatively good health, term life insurance offers the highest amount of coverage for the lowest initial cost. This is often used to cover specific financial obligations that have an expiration date, such as a 10-year mortgage or the remaining years until a spouse qualifies for maximum Social Security benefits.
- Duration: Terms typically range from 10, 15, to 20 years for the 55+ demographic.
- Convertibility: Most AIG Direct term policies include a conversion rider, allowing the policyholder to switch to a permanent policy without a new medical exam before the term ends or by a certain age (usually 70 or 75).
- Underwriting: Unlike guaranteed issue plans, term life requires medical underwriting. This may include a paramedical exam, though "lab-lift" programs in 2026 often allow healthy seniors to qualify using recent electronic health records instead of a physical blood draw.
3. Quality of Life (QoL) Insurance
This is a specialized type of universal or term insurance that includes "accelerated benefit riders." These riders allow the policyholder to access a portion of the death benefit while they are still alive if they are diagnosed with a qualifying chronic, critical, or terminal illness. For seniors, this serves as a hybrid between life insurance and long-term care preparation.
Eligibility and Requirements for Seniors
The eligibility criteria for AIG Direct products are strictly defined by age and, in some cases, residency. In 2026, the digital application process has been optimized to provide instant or near-instant decisions for many applicants.
Age Brackets
- Ages 50–80: Eligible for Guaranteed Issue Whole Life.
- Ages 50–75: Typically the window for new Term Life applications, though some 10-year terms may be available up to age 80 depending on the state.
- Ages 81–85: Coverage options become significantly limited and are usually restricted to specific final expense products with lower face values.
Health Documentation
For underwritten policies, AIG Direct utilizes the Medical Information Bureau (MIB) and prescription drug databases to verify applicant history. This means that even if a physical exam is waived, the insurance company will still have a comprehensive view of your health history. It is vital to be transparent during the application to avoid "material misrepresentation," which could lead to a claim denial during the two-year contestability period.
Cost Analysis: What to Expect in 2026
The cost of senior life insurance is primarily dictated by the "issue age." The older you are when you start the policy, the higher the premium. However, other factors also play a significant role.
- Gender: Statistically, women have a longer life expectancy than men, which generally results in lower premiums for female applicants of the same age and health status.
- Tobacco Use: Smokers or users of nicotine replacement therapies will pay significantly more—often double the rate of non-smokers.
- Coverage Amount: Senior policies through AIG Direct often start as low as $5,000 for final expenses and can go into the millions for term insurance.
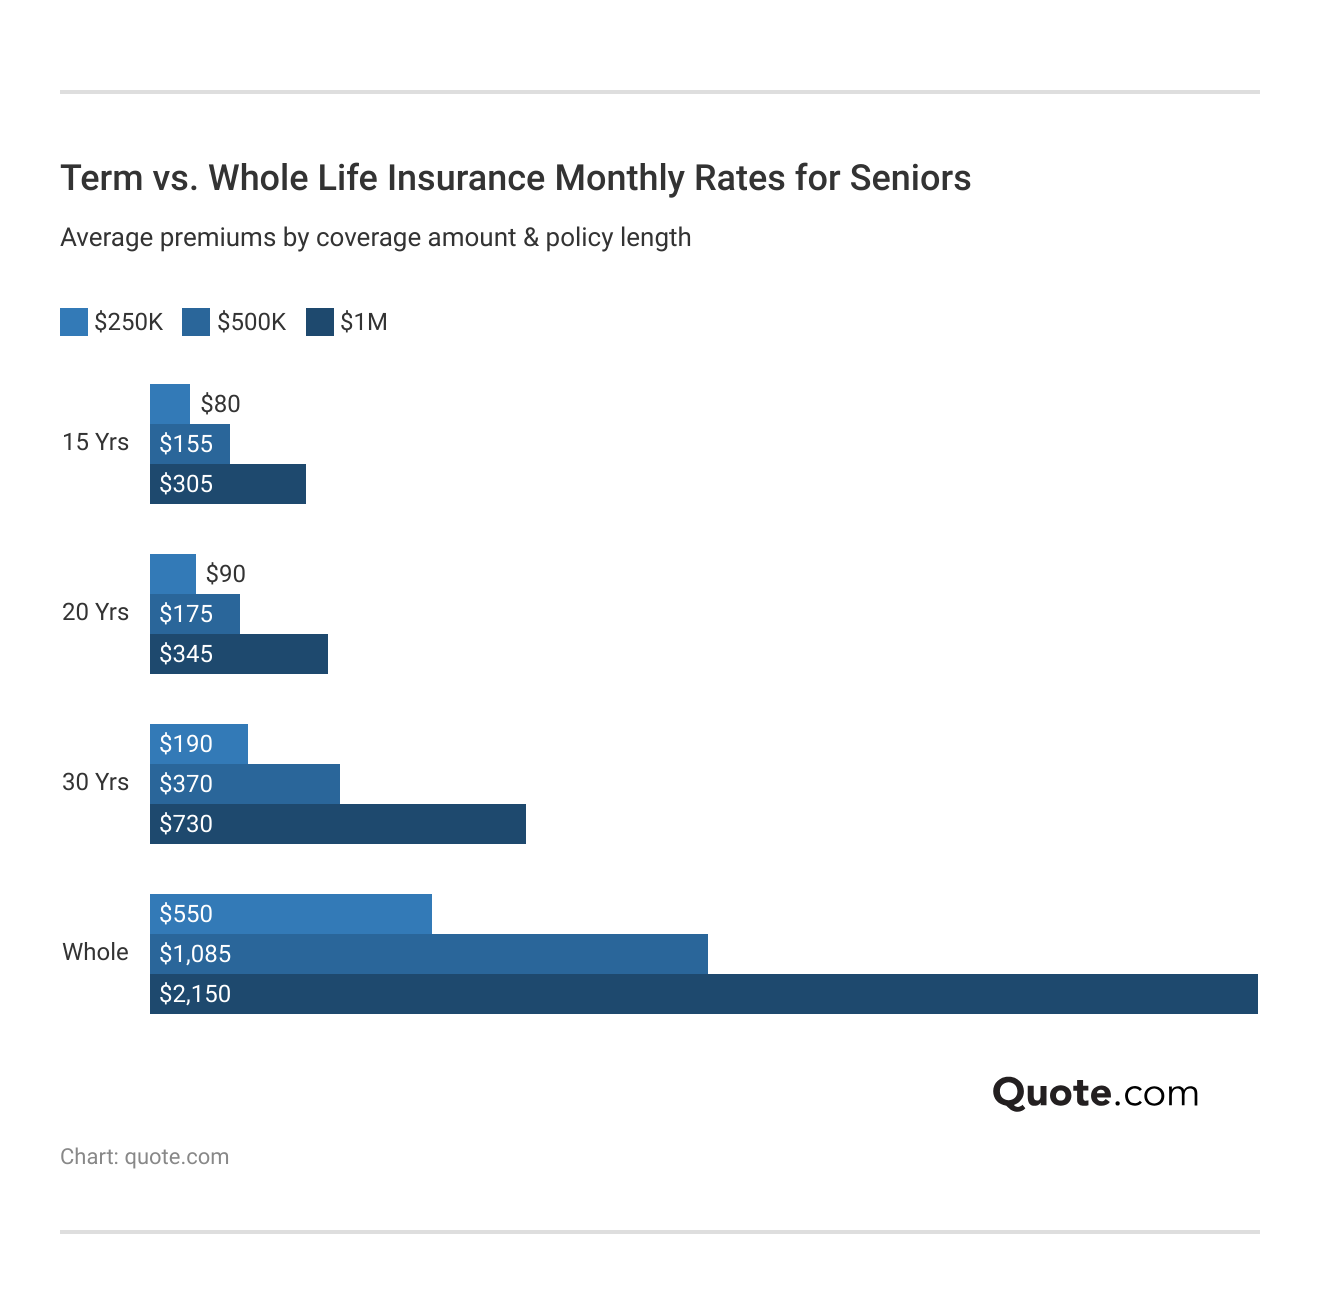
2026 Comparison Table: Estimated Monthly Premiums (Non-Smoker, Standard Health)
| Age at Issue | Product Type | Coverage Amount | Estimated Male Monthly Premium | Estimated Female Monthly Premium |
|---|---|---|---|---|
| 55 | 10-Year Term | $100,000 | $35 - $50 | $25 - $40 |
| 65 | 10-Year Term | $100,000 | $85 - $110 | $60 - $80 |
| 55 | Guaranteed Issue | $10,000 | $40 - $55 | $30 - $45 |
| 65 | Guaranteed Issue | $10,000 | $65 - $80 | $50 - $65 |
| 75 | Guaranteed Issue | $10,000 | $110 - $140 | $85 - $110 |
Note: These figures are illustrative estimates for 2026. Actual quotes depend on specific underwriting data and state-specific regulations.
The Application Process: Step-by-Step
AIG Direct focuses on a "direct-to-consumer" model, which simplifies the acquisition of coverage.
- Request a Quote: Use the online calculator to input your age, gender, state, and desired coverage amount.
- Phone Consultation: For many senior products, a licensed agent will call to finalize the application. They will ask specific health questions if you are applying for an underwritten policy.
- Electronic Signature: Documents are sent via email for secure digital signing.
- Underwriting Review: For term life, the carrier reviews your medical records. For guaranteed issue, this step is skipped, and the focus is solely on age and identity verification.
- Policy Issue: Once approved, the first premium is drafted, and the policy becomes active. In 2026, most policyholders receive their contract via a secure digital portal rather than physical mail, though paper copies remain an option upon request.
Advantages and Disadvantages for the 55+ Demographic
Pros
- Accessibility: The guaranteed issue product is a safety net for seniors who have been declined elsewhere due to diabetes, heart disease, or other chronic conditions.
- Living Benefits: The Quality of Life riders are particularly valuable for seniors who want to protect their retirement savings from being depleted by medical bills.
- Financial Stability: Being backed by Corebridge Financial provides peace of mind regarding the company's ability to pay future claims.
Cons
- Graded Benefit Period: The two-year wait on guaranteed issue plans is a significant drawback for those in very poor health.
- Cost of Small Policies: On a per-thousand-dollar basis, small final expense policies are much more expensive than large term policies.
- Age Limits: Once an individual passes 80, the options through AIG Direct narrow significantly, making early planning essential.
Common Mistakes to Avoid
Seniors often make the mistake of waiting too long to apply, thinking that their health will remain stable. In the insurance world, age is the primary driver of cost. Even a one-year delay can increase the lifetime cost of a policy by thousands of dollars.
Another common error is failing to distinguish between "Accidental Death" and "Life Insurance." Some direct mail offers are for accidental death only, which does not pay out for deaths caused by illness or natural aging. AIG Direct offers true life insurance, but it is important to confirm that the policy covers all causes of death (subject to the two-year contestability and graded benefit rules).
Lastly, do not overlook the importance of beneficiary designations. Ensure your beneficiaries are aware of the policy and that their contact information is kept current with Corebridge Financial. In 2026, digital beneficiary management tools make this process easier than ever.
Verification and Financial Strength
Before committing to a policy, seniors should verify the current standing of the insurer. As of 2026, Corebridge Financial (the issuer of AIG Direct policies) maintains strong ratings:
- A.M. Best: A (Excellent)
- Standard & Poor’s: A+ (Strong)
- Moody’s: A2 (Good)
These ratings reflect the company's balance sheet strength and its ability to meet ongoing insurance obligations. For further verification, consumers can visit the National Association of Insurance Commissioners (NAIC) to view the company’s complaint index and financial filings.
Frequently Asked Questions
Does AIG Direct require a physical medical exam for seniors?
It depends on the policy type. For Guaranteed Issue Whole Life, there is no medical exam and no health questions. For Term Life or Quality of Life policies, a medical exam may be required, although many healthy seniors in 2026 qualify for "automated underwriting" which uses digital health data to bypass the physical exam requirement.
What happens if I stop paying my premiums?
For term life insurance, the policy will lapse after a grace period (usually 31 days), and the coverage will end with no value returned. For whole life policies (including guaranteed issue), the policy may have accumulated some "cash value." If you stop paying, you may be able to use that cash value to purchase a "reduced paid-up" policy or take the cash surrenders value, though this will end the insurance coverage.
Can I change my coverage amount later?
It is generally easier to decrease coverage than to increase it. If you wish to decrease your death benefit to lower your premium, most Corebridge policies allow this. However, increasing your coverage usually requires a brand-new application and new underwriting based on your current age and health.
Is the death benefit taxable for my children?
In most cases, life insurance death benefits are passed to beneficiaries income tax-free. However, if the death benefit is large enough to make your total estate exceed federal or state estate tax thresholds, there may be estate tax implications. As of 2026, it is advisable to consult with a tax professional regarding current estate tax limits.
What is the "Free Look" period?
AIG Direct policies include a "Free Look" period, typically ranging from 10 to 30 days depending on your state. During this time, you can review the physical or digital policy document. If you are not satisfied for any reason, you can cancel the policy and receive a full refund of any premiums paid.
Final Recommendation for Seniors
If you are 55 or older and have dependents, outstanding debt, or concerns about funeral costs, AIG Direct remains a viable and highly accessible option. For those in good health, a 10-year or 15-year term policy provides the most significant protection for the lowest cost. However, for those with pre-existing conditions, the Guaranteed Issue Whole Life plan is a vital tool for ensuring that final expenses do not become a financial burden on surviving family members. Always compare the "Quality of Life" riders against standard policies to determine if the ability to access funds early is worth the potential difference in premium.