Bestow offers a streamlined, 100% digital term life insurance platform that eliminates the need for medical exams, needles, and waiting weeks for lab results. By leveraging proprietary algorithmic underwriting, Bestow provides instant coverage decisions for healthy individuals, offering term lengths from 10 to 30 years and coverage amounts up to $1.5 million.
Life insurance has historically been a slow, invasive process involving paramedical exams and manual record reviews. In 2026, the demand for "insurtech" solutions has solidified, and Bestow remains a primary contender in the accelerated underwriting space. This review provides an objective analysis of Bestow’s offerings, technical requirements, and how its no-medical-exam model compares to traditional life insurance products.
Understanding the "No Medical Exam" Mechanism
When consumers hear "no medical exam," they often confuse it with "no health questions." With Bestow, the "no medical exam" refers specifically to the absence of a physical check-up by a nurse or doctor. This is achieved through accelerated underwriting, a data-driven process that replaces physical samples with digital records.
Bestow’s platform connects to several large-scale databases to verify your health profile in real-time. This includes the Medical Information Bureau (MIB), which tracks previous insurance applications; LexisNexis, for identity and public record verification; and various prescription drug databases (like Milliman IntelliScript). By cross-referencing your application answers against these databases, Bestow’s algorithm determines your risk level within minutes.
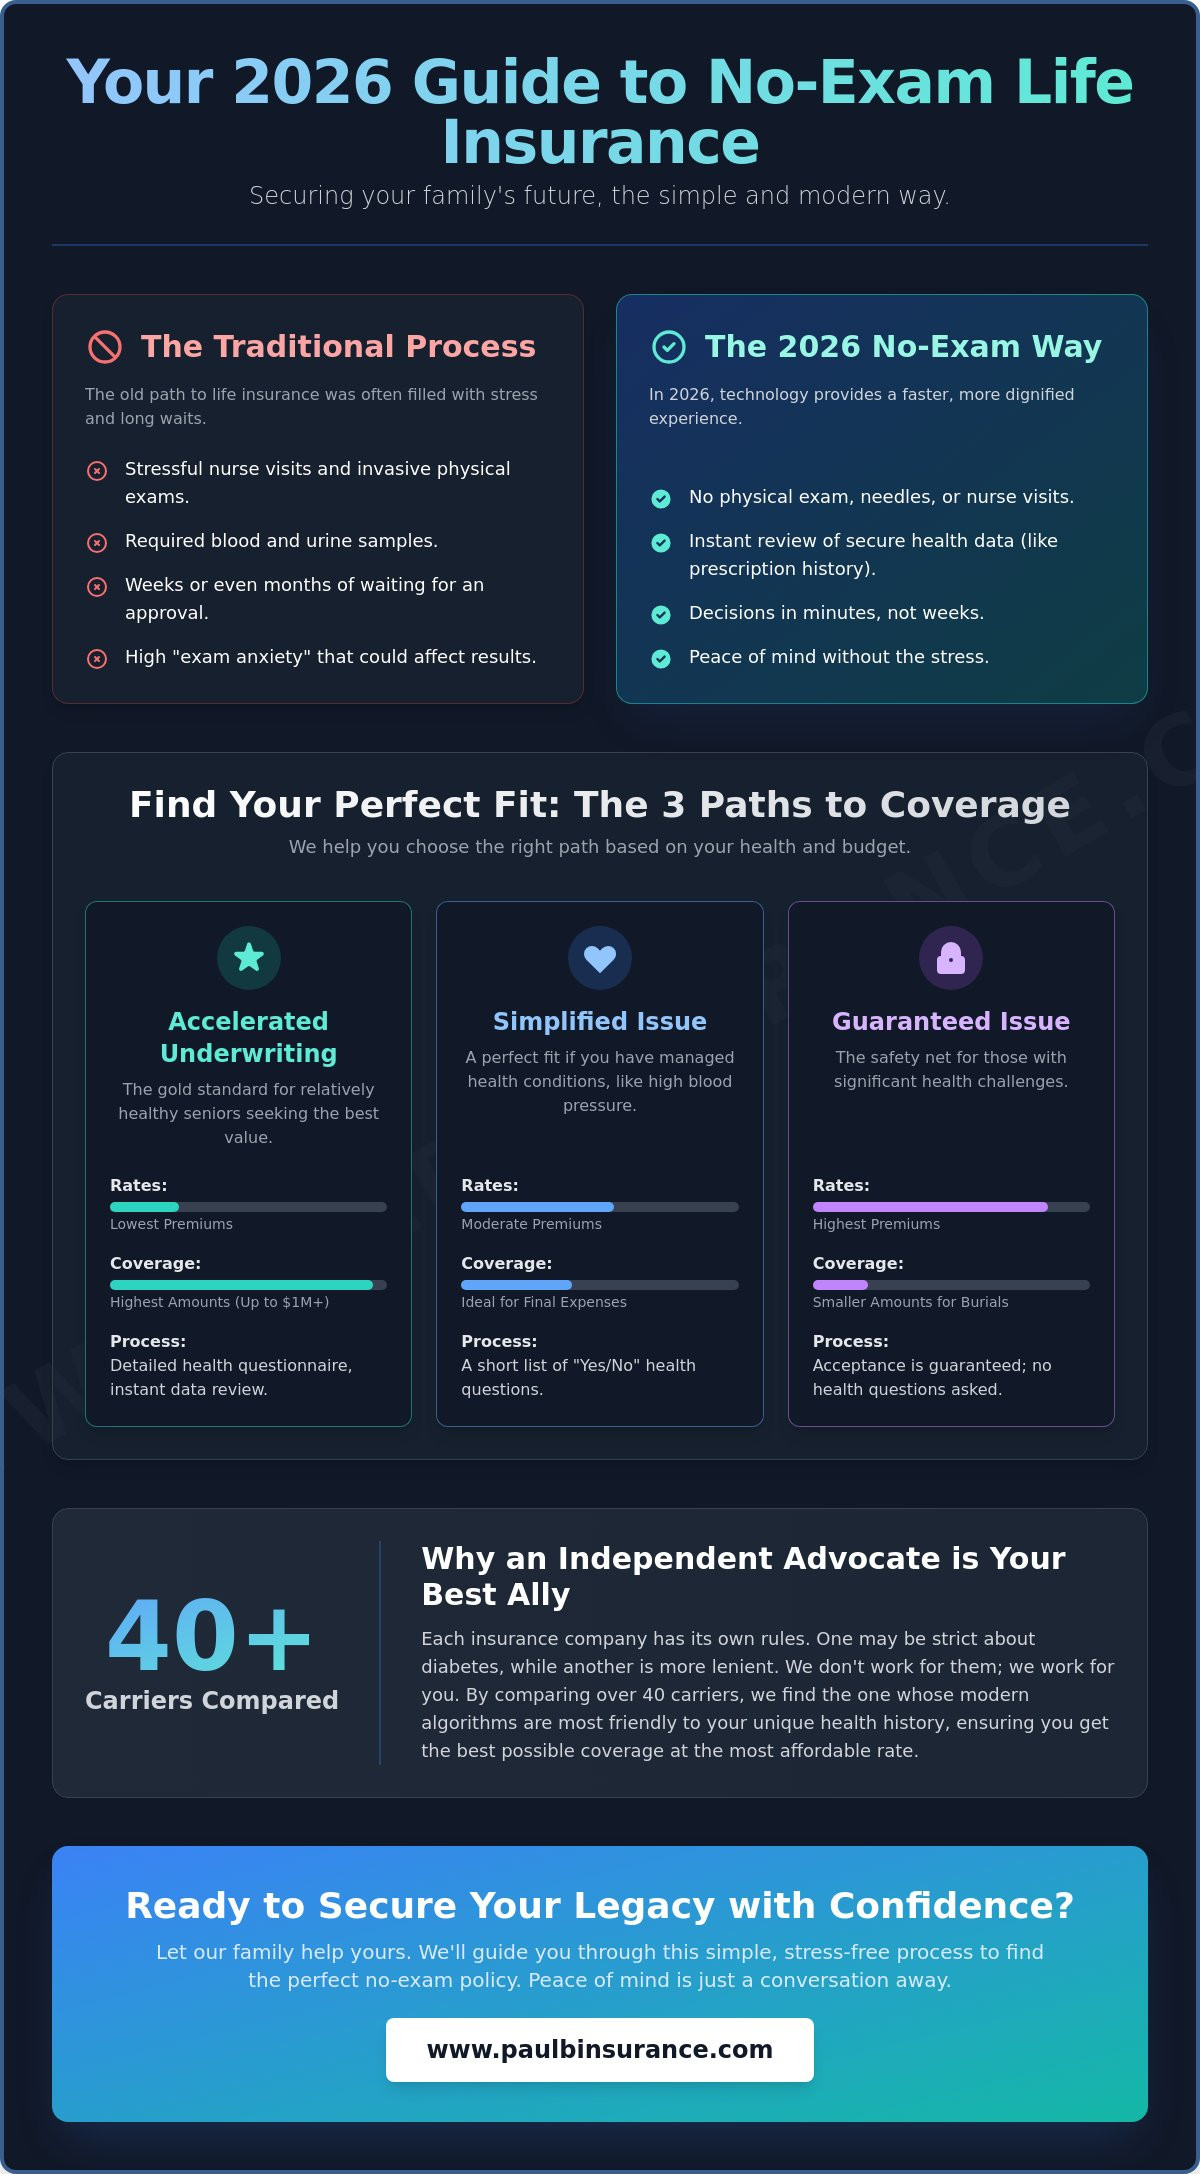
It is important to distinguish this from Simplified Issue or Guaranteed Issue insurance. Simplified issue policies often have higher premiums because the insurer is taking a "blind" risk. Bestow’s accelerated underwriting allows them to keep premiums comparable to traditional policies because they are still technically underwriting you—they are just doing it with data instead of blood draws.
Eligibility and Technical Prerequisites
While the process is convenient, Bestow is not available to everyone. The platform is specifically designed for individuals who fall within a certain age and health "sweet spot."
Age and Term Limits
In 2026, Bestow generally accepts applicants between the ages of 18 and 60. The term lengths available are usually 10, 15, 20, 25, or 30 years. However, your age dictates which terms you can select. For example, a 60-year-old may not be eligible for a 30-year term, as the policy must typically expire before the insured reaches age 80 or 85.
Health and Lifestyle Requirements
Because Bestow relies on data rather than physical exams, they are highly selective. To qualify for their best rates (or to be approved at all), applicants typically need:
- A body mass index (BMI) within a healthy range.
- No history of major chronic illnesses such as cancer, heart disease, or stroke.
- A clean driving record (no DUIs or reckless driving charges in the last several years).
- U.S. citizenship or a valid permanent resident status (Green Card).
If you have a complex medical history or participate in high-risk hobbies (like scuba diving or amateur aviation), Bestow’s algorithm may be unable to approve you instantly. In such cases, you might be directed toward a traditional insurer that uses human underwriters to evaluate nuance.
The Bestow Application Process: Step-by-Step
The primary appeal of Bestow is the speed of its application. For a prepared applicant, the process from start to finish rarely takes more than 10 to 15 minutes.
- The Quote Phase: You begin by entering basic information: date of birth, gender, height, weight, and zip code. This generates an initial estimate of your monthly premium.
- Detailed Health Questionnaire: Unlike some legacy carriers, Bestow's questions are direct and digital-first. You will answer questions about tobacco use, alcohol consumption, family medical history, and existing prescriptions.
- Data Authorization: To skip the medical exam, you must grant Bestow permission to pull your records from the MIB and prescription databases. This is a secure, encrypted process.
- Instant Decision: Once the data is analyzed, the platform provides one of three outcomes:
- Approved: You are offered a policy at a specific rate.
- Declined: The algorithm identifies a risk factor that Bestow cannot cover.
- Referral: Occasionally, the system may need a moment of manual review, though Bestow strives for 100% automated decisions.
- Policy Activation: If approved, you can review the policy documents, add beneficiaries, and make your first premium payment via credit card or bank transfer to put the coverage "in force."
Analyzing Coverage Options and Financial Security
One concern often raised with digital-first insurance companies is their long-term stability. It is vital to understand that while Bestow provides the technology and the interface, the policies are typically issued and backed by established industry giants.
As of 2026, Bestow continues its partnership with North American Company for Life and Health Insurance®, a member of the Sammons Financial Group. North American has been in business since 1886 and consistently holds high financial strength ratings.
Financial Ratings Context
- A.M. Best: Generally rated A+ (Superior).
- S&P Global: Generally rated A+ (Strong).
These ratings indicate that the entity responsible for paying out your death benefit is financially sound and capable of meeting its long-term obligations. When you buy a policy through Bestow, you are getting the speed of a startup with the financial backing of a century-old institution.
Comparison: Bestow vs. Traditional vs. Simplified Issue
| Feature | Bestow (Accelerated) | Traditional Life Insurance | Simplified Issue |
|---|---|---|---|
| Medical Exam | None | Required (Blood, Urine, Vitials) | None |
| Approval Time | Minutes | 4 to 8 Weeks | 24 to 72 Hours |
| Max Coverage | Up to $1.5M - $2M | $10M+ | Usually capped at $50,000 - $100,000 |
| Cost | Competitive/Low | Lowest (for very healthy) | High |
| Application | 100% Digital | Paper/Digital + Interview | Digital/Phone |
| Riders | Limited | Extensive (Waiver, etc.) | Minimal |
Limitations and Potential Drawbacks
While the convenience of Bestow is undeniable, "no medical exam" insurance has inherent trade-offs that might make it unsuitable for certain individuals.
1. Lack of Customization (Riders)
Traditional life insurance policies often allow you to add "riders"—optional benefits such as a Waiver of Premium (which pays your premiums if you become disabled) or a Child Term Rider. Bestow’s model is built for speed and simplicity, which often means these customizations are unavailable. If you require a highly tailored policy with living benefits, Bestow may feel too restrictive.
2. Term Life Only
Bestow focuses exclusively on Term Life Insurance. They do not offer Whole Life, Universal Life, or Variable Life products. For those who want their life insurance to serve as an investment vehicle or provide permanent coverage for estate planning, Bestow is not the right fit.
3. Maximum Coverage Ceilings
While $1.5 million is sufficient for many families, high-net-worth individuals or those with significant business liabilities may find Bestow’s limits too low. If you need $5 million or $10 million in coverage, you will almost certainly need to undergo a traditional medical exam with a different carrier.
4. Binary Decisions
The automated nature of Bestow means there is little room for "gray areas." If you have a well-managed health condition that a human underwriter might view favorably after reading a doctor’s note, Bestow’s algorithm might still trigger a hard "Decline" because it cannot interpret the nuance of your management plan.
Cost Considerations and Pricing Stability
Bestow’s pricing is transparent. Because they do not have the overhead of thousands of independent agents or the cost of processing physical medical exams, they pass those savings on to the consumer. In 2026, a healthy 30-year-old non-smoker can often secure a $500,000, 20-year term policy for less than $30 per month.
It is important to note that Bestow offers level premiums. This means your monthly cost is locked in for the duration of the term (e.g., 20 years). The price will not increase as you get older or if your health changes after the policy has started. This provides significant financial predictability for families on a budget.
Is Bestow Right for You?
Bestow is an ideal solution for a specific type of consumer. You should consider Bestow if:
- You are between 18 and 60 and in generally good health.
- You value speed and want to avoid the inconvenience of a medical exam.
- You only need Term Life insurance to cover a specific period (like the duration of a mortgage or until children graduate).
- You are comfortable managing your financial products through a digital portal rather than speaking with a local agent.
Conversely, if you have pre-existing conditions, need permanent "cash value" insurance, or require coverage amounts exceeding $2 million, you would be better served by a traditional brokerage that can shop your case to multiple carriers.
Frequently Asked Questions
Does "no medical exam" mean I don't have to provide my health history?No. You still have to answer detailed health questions and provide authorization for Bestow to access your medical and prescription records. The "no exam" part simply means you don't have to undergo a physical examination or provide blood and urine samples.
Can I be denied for a Bestow policy?Yes. If Bestow’s algorithm identifies high-risk factors in your data—such as a history of serious illness, a high BMI, or a poor driving record—you may be declined. If this happens, it does not mean you are uninsurable; it simply means you do not fit Bestow’s specific risk profile for accelerated underwriting.
Are Bestow’s rates higher than traditional life insurance?For many healthy individuals, Bestow’s rates are highly competitive and often identical to traditional policies. However, for those with minor health issues, a traditional insurer might offer a slightly lower rate because the medical exam provides the insurer with more "proof" of your health status, reducing their perceived risk.
What happens if I lie on the digital application?Lying on a life insurance application is considered material misrepresentation. Because Bestow verifies your answers against third-party databases (like the MIB), discrepancies are usually caught instantly. If a lie is discovered after the policy is issued, the insurer can void the policy or deny a death benefit claim during the two-year contestability period.
Does Bestow offer a money-back guarantee?Bestow typically provides a 30-day "free look" period. If you purchase a policy and change your mind within the first 30 days, you can cancel and receive a full refund of any premiums paid. This is a standard consumer protection in the insurance industry.
Can I convert my Bestow term policy to a whole life policy later?Usually, no. Most Bestow policies do not include a conversion privilege. If you think you might want permanent coverage in the future, you should look for a carrier that offers "convertible" term life insurance.
Final Recommendation
For the vast majority of healthy adults seeking life insurance in 2026, Bestow offers one of the most efficient paths to coverage. The combination of its user-friendly interface and the financial strength of North American Company for Life and Health Insurance creates a reliable safety net without the traditional headaches of the industry. If you need straightforward term coverage and have a clean health record, start with a quote from Bestow to see if you qualify for instant approval.
Disclaimer: Life insurance products and eligibility requirements can vary by state and individual circumstances. It is recommended to consult with a licensed financial advisor to ensure a policy meets your specific long-term needs.