Mutual of Omaha remains a top-tier provider for senior life insurance in 2026, offering exceptional financial stability and specialized products like the Living Promise Whole Life plan. It is ideal for seniors aged 45 to 85 seeking permanent coverage for final expenses without the requirement of a medical exam.
Mutual of Omaha has spent over a century establishing itself as a cornerstone of the American insurance industry. For seniors navigating the complexities of estate planning and end-of-life expenses in 2026, the company offers a blend of traditional reliability and modernized digital tools. Choosing a life insurance provider at an advanced age involves more than just comparing monthly premiums; it requires an evaluation of the company’s ability to pay claims decades into the future and the clarity of its policy terms.
As a mutual insurance company, Mutual of Omaha is owned by its policyholders rather than outside shareholders. This structure often aligns the company's long-term interests with those of its customers, potentially leading to more stable pricing and a focus on long-term solvency. In this review, we examine the specific products available to seniors, the nuances of their underwriting process, and how they compare to the broader 2026 insurance market.
Disclaimer: This review is for informational purposes only and does not constitute professional financial, legal, or medical advice. Insurance regulations and product availability may vary by state. Always consult with a licensed insurance professional before making a purchase.
Company Reputation and Financial Strength
When evaluating a senior life insurance provider, financial strength is the most critical metric. Seniors rely on these policies to provide liquidity for their beneficiaries at a time of emotional stress. Mutual of Omaha consistently receives high marks from independent rating agencies. As of 2026, it maintains an A+ (Superior) rating from A.M. Best and high ratings from S&P Global, reflecting a strong capacity to meet its ongoing insurance obligations.
The company’s reputation is further bolstered by its performance in customer satisfaction indices. According to reports from the National Association of Insurance Commissioners (NAIC), Mutual of Omaha typically maintains a lower-than-average complaint ratio for its life insurance products compared to other national carriers. This suggests that their claims process and customer service interactions are generally transparent and efficient, which is a vital consideration for beneficiaries who may be unfamiliar with the technicalities of filing a death claim.
Primary Senior Insurance Products: Living Promise Whole Life
The centerpiece of Mutual of Omaha’s senior portfolio is the Living Promise Whole Life Insurance plan. This product is designed specifically for final expenses, such as funeral costs, small debts, or remaining medical bills. It is a permanent policy, meaning it will not expire as long as premiums are paid, and it builds cash value over time.
Level Benefit Plan
The Level Benefit plan is intended for seniors in relatively good health. It provides coverage ranging from $2,000 to $50,000 (depending on the state and age of the applicant). The "level" designation means that the full face amount of the policy is available to beneficiaries from the very first day the policy is active.
Applicants for this plan must answer a series of health questions, but they are not required to undergo a physical medical examination. This "simplified issue" underwriting allows for a faster approval process—often within minutes or days—making it an attractive option for those who want immediate peace of mind.
Graded Benefit Plan
For seniors with more significant health challenges, Mutual of Omaha offers the Graded Benefit plan. This version is available to those who may not qualify for the level benefit due to certain chronic conditions. The coverage amounts are typically lower, often capped at $20,000.
The key feature of this plan is its payout structure: if the insured dies of natural causes within the first two years of the policy, the beneficiaries receive a return of all premiums paid plus 10% interest, rather than the full face amount. After the two-year "waiting period," the full death benefit becomes available. It is important to note that if death occurs due to an accident within the first two years, the full benefit is usually paid immediately.
Guaranteed Acceptance Whole Life Insurance
In 2026, many seniors find themselves in a position where health issues make traditional underwriting impossible. For these individuals, Mutual of Omaha provides a Guaranteed Acceptance policy. This product is available to applicants aged 45 to 85 (and up to age 75 in some jurisdictions) with absolutely no health questions and no medical exam.
While "guaranteed" sounds ideal, it comes with specific caveats that every consumer must understand. First, the premiums are significantly higher than simplified issue policies because the insurer is taking on a higher level of risk. Second, like the graded benefit plan, it features a two-year waiting period for non-accidental deaths. This policy should generally be viewed as a "last resort" for those who cannot qualify for any other form of coverage.
Term Life Express: An Alternative for Younger Seniors
Not every senior needs permanent coverage. Some may still have a mortgage that will be paid off in 10 or 15 years, or they may want to provide income replacement for a spouse until social security benefits stabilize. For these cases, Mutual of Omaha offers Term Life Express.
This product is available to seniors up to age 70 (for a 10-year term) or age 65 (for a 15-year or 20-year term). It offers much higher coverage amounts—up to $300,000—than the final expense plans. Like the Living Promise plan, it uses simplified underwriting, meaning no needles or physical exams are required. It also includes "living benefits" at no additional cost, which allow the policyholder to access a portion of the death benefit if they are diagnosed with a terminal, chronic, or critical illness.
2026 Comparison of Senior Life Insurance Options
The following table compares the primary features of Mutual of Omaha’s most popular senior products to help clarify which path is appropriate for different needs.
| Feature | Living Promise (Level) | Living Promise (Graded) | Guaranteed Acceptance | Term Life Express |
|---|---|---|---|---|
| Issue Ages | 45–85 | 45–80 | 45–85 | 18–70 |
| Max Coverage | $50,000 | $20,000 | $25,000 | $300,000 |
| Medical Exam | No | No | No | No |
| Health Questions | Yes | Yes | No | Yes |
| Waiting Period | None | 2 Years | 2 Years | None |
| Cash Value | Yes | Yes | Yes | No |
| Primary Use | Final Expenses | Final Expenses | Final Expenses | Debt/Income |
Underwriting and Eligibility Nuances
Understanding the underwriting process is where many seniors struggle. Mutual of Omaha uses a "knockout" question system for their simplified issue products. If you answer "yes" to certain high-risk questions—such as current hospitalization, terminal illness diagnosis, or a recent history of certain cancers—you will automatically be disqualified from the Level Benefit plan.
However, Mutual of Omaha is known in the industry for being relatively "liberal" with certain common senior health issues. For example, they are often more competitive for individuals with well-controlled Type 2 diabetes or those taking specific blood pressure medications compared to some stricter carriers. In 2026, they continue to refine their data-driven underwriting, which sometimes allows them to offer better rates to seniors who maintain healthy lifestyle habits despite age-related conditions.
The Cost of Coverage in 2026
Life insurance premiums are determined by age, gender, tobacco use, and health status. In 2026, inflationary trends have caused a slight uptick in premiums across the industry, but Mutual of Omaha remains competitively priced within the "Final Expense" niche.
For a 65-year-old non-smoking male in relatively good health, a $10,000 Living Promise Level Benefit policy might cost between $45 and $60 per month. A female of the same age might pay between $35 and $45. It is essential to remember that once a whole life policy is issued, the premiums are locked in for life. They will never increase, regardless of changes in your health or the economy. This predictability is a significant advantage for seniors living on a fixed income.
Advantages and Disadvantages
Pros
- No Medical Exams: All primary senior products avoid the need for blood draws or physicals.
- Financial Stability: A+ rating ensures that the company will likely be around to pay the claim.
- Quick Approval: The simplified underwriting process often results in a decision within 24 to 48 hours.
- Living Benefits: Many policies include riders that allow access to funds during a terminal illness.
- Mutual Structure: Policyholder interests are prioritized over shareholder profits.
Cons
- Coverage Caps: $50,000 is often the limit for whole life, which may not be enough for those with significant debts.
- Two-Year Waiting Periods: Common on the graded and guaranteed acceptance plans, which can be a risk for those in very poor health.
- Pricing for Tobacco Users: Mutual of Omaha can be significantly more expensive for seniors who smoke or use nicotine products.
- Strict "Look-Back" Periods: Their health questions often look back 2 to 5 years for major events like heart surgery or cancer, which can push applicants into more expensive graded plans.
How Mutual of Omaha Compares to Competitors
In the 2026 market, Mutual of Omaha’s primary competitors in the senior space include AARP (underwritten by New York Life), Globe Life, and Colonial Penn.
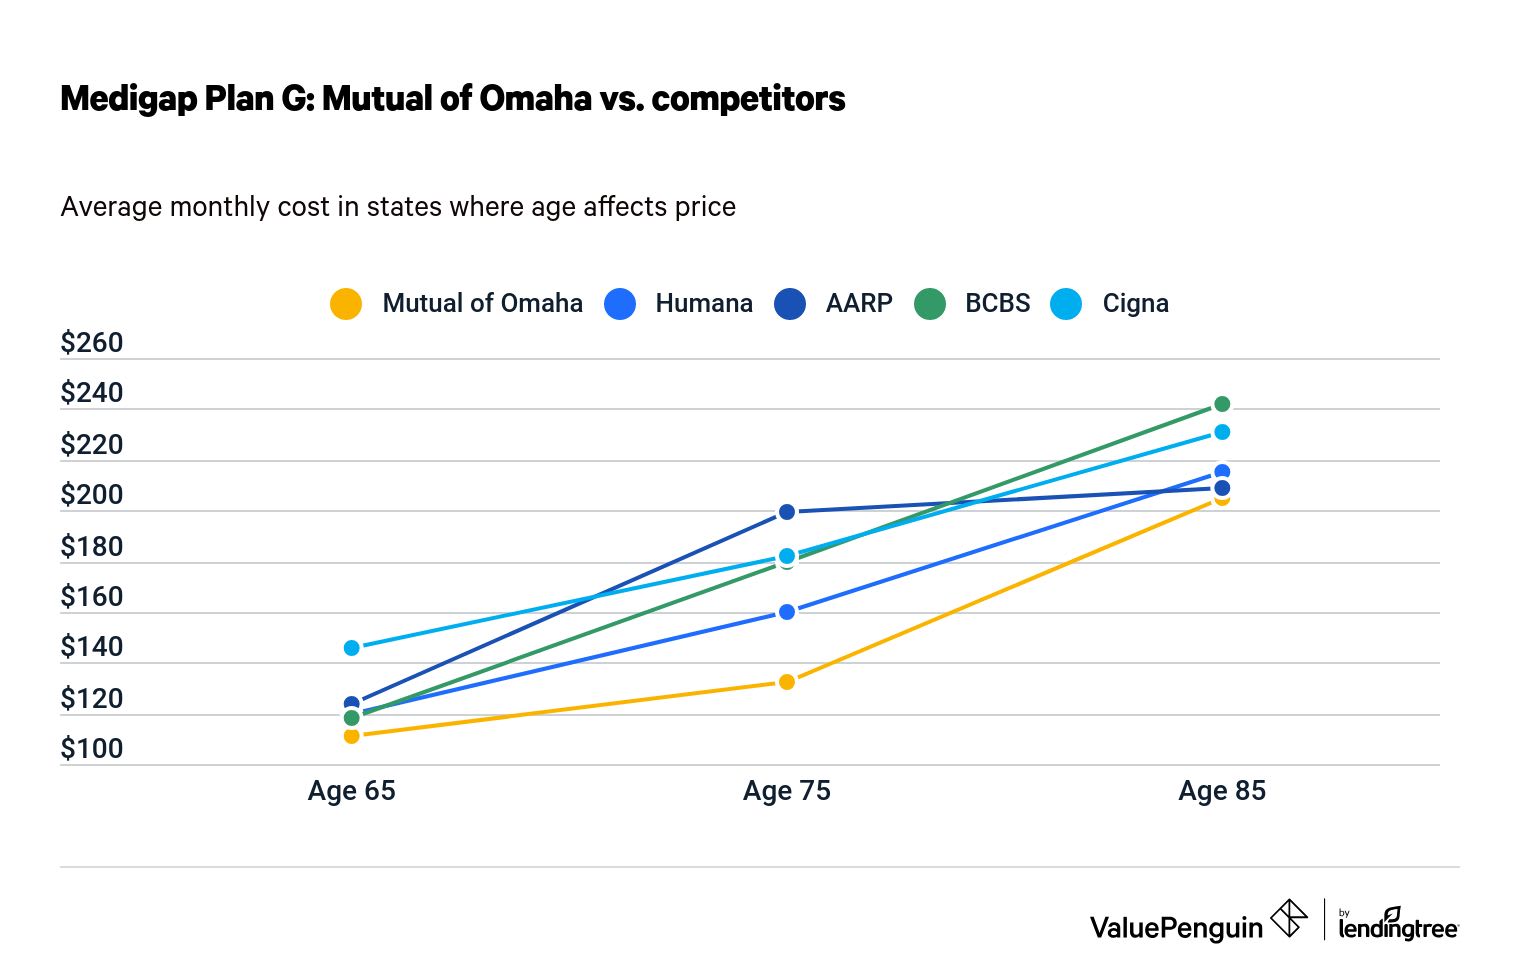
Compared to AARP/New York Life, Mutual of Omaha often offers more competitive rates for those who can pass the health questions. AARP’s term products are famous for having "price jumps" every five years, whereas Mutual of Omaha’s whole life products maintain a flat rate.
Compared to Colonial Penn and Globe Life, Mutual of Omaha’s Living Promise often provides better value. Colonial Penn is known for its "unit" pricing, which can be confusing and often results in a lower death benefit for the dollar spent once a senior reaches age 70. Globe Life offers "no money down" starts, but their long-term premium structure can be more expensive than Mutual of Omaha's simplified issue whole life over the duration of the policy.
Frequently Asked Questions
Does Mutual of Omaha require a physical for seniors?
No, Mutual of Omaha does not require a medical exam or physical for its primary senior life insurance products, including Living Promise and Guaranteed Acceptance. Underwriting is based on health questions, a review of prescription history (via the Medical Information Bureau), and sometimes a brief telephone interview. This makes the application process much less invasive for older adults.
What happens if I stop paying my premiums?
Since Living Promise and Guaranteed Acceptance are whole life policies, they build cash value. If you stop paying premiums, you may have the option to use the accumulated cash value to keep the policy in force for a shorter period, or you may receive a reduced "paid-up" policy with a lower death benefit. If the policy has no cash value (common in the first few years), it will simply lapse, and coverage will end.
Can I change my beneficiaries after the policy is active?
Yes, you can change your beneficiaries at any time by submitting a request to Mutual of Omaha. This is a common practice for seniors whose family situations change due to marriage, divorce, or the passing of a previously named beneficiary. It is recommended to review your beneficiary designations every few years to ensure they align with your current wishes.
Is the death benefit taxable for my children?
In most cases, the death benefit from a life insurance policy is paid to beneficiaries tax-free. Under current 2026 federal tax laws, life insurance proceeds are not considered taxable income. However, if the death benefit becomes part of a very large estate, it could potentially be subject to estate taxes, though this usually only applies to estates valued in the millions.
How long does it take for Mutual of Omaha to pay a claim?
Mutual of Omaha is generally known for a prompt claims process. Once the beneficiary submits the required documentation—typically a completed claim form and a certified copy of the death certificate—claims are often processed and paid within 7 to 14 business days. Delays only typically occur if the death happens within the "contestability period" (usually the first two years), requiring a more thorough investigation.
Practical Recommendations for Seniors
If you are considering Mutual of Omaha in 2026, your first step should be to determine exactly how much coverage you need. For most, a $10,000 to $20,000 policy is sufficient to cover modern funeral costs and minor administrative expenses.
If you are in relatively good health (no major surgeries or life-threatening diagnoses in the last two years), always apply for the Living Promise Level Benefit first. Do not assume you need "Guaranteed Acceptance" just because you are older or have minor ailments like high blood pressure. Applying for the level benefit first could save you thousands of dollars in premiums over the life of the policy and ensure your beneficiaries are protected from day one without a waiting period.
Finally, work with an independent agent who represents multiple carriers. While Mutual of Omaha is an excellent choice, an independent agent can compare their 2026 rates against other high-quality insurers to ensure you are getting the most death benefit possible for your monthly budget.