A 401k plan for contractors, primarily known as a Solo 401k, allows independent business owners to save for retirement as both employer and employee. This dual-role structure offers significantly higher contribution limits than standard IRAs, providing substantial tax-deductible benefits while accommodating the unique income fluctuations of the contracting and freelance markets.
Understanding the Strategic Value of a Contractor 401k
For independent contractors and 1099 professionals in 2026, the Solo 401k (also referred to as an Individual 401k or One-participant 401k) remains the most powerful retirement vehicle available. Unlike traditional employer-sponsored plans, which are designed for large groups of employees, the contractor 401k is tailored to the "business of one." It recognizes that a contractor is simultaneously the owner of the entity and its sole worker, allowing for a "double-dip" into contribution buckets.
The strategic overview of this plan hinges on its ability to minimize current taxable income while maximizing long-term wealth accumulation. Because contractors often face high self-employment taxes (Social Security and Medicare), the ability to defer a significant portion of their gross income into a tax-advantaged account is not just a retirement strategy; it is a critical tax-planning tool.
In the current 2026 fiscal environment, the Solo 401k has been further enhanced by provisions within the SECURE Act 2.0, which have matured to provide greater flexibility in how contributions are characterized and how older contractors can "catch up" on their savings. Navigating these rules requires a deep understanding of eligibility, contribution mechanics, and the administrative responsibilities that come with being a plan administrator.
Eligibility and the "No-Employee" Rule
The most significant prerequisite for a 401k contractors plan is the absence of full-time employees. The Internal Revenue Service (IRS) defines a "one-participant plan" as a business that covers only the owner and, if applicable, the owner’s spouse.
The Definition of an Employee
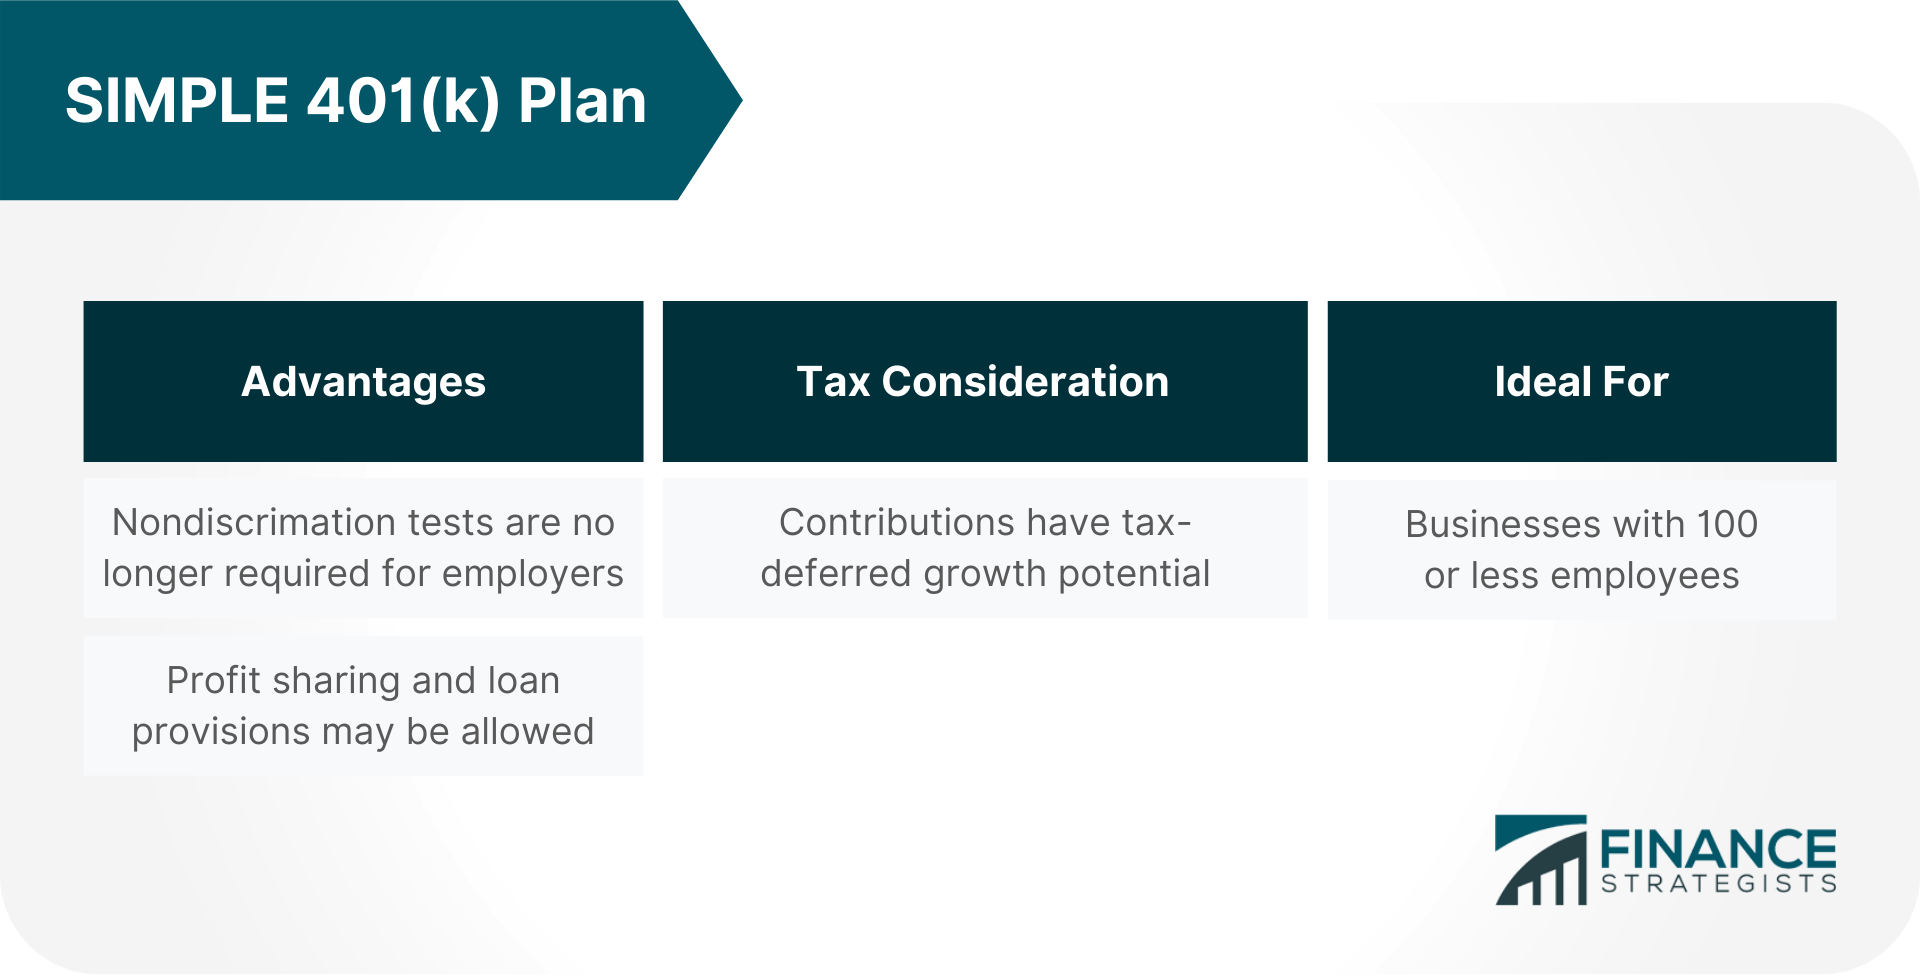
To qualify for a Solo 401k, you cannot have any employees who work more than 1,000 hours per year. This is a critical distinction for contractors who may scale their operations. If you hire a full-time assistant or a team of workers who meet the 1,000-hour threshold, you are no longer eligible for a Solo 401k and must transition to a standard 401k, which carries significantly higher administrative costs and more stringent compliance testing (such as non-discrimination testing).
The Spouse Exception
A unique strategic advantage of the contractor 401k is the spouse exception. If your spouse performs legitimate work for your contracting business and receives a salary, they can be included in the plan. This effectively doubles the household contribution limit, as both individuals can contribute as employees and the business can contribute for both as the employer. This is often the most effective way for high-earning contracting households to shield income from taxation.
Independent Contractors and Freelancers
Whether you operate as a sole proprietorship, a single-member LLC, or an S-Corp, you are eligible for this plan as long as your income is derived from self-employment. The structure of your business entity will, however, change how you calculate your maximum allowable contributions.
Contribution Mechanics: The Dual Role Advantage
The primary reason contractors choose a 401k over a SEP IRA or a Simple IRA is the high contribution ceiling. Because you act as both the employer and the employee, you can contribute in two distinct ways.
1. The Employee Elective Deferral
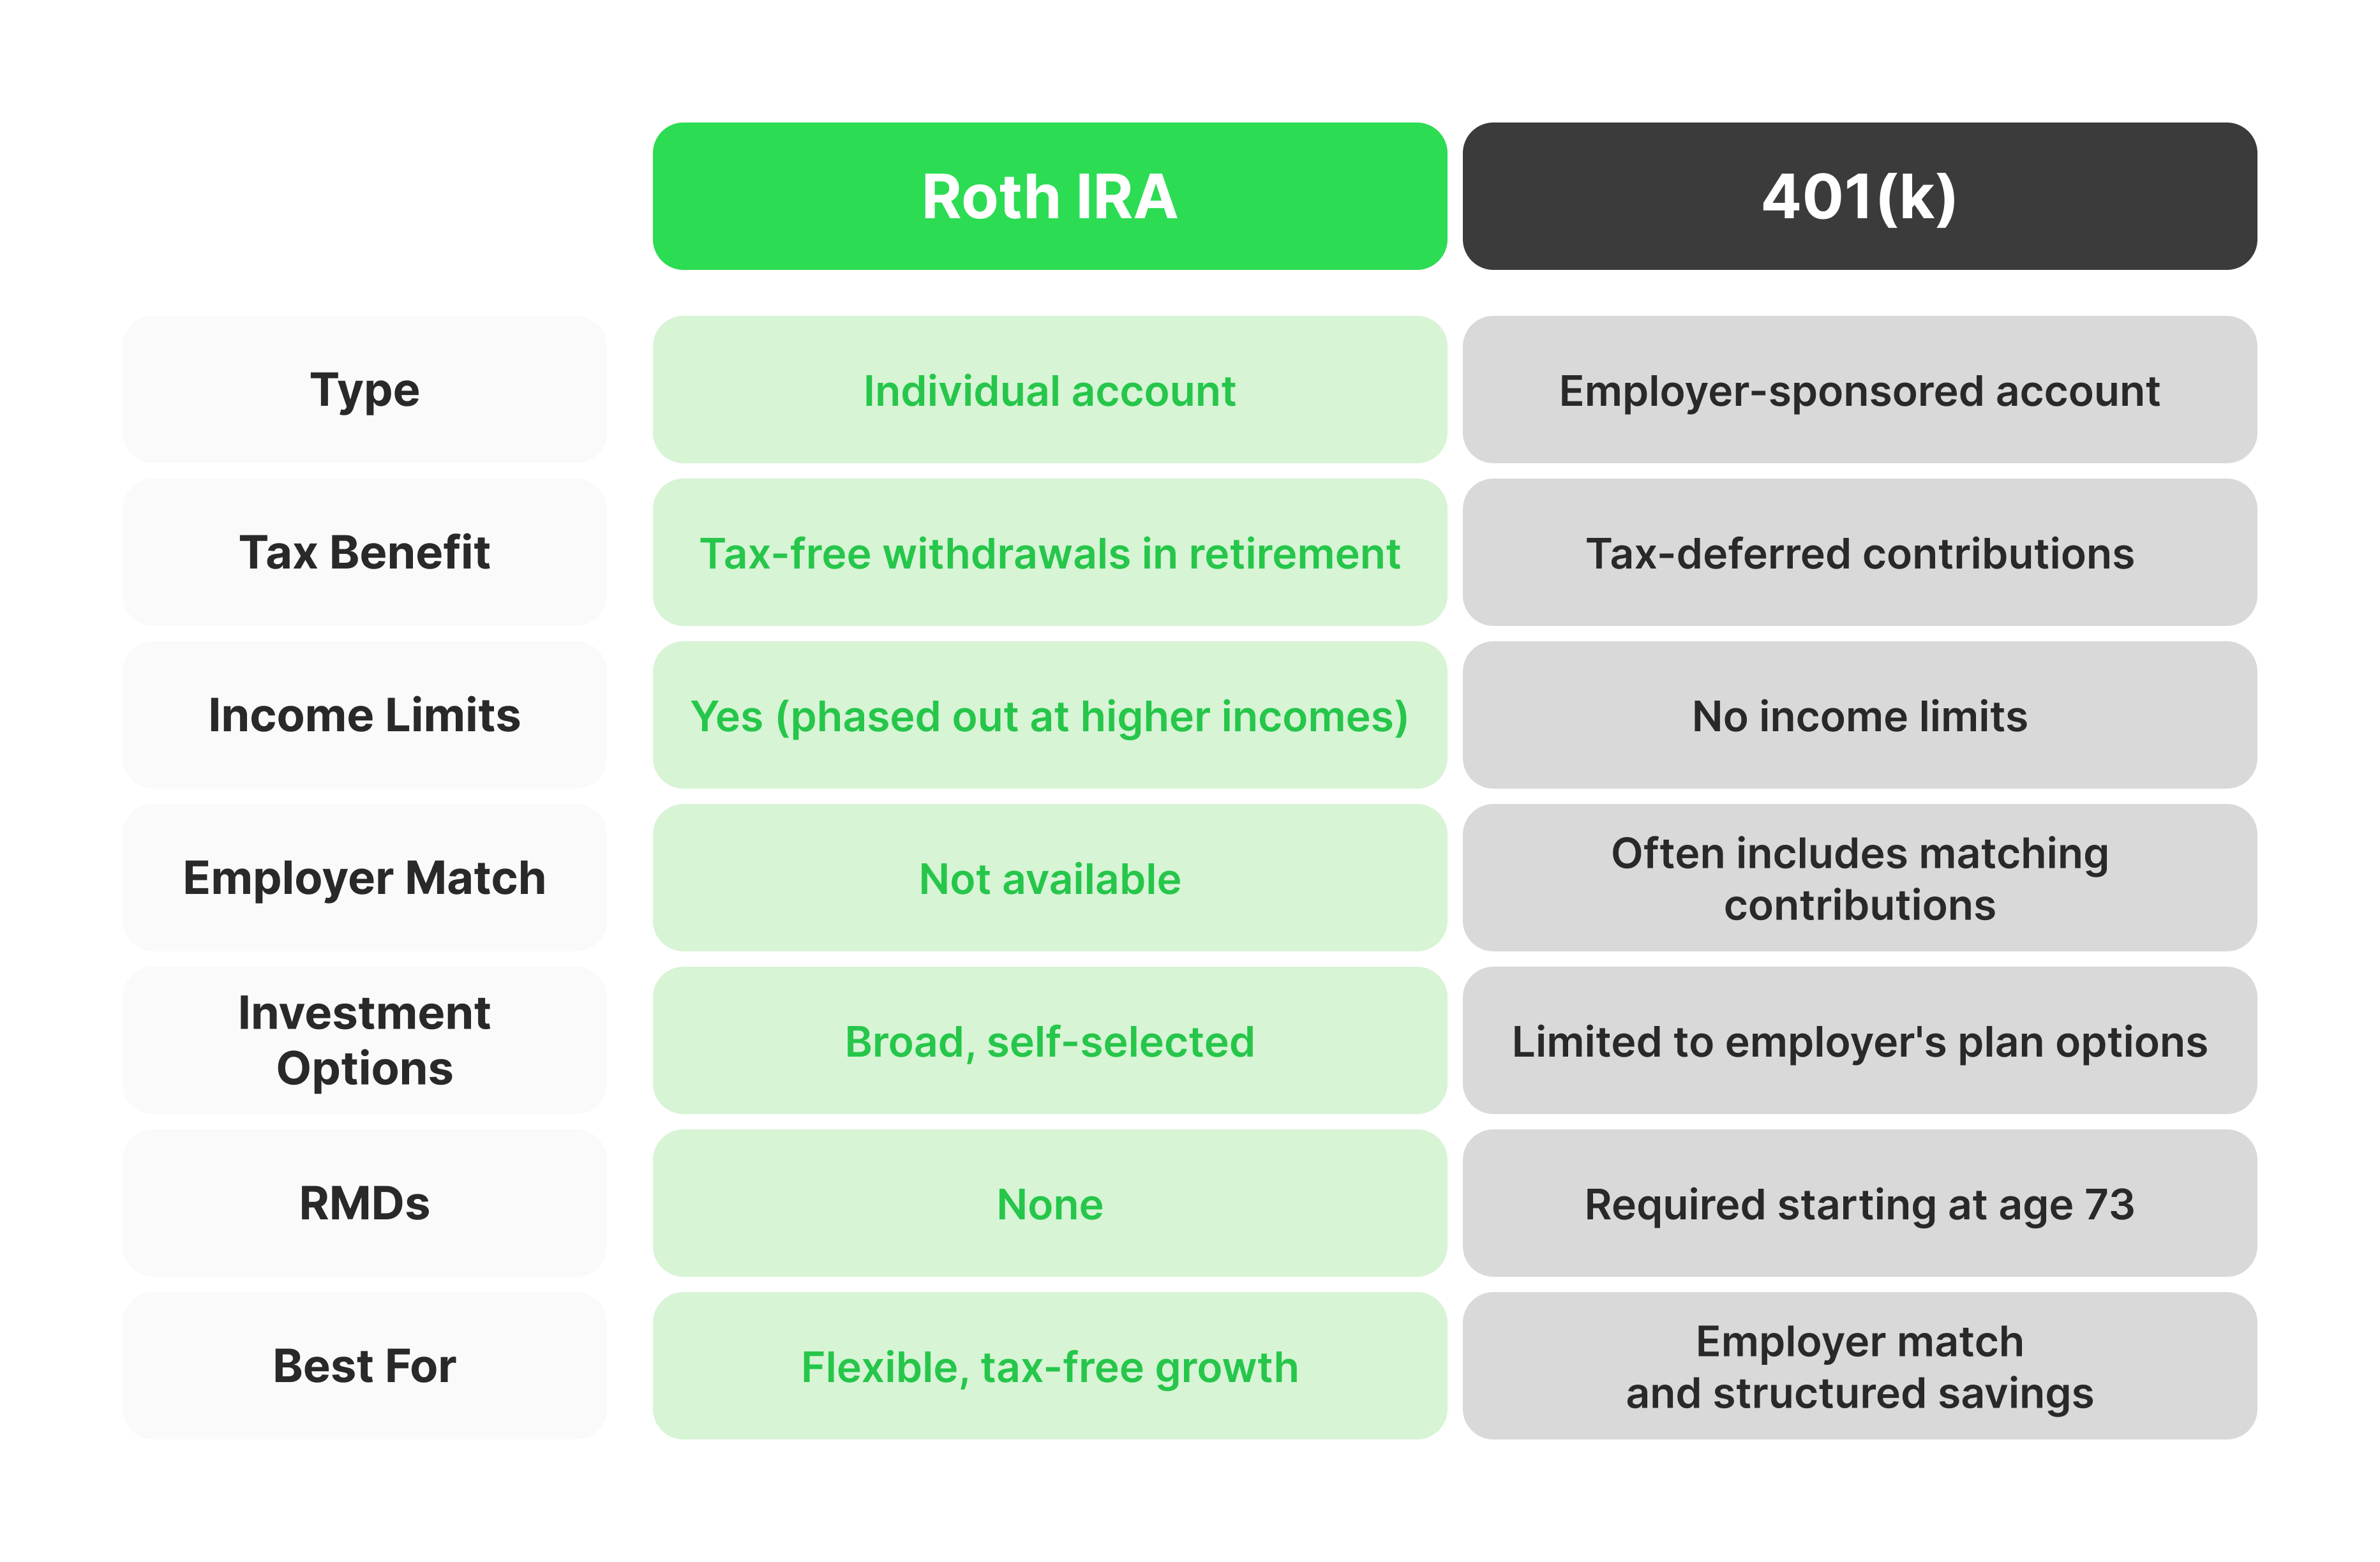
As the "employee," you can contribute up to 100% of your earned income, up to the annual limit. For 2026, this limit is indexed to inflation (building on the 2024 limit of $23,000). These contributions can be made on a "Traditional" basis (reducing your taxable income today) or a "Roth" basis (contributing after-tax dollars for tax-free withdrawals in retirement).
2. The Employer Profit-Sharing Contribution
As the "employer," your business can contribute an additional percentage of your net self-employment income. For most contractors, this is generally capped at 25% of your compensation (defined as net earnings from self-employment minus half of your self-employment tax and your own elective deferrals).
Total Combined Limits
The total contribution across both roles is capped annually. In 2026, for those under age 50, the combined limit generally exceeds $70,000, depending on the specific inflation adjustments finalized by the IRS for the current year. This is significantly higher than the $7,000 limit found in traditional or Roth IRAs, making it a superior choice for those looking to build a large nest egg rapidly.
Strategic Enhancements from SECURE Act 2.0 (2026 Context)
By 2026, the various phases of the SECURE Act 2.0 have become standard operating procedure for retirement plans. Several key provisions specifically benefit contractors:
- Enhanced Catch-Up Contributions: For contractors aged 60 to 63, a special higher catch-up limit is now in effect. This allows those in their peak earning years to aggressively front-load their retirement accounts before transitioning out of the workforce.
- Roth Employer Contributions: Historically, employer "matching" or profit-sharing contributions had to be pre-tax (Traditional). In 2026, contractors have the option to designate these employer-side contributions as Roth, provided they are willing to pay the income tax on those amounts in the year they are made.
- Emergency Savings Accounts: Some Solo 401k plan documents now allow for a "linked" emergency savings account, providing contractors with a source of liquidity without the penalties typically associated with early 401k withdrawals.
- Automated Portability: For those moving from a corporate career into full-time contracting, the rules for rolling over existing 401k balances into a new Solo 401k have been streamlined to prevent "leakage" and maintain tax-deferred status.
Comparative Analysis: Solo 401k vs. Alternatives
When developing a strategic plan, it is essential to compare the 401k against other self-employed retirement options like the SEP IRA or the SIMPLE IRA.
| Feature | Solo 401k (Contractor) | SEP IRA | SIMPLE IRA |
|---|---|---|---|
| Max Contribution (Under 50) | ~$70,000+ (Combined) | 25% of net income | $16,000 + Employer Match |
| Roth Option | Yes (Employee & Employer) | Yes (Recently added) | Yes (Recently added) |
| Participant Loans | Yes (Up to $50,000) | No | No |
| Catch-up (50+) | Yes | No | Yes |
| Complexity | Moderate (Form 5500-EZ) | Low | Low |
| Spouse Eligibility | Yes | Yes | Yes |
While the SEP IRA is simpler to set up, it often requires a much higher total income to reach the same contribution levels as a Solo 401k. For example, to contribute $25,000 to a SEP IRA, a contractor might need $100,000 in net income. With a Solo 401k, that same $25,000 could be contributed with just $25,000 of earned income through the employee deferral portion.
Administrative Requirements and Compliance
While the benefits are vast, a 401k contractors plan is an "IRS-qualified" plan, meaning it must follow specific federal regulations to maintain its tax-exempt status.
The $250,000 Threshold and Form 5500-EZ
The most critical administrative task for a Solo 401k owner occurs once the plan's total assets exceed $250,000. At this point, the IRS requires the filing of Form 5500-EZ (Annual Return of a One-Participant Retirement Plan). This form is an informational return that discloses the plan’s value and activity. Failing to file this form can result in significant penalties, sometimes reaching thousands of dollars, even if no tax is actually owed.
Plan Documents and EINs
To establish a 401k, a contractor cannot use their Social Security Number as the primary identifier for the plan. You must obtain an Employer Identification Number (EIN) specifically for the retirement plan (separate from your personal business EIN if preferred, though usually, the business EIN is used to sponsor the plan). Furthermore, you must adopt a written "Plan Document" that has been pre-approved by the IRS. Most major brokerage firms provide these documents for free or a low fee when you open the account.
Prohibited Transactions and Self-Direction
Many contractors use a "Self-Directed" Solo 401k to invest in alternative assets like real estate, private equity, or precious metals. While this offers immense flexibility, it also introduces the risk of "prohibited transactions." You cannot, for example, use 401k funds to buy a vacation home that you personally stay in, nor can you pay yourself a management fee for overseeing the plan’s investments. These actions can disqualify the entire plan, leading to the immediate taxation of all assets.
Strategic Implementation: A Step-by-Step Guide
If you are a contractor looking to establish or optimize your 401k in 2026, follow these steps to ensure compliance and maximum benefit:
- Verify Eligibility: Ensure you have no employees (excluding a spouse) and that your income is generated from self-employment (1099, LLC, S-Corp).
- Select a Provider: Choose between a "Prototype" plan from a large brokerage (Fidelity, Schwab, Vanguard) or a "Custom" plan from a specialized provider. Prototype plans are cheaper (often free) but usually limit investments to stocks, bonds, and mutual funds. Custom plans allow for self-direction into real estate but involve higher setup fees.
- Obtain an EIN: If you don't already have one for your business, apply for an EIN via the IRS website. This is required for the 401k trust.
- Adopt the Plan Document: Sign the adoption agreement provided by your broker. This document outlines the rules of your plan, including contribution limits and whether you allow loans.
- Open the Trust Account: The 401k assets must be held in a separate trust account. The account title should reflect the name of the plan (e.g., "The [Your Name] 401k Trust").
- Calculate and Deposit Contributions: Work with a CPA to determine your maximum elective deferral and profit-sharing amounts. Deposits for the employee portion should generally be made by the end of the calendar year, while employer portions can often be made up until your tax filing deadline (including extensions).
Potential Pitfalls and Troubleshooting
Despite its advantages, there are common mistakes that can derail a contractor’s retirement strategy:
- The "Hired Help" Trap: Many contractors forget that hiring a part-time worker who eventually crosses the 1,000-hour mark triggers the end of Solo 401k eligibility. If you plan to grow a team, start looking at "Safe Harbor 401k" plans early.
- Inaccurate Income Calculations: For sole proprietors, your "compensation" is not your gross revenue. It is your net profit minus the deductible half of self-employment tax. Over-contributing based on gross revenue is a common error that requires a "Corrective Distribution" to fix.
- Missing the Filing Deadline: As mentioned, the Form 5500-EZ is mandatory once the plan hits $250,000 in assets. Many contractors miss this because they believe that since they have no employees, they have no paperwork.
- Loan Compliance: If your plan allows for a loan (up to 50% of the balance or $50,000, whichever is less), you must create a formal loan agreement and make regular amortized payments. Treating a 401k loan like a casual withdrawal is a major compliance risk.
Frequently Asked Questions
Can I have a Solo 401k if I also have a day job with a 401k?
Yes, you can have both. However, the Employee Elective Deferral limit applies across all plans. If you contribute $15,000 to your employer's 401k at your W-2 job, you can only contribute the remaining balance of the annual limit (e.g., $8,000 if the limit is $23,000) to your Solo 401k as an employee. However, the Employer Profit Sharing limit for your contracting business is independent of your W-2 job.
When is the deadline to set up a 401k for contractors?
Under SECURE Act provisions active in 2026, you can actually set up and fund a Solo 401k for a given tax year up until your tax filing deadline (including extensions). This is a significant change from older rules that required the plan document to be signed by December 31st. This allows contractors to see their final year-end income before deciding whether a 401k is the right move.
Can I roll over my IRA into a Solo 401k?
Yes, most Solo 401k plans allow for "roll-ins." You can roll over funds from a Traditional IRA, SEP IRA, or a previous employer's 401k. However, you generally cannot roll a Roth IRA into a Solo 401k, though you can roll a Roth 401k into a Solo 401k.
What happens if I close my contracting business?
If you cease operations, you must terminate the 401k plan. The assets are then typically rolled over into an Individual Retirement Account (IRA) or another qualified 401k plan if you return to W-2 employment. You must file a final Form 5500-EZ to notify the IRS that the plan has been liquidated and closed.
Are there any fees associated with a contractor 401k?
Fees vary by provider. Many major online brokerages offer Solo 401k plans with $0 setup fees and $0 maintenance fees. However, if you require a "Self-Directed" plan to buy real estate, you may pay an initial setup fee of $500–$2,000 and annual maintenance fees of $300–$500 to a specialized custodian.
Final Recommendation
For any contractor earning a significant net profit, the Solo 401k is the gold standard for retirement planning. It offers the highest contribution limits, the most flexible tax treatments (Roth vs. Traditional), and the ability to borrow against your own savings through participant loans.
As you move through 2026, the primary strategic action is to consult with a tax professional to calculate your exact "earned income" figures. Because these calculations are nuanced for the self-employed, an accurate assessment ensures you maximize your contributions without triggering over-contribution penalties. If your plan balance is approaching the $250,000 mark, prioritize the establishment of a filing system for Form 5500-EZ to avoid unnecessary IRS scrutiny.