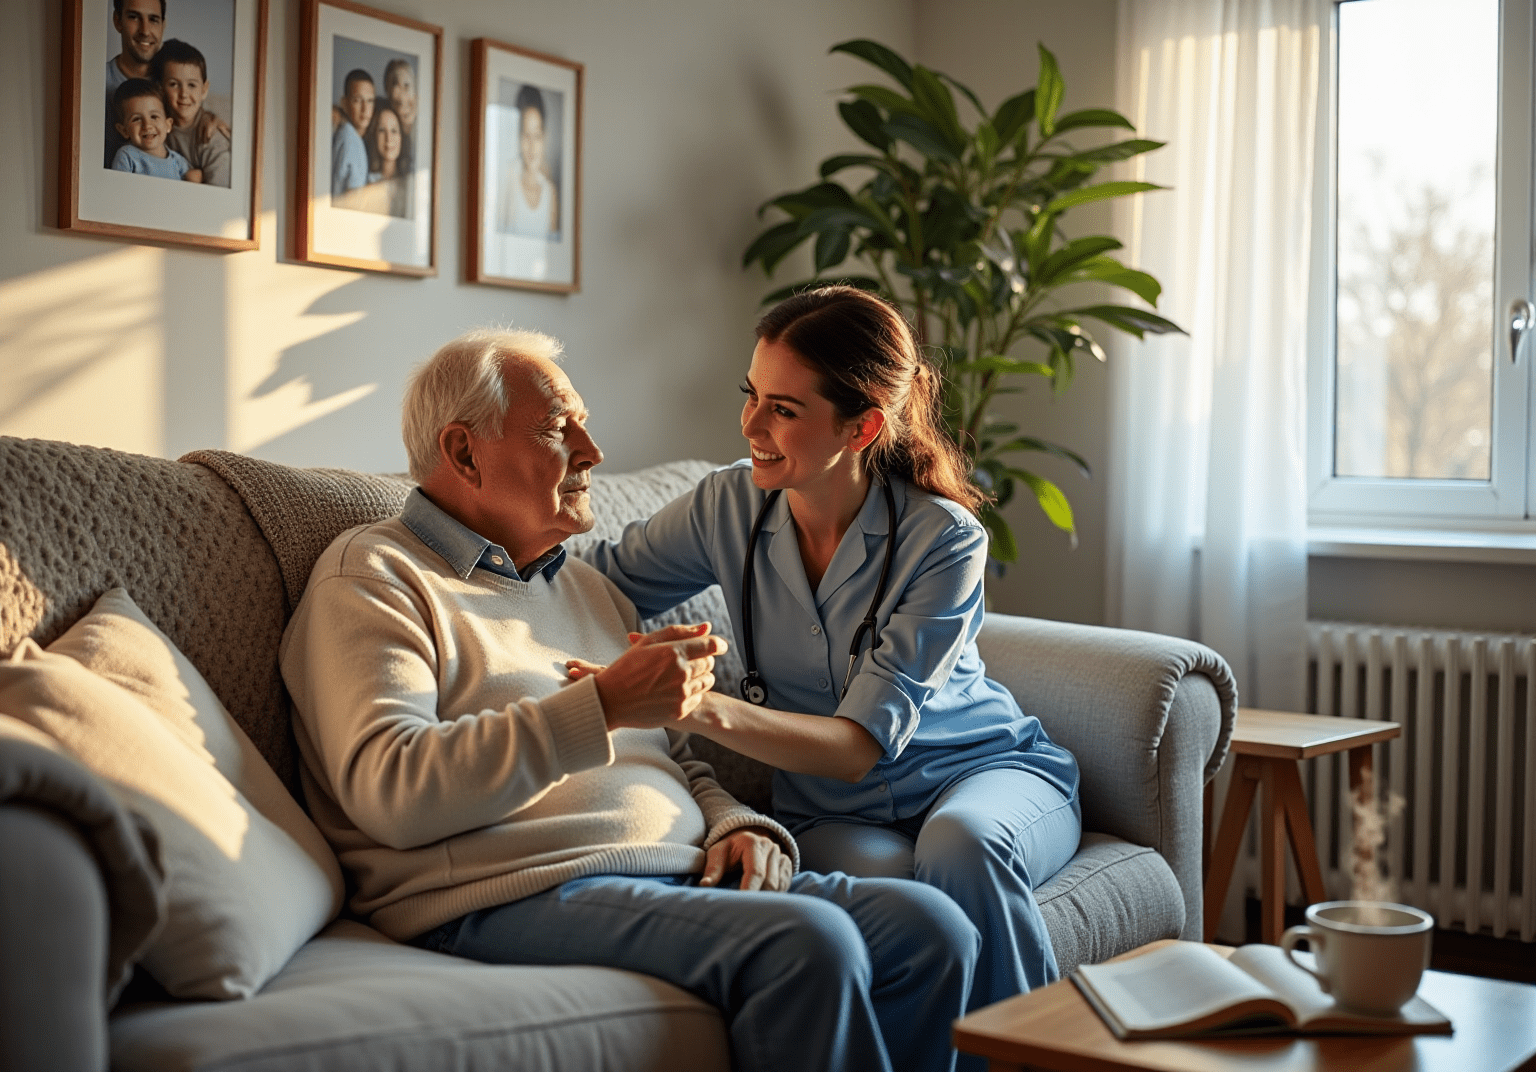
Understanding "Moms Care" as a concept or service entity involves recognizing the critical intersection of professional caregiving, familial support systems, and the logistics of home health assistance. In the context of 2026, this term frequently refers to specialized in-home care programs designed to assist aging parents, particularly mothers, in maintaining their independence, health, and quality of life within the familiar surroundings of their own homes.
Defining the Scope of In-Home Care for Mothers
The primary mission of "Moms Care" initiatives is to bridge the gap between complete independence and institutionalized care. For many families, the transition to assisted living or nursing homes is often perceived as a last resort, reserved for when medical needs exceed the capacity of home-based support. Understanding the mechanics of these services allows families to make informed decisions about long-term care plans.
In-home care is not a monolithic service; it spans a broad spectrum ranging from non-medical companionship to skilled nursing care. When families look into care services, they are often navigating a complex environment of agency-provided support, government-funded programs, and independent contractor arrangements.
Key Components of Professional Caregiving
To effectively utilize care services, one must categorize the level of assistance required. These categories are generally divided into three distinct buckets:
- Companionship and Homemaking: This entry-level support focuses on social engagement, light housekeeping, meal preparation, and transportation. It is designed for mothers who are cognitively and physically capable of most tasks but require assistance with the secondary burdens of home maintenance or who suffer from loneliness.
- Activities of Daily Living (ADL) Support: As physical mobility or cognitive clarity declines, care must shift toward hands-on assistance. This includes help with bathing, dressing, grooming, toileting, and medication reminders. Professional caregivers undergo specific training to manage these tasks with dignity and safety.
- Skilled Nursing and Specialized Care: This level involves licensed medical professionals, such as Registered Nurses (RNs) or Licensed Practical Nurses (LPNs), who manage clinical tasks like wound care, intravenous therapy, and monitoring of chronic health conditions like diabetes or post-operative recovery.
Eligibility and Prerequisites for Service Access
Before securing care services, families must conduct an honest assessment of the mother’s health status. Most reputable home care agencies will perform a clinical assessment as a prerequisite to service. This process typically involves a review of:
- Medical History: A complete profile of chronic conditions, past surgeries, and ongoing treatments.
- Cognitive Evaluation: Assessment of memory, orientation, and potential presence of dementia or Alzheimer’s disease.
- Environmental Safety: An evaluation of the home layout to identify fall hazards, such as rugs, narrow hallways, or poorly lit areas.
- Current Medication Regimen: Documentation of all prescriptions to ensure that caregivers can manage adherence protocols.
It is vital to distinguish between what insurance may cover and what families must pay out-of-pocket. While some long-term care insurance policies and specific Medicaid waivers cover certain aspects of home care, standard Medicare often excludes long-term, non-medical in-home care, focusing instead on short-term rehabilitative support.
The Financial Landscape of Home Care in 2026
As of 2026, the cost of home care is highly variable depending on geographic location and the intensity of the care required. Understanding the financial structure is essential for long-term sustainability.
| Care Type | Primary Focus | Typical Cost Structure |
|---|---|---|
| Companion Care | Social and light support | Hourly or flat daily rate |
| Personal Care (ADLs) | Hygiene and mobility assistance | Higher hourly rate due to skill requirements |
| Skilled Nursing | Medical monitoring and treatment | Variable based on clinical licensure requirements |
| Respite Care | Temporary relief for family caregivers | Short-term contract or per-shift pricing |
Families should approach these costs by creating a budget that accounts for a 3-5% annual inflationary increase, which is common in the care industry due to rising wages for certified nursing assistants and health aides.
Identifying Quality Care Providers
Choosing a provider is the most critical decision in the "Moms Care" process. Not all agencies are created equal, and the vetting process should be rigorous.
- Licensing and Bonding: Ensure the agency is licensed by the state health department. Being bonded and insured is non-negotiable, as it protects the family from liability should an accident occur within the home.
- Employee Background Checks: Reputable agencies perform comprehensive background checks, including criminal history and verification of nursing or aide certifications.
- Caregiver-to-Client Matching: The best outcomes occur when the caregiver's personality and skills align with the mother’s preferences. Inquire about the agency's process for changing caregivers if the match is not successful.
- Communication Protocols: Establish clear expectations for reporting. You should receive regular updates on the mother’s mood, physical condition, and any changes in her daily routine.
Common Challenges and Troubleshooting
Even with professional support, challenges arise. The most frequent issue is the "refusal of care" by the individual receiving it. Many mothers are fiercely independent and may view the presence of a caregiver as an intrusion.
Addressing Resistance to Care: If your mother resists the idea of professional help, focus the conversation on safety and longevity rather than "help." Frame the caregiver as a "personal assistant" or "home manager" to mitigate the stigma associated with needing care. Gradually introduce services—perhaps starting with two or three hours a week—to normalize the presence of a professional in the home before moving to full-time care.
Managing Caregiver Burnout: If you are the primary family caregiver, you are at risk of burnout. Integrating professional care isn't just for the mother; it is a vital strategy for the child to maintain their own professional and personal life. Use respite care services to take regular, scheduled breaks to ensure that your role as a family member remains focused on love and connection, not just medical management.
Legal and Medical Considerations
In 2026, the legal framework for in-home care remains strict. Ensure that you have updated Power of Attorney (POA) documents—both medical and financial—before the need for care becomes urgent. Without these legal instruments, you may find it difficult to make decisions on your mother’s behalf or manage the financial aspects of her care contracts.
Furthermore, maintain a "Care Journal." This is a physical or digital document that logs medication administration, observed symptoms, and interactions with healthcare providers. This tool is invaluable when communicating with the mother's primary care physician, as it provides objective data rather than relying on subjective memory.
Frequently Asked Questions
1. Does Medicare cover long-term in-home care? Generally, no. Medicare covers skilled nursing care only if it is part of a plan of treatment following a hospital stay or for specific medical needs. Routine daily living assistance is usually not covered by traditional Medicare, though some Medicare Advantage plans offer supplemental benefits that may include limited home help.
2. How do I know when it is time to move from companionship to personal care? The transition is usually indicated by "ADL failures," such as difficulty bathing independently, managing incontinence, or trouble getting in and out of a chair or bed. If your mother is consistently struggling with these tasks, the risk of falls or infection increases significantly, and professional intervention is recommended.
3. What is the difference between a home care agency and an independent contractor? An agency employs, trains, and insures its workers, handling taxes and scheduling. An independent contractor is cheaper but requires the family to act as the employer, meaning you are responsible for taxes, background checks, and finding a replacement if the caregiver is ill.
4. Can my mother's insurance policy cover home care? If she holds a long-term care (LTC) insurance policy, it may cover home care. These policies vary significantly in their "triggers" for benefits. You must contact the insurance company to read the specific "activities of daily living" clauses in her policy to determine if she qualifies.
5. How can I ensure the caregiver is safe? Beyond standard background checks, install modern home-monitoring systems. In 2026, non-intrusive smart home technology, such as motion sensors or camera systems (with the mother’s consent and knowledge), can provide peace of mind regarding the mother’s safety during hours when family members are away.
Final Recommendation
The successful integration of "Moms Care" relies on early planning and open communication. Start by identifying the specific, non-negotiable health and safety needs of your mother, then conduct a thorough financial assessment to determine the level of professional support your budget can sustain. Begin with a trial period of light assistance to allow for a gradual transition, and always maintain updated legal documentation to avoid administrative roadblocks during times of crisis. Prioritize finding an agency that values clear, proactive communication, as your peace of mind is directly linked to the quality of information you receive about your mother’s daily status.