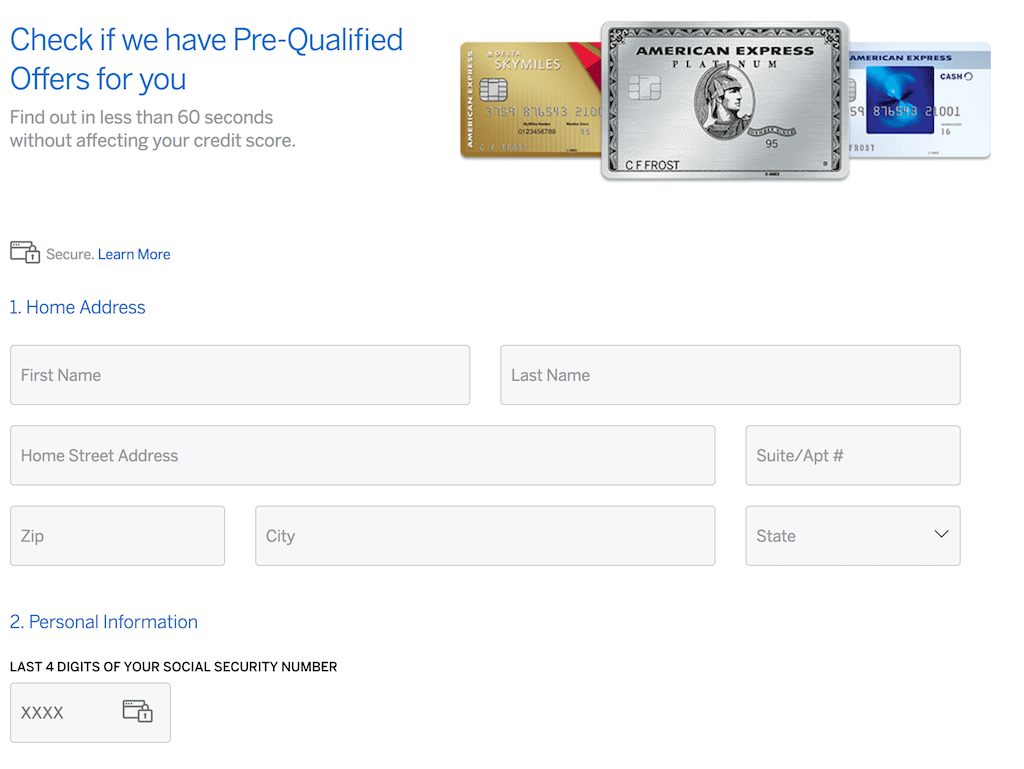
American Express pre-approval allows prospective cardholders to check if they are likely to be approved for a specific credit card before submitting a formal application, utilizing a soft credit check that does not impact their credit score. This mechanism gives applicants insight into their eligibility and potential offers, helping them target rewards cards, cash-back products, or travel cards that align with their financial profile without risking an unnecessary hard inquiry on their credit report.
Understanding the American Express Pre-Approval Process
Navigating the landscape of premium credit cards often requires a strategic approach to safeguard your credit profile. Financial institutions use various methods to gauge creditworthiness, and American Express is no exception. Understanding how pre-approval functions within the broader consumer credit ecosystem helps applicants minimize risks, optimize reward earnings, and maximize their chances of securing favorable terms.
The Mechanics of Soft Credit Inquiries
When you check for pre-approval on the official American Express website, the issuer initiates a soft credit inquiry. Unlike a hard inquiry—which occurs when you formally apply for credit and can temporarily lower your credit score by a few points—a soft inquiry is merely a review of your credit profile.
- Impact on Credit Score: Soft inquiries are completely invisible to future lenders and have zero impact on your credit score.
- Data Accessed: American Express reviews basic credit data, payment history, and public records to evaluate whether you meet their internal risk parameters.
- Scope of Review: This check allows the algorithm to scan your credit health without committing you to an application or binding the bank to an offer.
Pre-Approval Versus Pre-Qualified Offers
While credit card issuers often use the terms "pre-approved" and "pre-qualified" interchangeably, understanding the distinction is vital for managing expectations.
Historically, direct mail or email solicitations labeled "pre-approved" suggested a higher degree of certainty, whereas online tools labeled "pre-qualified" indicated a simple matching process. In practice, American Express uses these terms to signify that your profile matches the baseline criteria for a specific card. However, neither term constitutes a legally binding contract or a 100% guarantee of final approval.
Submitting a formal application still triggers a secondary review, during which American Express verifies your current income, employment status, housing payments, and recent credit inquiries.
How to Check Your American Express Pre-Approval Status
Checking your status takes only a few minutes and requires basic identifying information. Knowing the correct procedure ensures you navigate the official channels safely and avoid third-party marketing traps.
Step-by-Step Guide to the Online Tool
- Navigate to the Official Source: Go directly to the official American Express website and look for the "Check for Pre-Approval" or "Cards" section. Avoid clicking unverified links from third-party blogs or forums.
- Provide Identifying Information: You will be prompted to enter your full legal name, home address, date of birth, annual income, and the last four digits of your Social Security Number (SSN) or Individual Taxpayer Identification Number (ITIN).
- Select Preferences (Optional): Some prompts allow you to filter by card category, such as travel rewards, cash back, business cards, or no-annual-fee options.
- Review Your Offers: The system will process your information in seconds and display a list of American Express cards for which you show strong eligibility.
Information Required and Data Privacy
Providing sensitive data like your SSN can cause hesitation, but it is necessary for the issuer to pull your credit bureau file accurately. American Express employs bank-grade encryption to protect this data during transmission.
Ensure that you are on the secure americanexpress.com domain before inputting personal details. Double-check that your address matches what credit bureaus have on file to prevent mismatches that could result in an error or a failure to retrieve offers.
Factors That Influence American Express Pre-Approval
Receiving favorable pre-approval results depends on several financial and credit metrics. American Express evaluates these variables holistically to determine which products to present.
Credit Score Thresholds and History
While American Express does not publish exact minimum credit score cutoffs for every card, most premium rewards and travel cards—such as the American Express® Gold Card or The Platinum Card®—generally require good to excellent credit (typically a FICO score of 690 or higher). Cash-back cards or secured options may be accessible to those building or rebuilding credit.
- Payment History: Timely payments across existing revolving and installment accounts carry the heaviest weight.
- Credit Utilization: Keeping your revolving balances well below 30% of your total available credit signals responsible financial management.
- Account Age: A longer average age of open accounts demonstrates stability to the underwriting algorithm.
Internal Risk Policies and Relationship History
Beyond standard credit bureau data, American Express maintains strict internal risk models based on your existing or past relationship with the company.
- Existing Customers: If you already hold an American Express card, the issuer analyzes your internal spending patterns, payment reliability, and account management over time.
- The "Once-in-a-Lifetime" Welcome Offer Rule: American Express restricts welcome bonuses to one per card per lifetime. Pre-approval tools will often display the card, but your internal history dictates whether you are eligible for the introductory bonus points.
- Card Limits: American Express enforces a general limit on the number of personal credit cards and charge cards an individual can hold concurrently (typically up to five credit cards at a time, though charge cards have more flexible limits). Pre-approval offers may be withheld if you are close to these internal caps.
Comparing Hard Pulls vs. Soft Pulls in Credit Applications
| Feature | Soft Inquiry (Pre-Approval) | Hard Inquiry (Formal Application) |
|---|---|---|
| Credit Score Impact | None (0 points) | Temporary dip (typically 2 to 5 points) |
| Visibility to Lenders | Invisible to other financial institutions | Visible to all lenders reviewing your report |
| Purpose | Eligibility check, marketing, account review | Formal credit extension, loan underwriting |
| Binding Agreement | No obligation or commitment | Legally binding credit agreement upon approval |
| Data Verified | Basic credit health and risk metrics | Comprehensive financial review (income, debt-to-income) |
Benefits of Using the Pre-Approval Tool
Utilizing the pre-approval process offers distinct strategic advantages for consumers looking to optimize their wallet composition.
Protecting Your Credit Score
Every hard inquiry signals to lenders that you are actively seeking new credit. Accumulating multiple hard inquiries in a short span can portray financial distress, temporarily lowering your credit score and potentially leading to application rejections. By using the soft-pull pre-approval tool, you can test the waters across multiple cards without accumulating a string of damaging hard inquiries.
Targeted Rewards and Tailored Offers
Pre-approval tools filter out products for which you are unlikely to qualify, saving you time and sparing you from wasted applications. Furthermore, checking pre-approval can occasionally unearth targeted welcome offers featuring higher point bonuses than standard public links.
Common Misconceptions and Limitations
Misunderstandings surrounding pre-approval can lead to unexpected denials or frustration during the application process. Clarifying these limitations ensures realistic expectations.
Pre-Approval is Not Guaranteed Approval
The most common misconception is that pre-approval equals guaranteed issuance. In reality, pre-approval means you have cleared the initial algorithmic hurdle based on a soft credit check.
If your financial situation changes between the pre-approval check and the formal application—such as a sudden drop in credit score, a new high-balance loan, or a discrepancy in reported income—American Express can and will deny the formal application.
Opt-Out Preferences and Marketing Solicitations
If you have previously opted out of receiving prescreened credit offers through major credit bureaus (via OptOutPrescreen.com), you may not receive online pre-approval offers or direct mail solicitations from American Express. Reversing this preference or checking directly via the American Express website can bypass these restrictions.
Troubleshooting Pre-Approval Errors
Sometimes, the pre-approval tool fails to return offers or displays an error message. Understanding why this happens can help you resolve the underlying issue.
Data Mismatches and Security Freezes
- Credit Freezes: If you have placed a security freeze on your credit reports with Equifax, Experian, or TransUnion, American Express cannot access the data required to issue a pre-approval. You must temporarily lift or thaw the freeze to check your status.
- Address or Name Discrepancies: A minor typo in your street address, ZIP code, or a mismatch between your maiden and married name can prevent the system from matching your identity to your credit bureau file.
- Insufficient Credit History: Individuals with thin credit files—those who have only recently opened their first credit account—may not have enough data for the automated system to generate a reliable pre-approval offer.
Next Actions and Strategic Recommendations
Once you have checked your American Express pre-approval status and identified a card that aligns with your spending habits and financial goals, proceed with the following steps:
- Review the Card Terms: Carefully examine the cardmember agreement, annual fees, foreign transaction fees, and the specific terms of the welcome offer.
- Weigh the Annual Fee: Ensure that the value of the card's rewards, credits, and travel perks outweighs the cost of the annual fee.
- Proceed with Confidence: If you are satisfied with the terms, submit the formal application through the pre-approval portal to lock in your offer. Be prepared to provide immediate income verification if requested by American Express underwriting.