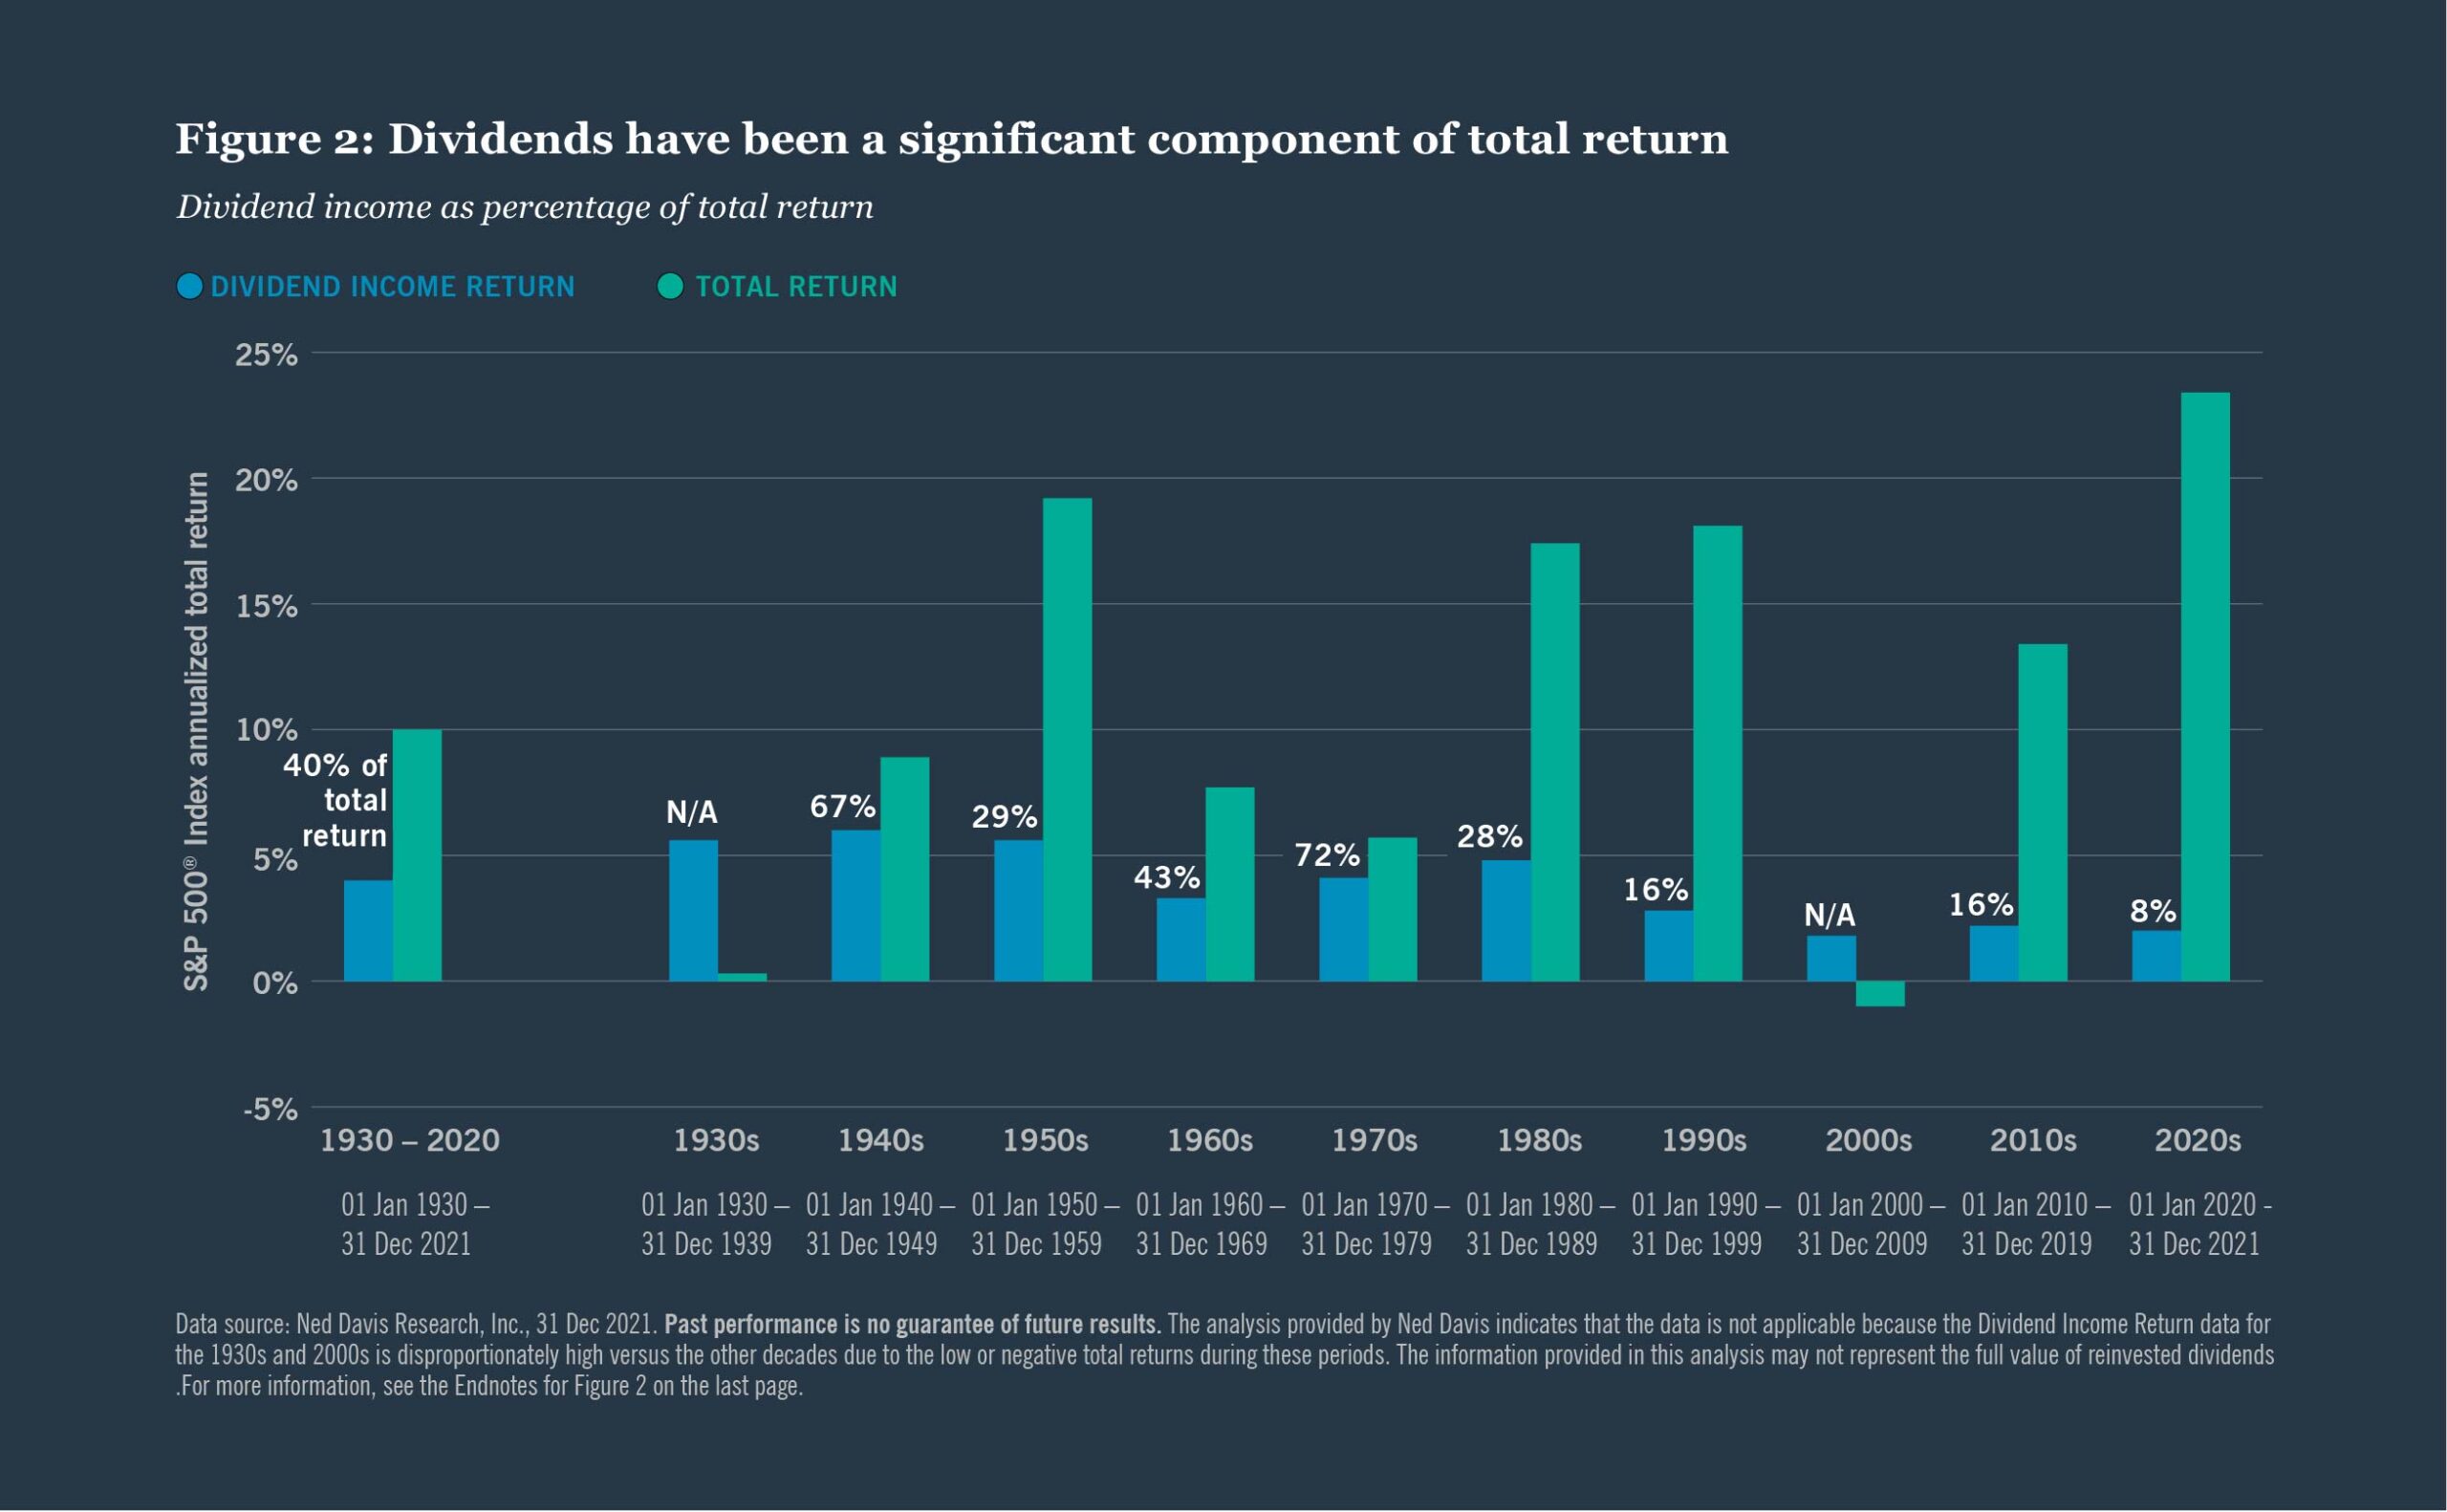
The S&P 500 dividend yield typically fluctuates between 1.5% and 2.5%, representing the weighted average of annual cash dividends paid by all 500 constituent companies relative to their aggregate share price. While individual stocks within the index may offer much higher or lower payouts, this broad benchmark serves as a vital macroeconomic indicator for equity valuation, income generation, and market sentiment.
Introduction to the S&P 500 Dividend Yield
When evaluating the performance and characteristics of the United States stock market, investors frequently encounter references to the S&P 500 index. Beyond capital appreciation—the growth in stock prices over time—shareholders often look to dividends as a steady source of cash flow. Understanding what the dividend yield of the S&P 500 represents, how it is calculated, and why it changes over time is essential for anyone building a balanced, long-term portfolio.
The phrase "10 5 dividend yield sandp 500 explained" often stems from a combination of numeric figures, search queries, or misconceptions regarding historical averages, sector allocations, or specific payout thresholds. To clear up any confusion, it is important to note that the S&P 500's aggregate dividend yield has historically hovered well below 10% or 5% at any given point in recent decades, typically resting closer to 1.5% to 2.5%. This comprehensive guide breaks down the true mechanics of the S&P 500 dividend yield, explores historical context, examines the influence of sector weightings, and provides practical guidance for income-focused investors navigating the modern market.
How the S&P 500 Dividend Yield Is Calculated
To understand why a 10% or 5% yield is uncommon for the S&P 500 as a whole, one must first examine the mathematical formula behind index-level dividend yields. Unlike a single stock where the calculation is simply the annual dividend divided by the current share price, the S&P 500 is a capitalization-weighted index.
The index yield is calculated by taking the total aggregate annual dollar amount of dividends paid by all 500 constituent companies and dividing that sum by the total market capitalization of the entire index. Alternatively, it can be viewed as a market-cap-weighted average of the individual dividend yields of every company in the index.
Because mega-cap technology and growth companies—such as Apple, Microsoft, Amazon, and Alphabet—comprise a massive portion of the index's total market capitalization and often pay lower dividend yields (or reinvest cash flows into growth), they exert a powerful gravitational pull on the aggregate index yield. Even if several smaller utility or financial firms within the index pay 4% to 6% yields, their lower market capitalization means they cannot single-handedly push the overall S&P 500 yield up to 5% or 10%.
Historical Context and Baseline Benchmarks
Looking back over the past several decades, the dividend yield of the S&P 500 has experienced distinct structural shifts. Understanding these historical norms helps contextualize why expecting a 5% or 10% yield from a broad market index fund is unrealistic under normal economic conditions.
During the high-inflation era of the early 1980s, S&P 500 dividend yields reached peaks above 6%. However, as equity markets evolved, corporate behavior shifted. Rather than returning all excess cash to shareholders via dividends, companies increasingly favored share repurchase programs (buybacks) and reinvestment in research and development. By the late 1990s dot-com boom, the S&P 500 dividend yield compressed to historic lows around 1.1%. In the wake of the 2008 financial crisis and through the prolonged low-interest-rate environment of the 2010s, the yield generally ranged between 1.8% and 2.2%.
| Period / Market Phase | Average S&P 500 Dividend Yield | Primary Market Drivers |
|---|---|---|
| 1980s High-Inflation Era | 4.5% – 6.0% | High interest rates, heavy reliance on cash payouts over buybacks. |
| Late 1990s Tech Boom | 1.1% – 1.5% | Soaring valuations, dominance of non-dividend-paying growth stocks. |
| Post-2008 Recovery Era | 1.8% – 2.5% | Moderate economic growth, return of steady corporate payouts. |
| Current Market Environment | 1.3% – 1.8% | Heavy weighting toward mega-cap tech and capital reinvestment. |
Note: Historical yield ranges are compiled from verified financial market data providers and represent aggregate index trailing twelve-month figures.
Why High Yields (Like 5% or 10%) Are Rare in the S&P 500
Investors searching for terms related to high yields often desire substantial passive income. However, a yield of 5% or 10% for the entire S&P 500 is mathematically and economically improbable under standard market conditions.
The Mechanics of Share Price and Yield Inversity
Dividend yield moves inversely to share price. If a company's stock price drops drastically, its dividend yield mathematically spikes. Therefore, if the entire S&P 500 were to exhibit a 10% dividend yield, it would indicate a catastrophic collapse in stock prices across the board—a severe systemic market crash reminiscent of the Great Depression.
Capital Allocation Preferences
Modern corporate finance heavily emphasizes total shareholder return rather than dividends alone. Many of the most profitable corporations in the S&P 500 prefer share buybacks. Buybacks reduce share count, theoretically increasing earnings per share and boosting stock prices without locking the company into a fixed, ongoing cash obligation like a dividend.
Sector Composition
The S&P 500 covers eleven distinct market sectors. While sectors like Utilities, Financials, and Consumer Staples frequently offer higher-than-average yields (often between 3% and 5%), sectors like Information Technology, Communication Services, and Consumer Discretionary offer much lower yields. Because tech heavyweights dominate the index's total weight, the blended average remains low.
Distinguishing the Broad Index from High-Dividend Strategies
Investors who require a higher yield—such as a 4% to 5% baseline—generally cannot rely on a standard, market-cap-weighted S&P 500 index fund. Instead, they must look toward specialized investment vehicles and sub-strategies.
Dividend Aristocrats and Dividend Kings
Indices such as the S&P 500 Dividend Aristocrats focus exclusively on S&P 500 companies that have successfully increased their dividend payments for at least 25 consecutive years. While these portfolios tilt toward mature, stable businesses, their yields still typically land in the 2.5% to 3.5% range rather than extreme double-digit figures.
High-Dividend Yield ETFs
Exchange-traded funds that track high-dividend-yielding subsets of the broad market screen specifically for companies paying top-tier distributions. Even within these targeted funds, sustained yields above 5% often introduce higher concentration risk, exposure to cyclical downturns, or potential "value traps"—companies with high yields driven entirely by falling stock prices rather than fundamental business strength.
Evaluating Total Return vs. Dividend Yield
Relying exclusively on dividend yield when constructing a portfolio can lead to suboptimal decision-making. Professional financial analysts emphasize total return, which combines capital appreciation (price growth) with dividend income reinvested.
Total Return = (Ending Price - Beginning Price + Dividends Distributed) / Beginning Price
A company that pays a 0% dividend yield but grows its stock price by 15% annually provides a superior total return to an investor compared to a stagnant company paying a 6% dividend yield whose stock price declines by 10% annually. While income-oriented investors—such as retirees living off portfolio distributions—prioritize current cash flow, balancing yield against underlying business growth preserves long-term purchasing power against inflation.
Tax Implications of Dividend Income
For taxable brokerage accounts in the United States, receiving dividends triggers tax obligations that investors must account for. The Internal Revenue Service (IRS) categorizes dividends into two primary types:
- Qualified Dividends: These meet specific holding period requirements (generally holding the stock for more than 60 days during the 121-day window surrounding the ex-dividend date) and are taxed at preferential long-term capital gains tax rates (0%, 15%, or 20% depending on taxable income). Most S&P 500 company dividends qualify for this status.
- Ordinary (Unqualified) Dividends: These do not meet the holding period requirements and are taxed at ordinary income tax rates, which are typically higher than capital gains rates.
Disclaimer: Tax laws are subject to change and vary based on individual jurisdiction and financial circumstances. Investors should consult a qualified tax professional or certified financial planner before making major portfolio adjustments.
Common Misconceptions Regarding S&P 500 Payouts
- "Companies are required to pay dividends." — No law or corporate charter forces a publicly traded company to distribute dividends. Management and the Board of Directors retain full discretion to initiate, maintain, increase, decrease, or eliminate dividends at any time based on cash flow needs.
- "A high dividend yield guarantees safety." — High yields can sometimes signal financial distress. If a company's business model is declining, its stock price drops, pushing the yield up temporarily just before a dividend cut is announced.
- "Dividends are free money." — When a stock goes ex-dividend, the exchange automatically reduces the share price by the exact amount of the dividend distribution. The cash received by the investor is offset by an equivalent drop in share value on that trading day.
Frequently Asked Questions
What is the historical average dividend yield of the S&P 500?
Over the past 50 years, the historical average dividend yield of the S&P 500 has averaged roughly 2% to 3%. However, in recent decades, as tech and growth stocks have expanded their share of the index market capitalization, that average has trended closer to 1.5% to 2.0%.
Can I get a 5% to 10% yield from an S&P 500 index fund?
No. A standard S&P 500 index fund cannot naturally sustain a 5% to 10% dividend yield under normal macroeconomic conditions. Achieving a 5% yield requires selecting specialized high-dividend ETFs, individual dividend stocks, or alternative asset classes such as real estate investment trusts (REITs) or fixed-income instruments.
Why do some S&P 500 companies pay no dividends at all?
Many growth-oriented companies—particularly in the technology sector—choose to retain all earnings to fund research, capital expenditures, acquisitions, and business expansion. Management often believes that reinvesting capital into high-return internal projects generates more long-term wealth for shareholders than distributing cash dividends that trigger immediate taxable events.
How often are S&P 500 dividends paid?
Most constituent companies within the S&P 500 distribute dividends on a quarterly basis (four times per year). When holding an S&P 500 index fund or ETF, the fund manager typically collects these underlying corporate payouts and distributes them to fund shareholders either quarterly or monthly, depending on the specific fund's structure.
Does a higher dividend yield mean better performance?
Not necessarily. Academic studies and historical market data demonstrate that high-dividend-yielding stocks can outperform during specific economic cycles (such as inflationary or low-growth environments), but they frequently lag broader market benchmarks during secular bull markets driven by technological innovation and aggressive growth.
Practical Next Actions for Investors
If you are evaluating your portfolio's income generation relative to the S&P 500, take the following steps:
- Assess Your Income Goals: Determine whether you need immediate cash flow or are primarily focused on long-term capital accumulation.
- Review Asset Allocation: Examine your holdings to see if your portfolio relies solely on broad market index funds or incorporates targeted income strategies.
- Consult Professional Guidance: Speak with a licensed financial advisor to align your dividend and growth strategy with your personal tax situation and retirement timeline.