Navigating life insurance in later life requires balancing financial protection needs with policy accessibility, and obtaining AARP members life insurance quotes provides a gateway to specialized coverage options designed specifically for older adults. These policies, made available through the AARP Life Insurance Program administered by New York Life Insurance Company, offer tailored financial products including term life, whole life, and guaranteed acceptance whole life insurance. Securing an accurate quote involves evaluating your age, desired coverage amount, health history, and membership status to determine the most cost-effective and appropriate protection for your final expenses, income replacement, or estate planning goals.
The AARP Life Insurance Program Structure Explained
The AARP Life Insurance Program is not an insurance company itself; rather, it is a portfolio of insurance products officially sponsored by AARP and issued by New York Life Insurance Company. This distinction is crucial for members seeking quotes, as the underwriting standards, policy administration, and financial backing are provided by New York Life, an insurer with extensive history and high financial strength ratings.
Understanding this structure helps demystify how quotes are generated. When you request a quote through the AARP program, you are looking at proprietary products designed in collaboration with AARP to meet the unique needs of its members, typically individuals aged 50 and older. Because these policies are group-endorsed, they often feature simplified application processes that bypass the rigorous medical exams required by traditional individual policies, though this convenience can influence premium pricing and coverage limits.
Membership in AARP is a mandatory prerequisite to apply for and hold these insurance policies. While you can explore general rate tables online or through informational brochures without being a member, you must officially join AARP before an application can be processed or a policy can be issued. This requirement ties the longevity of your policy privileges to your active membership status, though the underlying contracts themselves are guaranteed renewable as long as premiums are paid on time.
Primary Types of Life Insurance Policies Available Through AARP
When requesting quotes through the AARP Life Insurance Program, you will typically encounter three primary categories of coverage. Each type serves a distinct financial purpose, features different underwriting requirements, and calculates quotes based on unique criteria.
Level Benefit Term Life Insurance
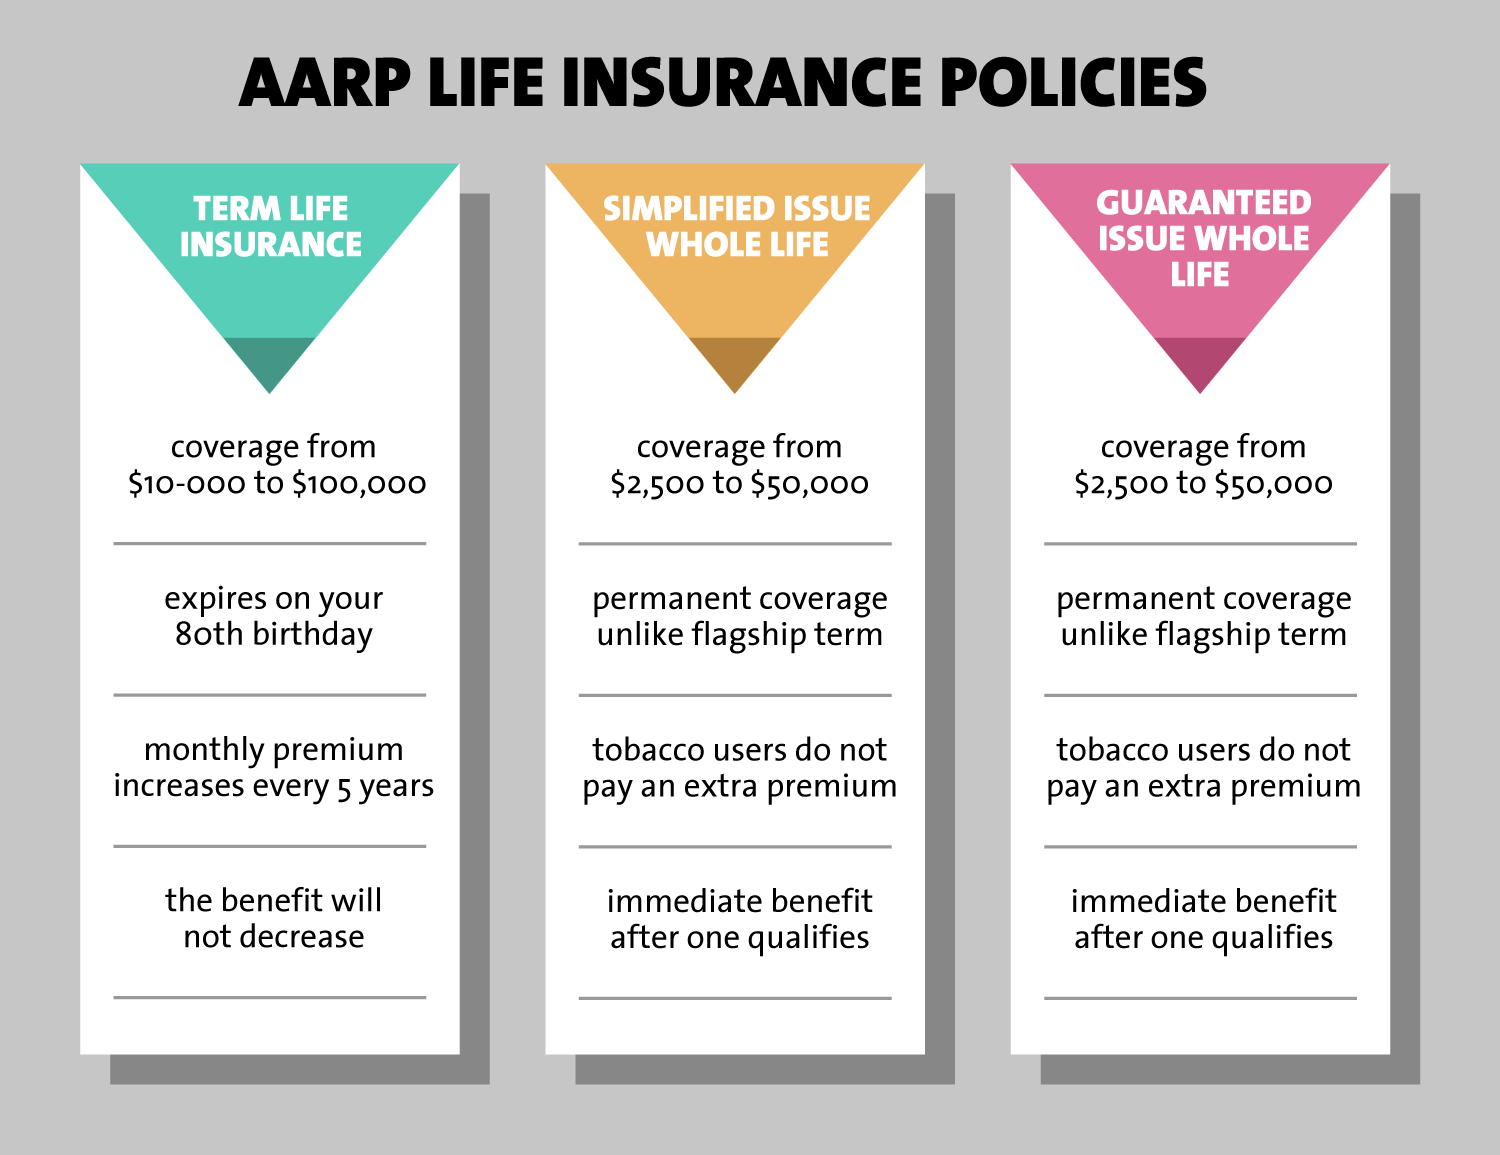
Term life insurance provides coverage for a specific period or "term," typically renewable up to a certain age (such as age 80). The primary advantage of term life is that it offers higher coverage amounts at more affordable initial rates compared to permanent insurance.
- Quote Dynamics: Quotes for term life depend heavily on your exact age at the time of application and your gender.
- Renewability: Premiums typically increase at predetermined age brackets (every five years) as you enter older age bands.
- Purpose: Ideal for income replacement, paying off a remaining mortgage, or providing temporary financial support for dependents.
Permanent Whole Life Insurance
Whole life insurance provides lifetime coverage, meaning it stays in effect as long as you pay the premiums. Unlike term policies, whole life includes a cash value component that grows at a guaranteed rate on a tax-deferred basis.
- Quote Dynamics: Quotes are level, meaning the premium you lock in when you first purchase the policy will never increase due to your advancing age.
- Cash Value: A portion of your premium builds equity over time, which you can borrow against if necessary.
- Purpose: Designed for lifetime protection, final expense coverage, and leaving a guaranteed legacy or inheritance.
Guaranteed Acceptance Whole Life Insurance
Guaranteed acceptance policies are specifically structured for individuals who may have health conditions that would ordinarily disqualify them from traditional life insurance coverage.
- No Medical Exam or Questions: Underwriting does not require a medical exam, and you cannot be turned down based on your health history.
- Graded Death Benefit: Be aware that these policies typically feature a graded death benefit. If death occurs from natural causes within the first two policy years, beneficiaries may receive a refund of premiums paid plus interest, rather than the full face value, though accidental death is usually covered immediately.
- Purpose: Securing guaranteed funds specifically for burial costs, medical bills, or minor debts without health hurdles.
| Policy Type | Medical Requirements | Premium Behavior | Cash Value Component | Primary Use Case |
|---|---|---|---|---|
| Level Benefit Term | Health questions / possible exam depending on age/amount | Increases every 5 years as you age | No | Temporary needs, income replacement, debt coverage |
| Permanent Whole Life | Health questions required | Level (never increases) | Yes | Lifetime protection, building cash value, final expenses |
| Guaranteed Acceptance | None (No health questions or exams) | Level (never increases) | Yes | Guaranteed coverage regardless of health status |
Key Factors That Influence AARP Life Insurance Quotes
Generating a quote for life insurance through the AARP program involves several actuarial and personal variables. While group-sponsored insurance aims to streamline the process, certain non-negotiable risk factors dictate the final cost of your monthly or annual premium.
Age and Gender
Age is the most dominant factor in life insurance pricing. Because the probability of a claim increases as a person ages, quotes rise incrementally with every year of chronological age. Furthermore, statistical mortality tables show that women generally have a longer life expectancy than men, which typically results in lower term and permanent life insurance quotes for female applicants of the same age.
Coverage Amount (Face Value)
The total payout your beneficiaries will receive upon your passing directly impacts your quote. Higher face values require higher premium contributions. The AARP Life Insurance Program sets maximum and minimum coverage thresholds depending on the product type, ensuring that policies remain financially viable for both the insurer and the insured member.
Health History and Tobacco Use
While products like guaranteed acceptance bypass health evaluations, traditional term and permanent whole life policies require applicants to answer health-related questions. Your medical history, including chronic conditions, medications, and particularly tobacco use, will be evaluated. Smokers or users of nicotine products face significantly higher rate brackets due to the associated health risks.
Step-by-Step Guide to Requesting and Comparing Quotes
Obtaining an accurate, personalized quote through the AARP Life Insurance Program requires a methodical approach. Follow these steps to ensure you gather precise financial estimates without unnecessary delays.
- Verify AARP Membership: Ensure your AARP membership is active. You will need your membership number or basic personal verification details to access official, personalized quoting tools.
- Determine Your Coverage Needs: Calculate the financial obligations you wish to leave behind. Consider final expenses, outstanding loans, ongoing living expenses for a surviving spouse, or a specific legacy gift.
- Visit the Official Program Portal: Navigate to the official New York Life-administered AARP Life Insurance Program website. Avoid third-party aggregator sites that may provide generalized estimates rather than exact carrier quotes.
- Input Personal Data: Provide your birth date, gender, state of residence, and tobacco use status into the online quote calculator.
- Select Policy Type and Coverage Level: Adjust the slider or input fields for term or whole life coverage amounts to see how monthly premiums shift in real-time.
- Review the Application Requirements: Examine whether the chosen quote requires answering health questions or undergoing further underwriting verification.
Evaluating Value: Pros and Limitations of AARP-Endorsed Policies
Before finalizing any life insurance application based on a quote, it is essential to weigh the distinct advantages of the AARP program against its operational limitations. A balanced evaluation ensures the policy aligns with your broader financial plan.
Advantages of the Program
- Trusted Insurer Backing: Policies are issued by New York Life Insurance Company, an institution holding exceptional financial strength ratings from major rating agencies.
- Simplified Underwriting: Many products eliminate the need for invasive medical exams, allowing older adults to secure coverage quickly.
- Specialized Age Matching: Products are intentionally engineered for adults aged 50 and over, addressing life stages where traditional commercial policies become cost-prohibitive or unavailable.
- Guaranteed Renewability: Once your policy is active, the insurer cannot cancel it as long as you pay your premiums on time and maintain your AARP membership.
Limitations and Considerations
- Term Premium Increases: For term life products, premiums rise every five years as you cross age thresholds, which can make long-term budgeting challenging on a fixed retirement income.
- Coverage Caps: Maximum face values for older applicants may be lower than what is available through specialized individual underwriting markets.
- Graded Benefits on Guaranteed Plans: If you choose guaranteed acceptance to bypass health checks, remember the waiting period restrictions on natural death benefits during the initial policy years.
- Membership Dependency: You must maintain your AARP membership to keep your policy active and serviced under the program guidelines.
Common Mistakes to Avoid When Shopping for Senior Life Insurance
Navigating life insurance quotes later in life can lead to costly miscalculations if certain pitfalls are not avoided. Being aware of these common errors helps protect your financial interests.
- Underestimating Future Premium Jumps: When buying term insurance, failing to look at the future rate schedule for subsequent age brackets can result in unaffordable premiums down the road.
- Delaying Application: Waiting until health conditions deteriorate significantly forces reliance on guaranteed acceptance policies, which feature higher costs per dollar of coverage and graded benefit clauses.
- Confusing Group Insurance with Individual Policies: AARP life insurance is a group policy endorsed by an organization. Ensure you understand how group administration rules differ from individually owned policies.
- Overlooking Riders and Add-ons: Failing to review available policy riders—such as accelerated death benefits for terminal illness—can leave valuable policy features unutilized.
Frequently Asked Questions About AARP Members Life Insurance Quotes
Do I have to be an AARP member to get a quote?
You can review general rate tables and educational materials without being a member, but you must join AARP before you can formally submit an application or have a policy issued in your name through the official program.
Are medical exams mandatory to secure an AARP life insurance quote?
It depends entirely on the product selected. Guaranteed acceptance whole life insurance requires no medical exam or health questions. Traditional term and permanent whole life policies require answering health questions, though physical exams are often waived depending on your age and the coverage amount requested.
Can my AARP life insurance rates increase as I get older?
It depends on the policy type. Level benefit term insurance rates increase every five years as you enter new age brackets. Conversely, permanent whole life and guaranteed acceptance policies feature level premiums that remain fixed for the life of the policy.
What happens if I miss a premium payment?
Policies typically include a grace period (usually 31 days) to make late payments without lapsing coverage. If premiums remain unpaid past the grace period, the policy may terminate, though whole life policies may utilize cash value features to keep coverage active automatically depending on the accumulated equity.
How do I submit a claim or manage my policy after purchasing?
Because the policies are issued and serviced by New York Life Insurance Company, all ongoing administration, premium billing, customer service inquiries, and death claim filings are handled directly through New York Life's dedicated customer support channels for AARP members.
Practical Next Steps for Securing Coverage
Begin your process by listing your current financial liabilities, anticipated final expenses, and the liquid assets available to your family. Once your financial inventory is complete, log into the official AARP Life Insurance Program portal to run side-by-side quotes for term versus whole life products. Compare these figures against your monthly retirement budget to ensure long-term affordability. If you have complex estate planning needs or chronic health conditions, consider consulting an independent financial advisor or insurance professional to evaluate how an AARP-endorsed policy fits alongside your existing retirement and Social Security planning.