Determining if a payday loan in Fresno is "worth it" depends on your immediate liquidity needs versus the high cost of borrowing. In 2026, California law limits these loans to $300 with a maximum fee of $45. While they provide instant cash for emergencies, the 400%+ APR makes them an expensive last resort.
The Financial Landscape of Payday Lending in Fresno
In 2026, Fresno remains a hub for various financial services catering to the Central Valley's diverse workforce. From the agricultural sector to the growing healthcare corridor, residents often face timing gaps between paychecks. Payday loans, technically known in California as Deferred Deposit Transactions, are marketed as a bridge over these gaps. However, the question of their "worth" is not just about availability; it is about the long-term impact on your financial health.
To understand if these loans are worth it, one must first understand the strict regulatory environment governed by the California Department of Financial Protection and Innovation (DFPI). Unlike some states where loan amounts can reach thousands of dollars, California has maintained a conservative cap. This cap protects consumers from massive debt but also means the "utility" of the loan is limited to relatively small emergencies, such as a minor car repair or a utility bill.
Understanding the Legal Framework in California (2026)
When you walk into a storefront on Blackstone Avenue or apply online from a Fresno-based IP address, you are entering a contract governed by the California Deferred Deposit Transaction Law. As of 2026, the fundamental rules remain unchanged, providing a predictable but high-cost framework for borrowers.
The $300 Maximum Limit
The most significant constraint is the $300 loan limit. It is vital to note that this $300 includes the fee. In practice, if a lender charges the maximum allowed fee, you will only receive $255 in cash, while providing a post-dated check for $300. For many Fresno families facing 2026 housing costs and inflation, $255 may not cover a full emergency, which is a primary reason critics argue these loans are rarely "worth it."
Fee Structures and APR
California law permits a maximum fee of 15% of the face amount of the check. While 15% sounds low compared to credit card interest rates, it is deceptive because of the short duration of the loan.
- Face amount of check: $300.00
- Maximum fee (15%): $45.00
- Amount advanced to borrower: $255.00
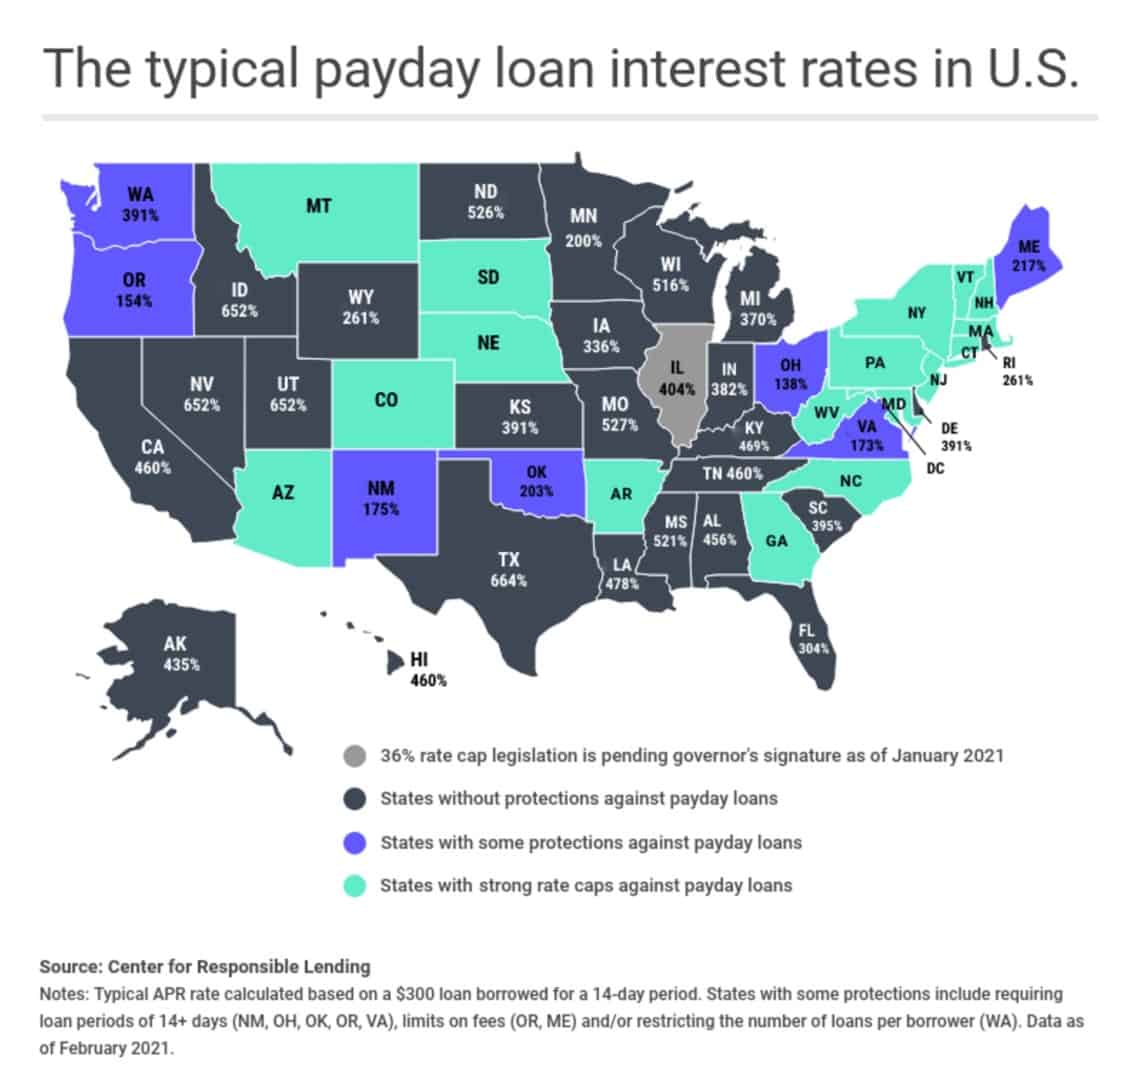
- Annual Percentage Rate (APR): For a 14-day loan, this equates to approximately 460%.
When comparing this to a standard personal loan (10-30% APR) or even a high-interest credit card (25-35% APR), the payday loan is exponentially more expensive.
Why Fresno Residents Consider Payday Loans
Despite the high costs, the payday loan industry in Fresno continues to thrive in 2026. This persistence is driven by several factors unique to the local economy and the specific hurdles faced by subprime borrowers.
Speed and Accessibility
For a resident in the Tower District or Southeast Fresno who needs cash within the hour, few alternatives exist. Most payday lenders in Fresno offer "instant" approval. If you have a valid ID, a steady income source (even disability or Social Security), and an active checking account, you can typically walk out with cash or have a deposit initiated immediately.
No Traditional Credit Check
Most Fresno payday lenders do not use "Hard Pull" credit inquiries through Experian, Equifax, or TransUnion. Instead, they use specialized services like Teletrack or Clarity Services to see if you have outstanding payday loans with other lenders. This makes them "worth it" in the narrowest sense for individuals whose credit scores have been decimated by past defaults and who are barred from traditional banking products.
Lack of Banking Alternatives
While Fresno has seen an increase in credit union branches, a significant portion of the population remains "underbanked." For those without a credit limit on a card or a pre-existing personal line of credit, the payday storefront becomes a default financial institution.
The True Cost: Analyzing the "Debt Trap" in the Central Valley
The primary argument against payday loans being "worth it" is the high probability of the debt cycle. In Fresno, where the cost of living has risen steadily through 2026, many borrowers find that after paying back the $300 from their next paycheck, they lack the funds to cover that month’s basic expenses.
The Rollover Prohibition
California law strictly prohibits "rolling over" a loan. A lender cannot charge you a fee to extend the loan. You must pay the loan in full before taking another. However, a common practice in Fresno is the "back-to-back" loan. A borrower pays off the $300 on Friday and immediately takes out a new $300 loan to cover the hole the repayment left in their budget.
Indirect Costs
Beyond the $45 fee, there are significant risks of indirect costs:
- NSF Fees: If the lender attempts to cash your post-dated check and your account has insufficient funds, your bank may charge you $25–$35 per attempt.
- Lender Penalties: California law allows lenders to charge a single $15 NSF fee if your check bounces.
- Credit Impact: While the loan itself doesn't usually help your credit score, a default that is sold to a collection agency will severely damage it.
Comparing Payday Loans to Local Alternatives in Fresno
Before committing to a high-interest loan, Fresno residents should evaluate local alternatives that have expanded in 2026. Many of these provide the same liquidity at a fraction of the cost.
Payday Alternative Loans (PALs)
Local credit unions, such as Educational Employees Credit Union (EECU) or Noble Credit Union, often offer PALs. These are regulated by the National Credit Union Administration (NCUA).
- Interest Rates: Capped at 28%.
- Loan Amounts: Often $200 to $1,000.
- Repayment Terms: One to six months, allowing for much smaller, manageable payments compared to the 14-day "balloon" payment of a payday loan.
Employer Sponsored Advances
By 2026, many large Fresno employers in the healthcare and logistics sectors have partnered with "Earned Wage Access" (EWA) providers like DailyPay or Earnin. These services allow you to access money you have already earned before payday for a small flat fee or even for free, avoiding the 400% APR trap entirely.
Community Organizations and Non-Profits
Fresno has a robust network of community support. Organizations like the Fresno Economic Opportunities Commission (EOC) may offer emergency assistance or financial literacy programs that help residents navigate crises without resorting to high-interest debt.
| Feature | Payday Loan (Storefront) | Credit Union (PAL) | Earned Wage Access (EWA) |
|---|---|---|---|
| Max Amount | $300 | $1,000 | Percentage of earned wages |
| Typical APR | 460% | 28% | 0% - 15% (fees vary) |
| Repayment Term | 14–31 days | 1–6 months | Next payday |
| Credit Check | No (Usually) | Yes (Soft/Hard pull) | No |
| Speed | Immediate | 1–3 business days | Immediate |
When Is a Payday Loan "Worth It"?
There are very narrow circumstances where a payday loan might be considered a rational, though expensive, choice in 2026:
- Avoiding a Greater Loss: If the $255 prevents a utility disconnection that carries a $100 reconnection fee, or prevents a late rent payment that carries a $150 penalty, the $45 fee is technically the "cheaper" option.
- No Other Access to Capital: If you have exhausted all family help, credit union options, and employer advances, and the need is an absolute emergency (e.g., medical or essential transit).
- Certainty of Repayment: If you are 100% certain you will have the funds to pay it back and not take out another loan immediately, the damage is contained to a one-time $45 loss.
In almost all other scenarios, the math does not favor the borrower. The high cost of credit in the Fresno market essentially functions as a "poverty tax," extracting wealth from the residents who can least afford it.
How to Verify a Payday Lender in Fresno
If you decide to proceed, you must ensure the lender is licensed. Unlicensed "offshore" or "tribal" lenders often ignore California’s $300 cap and $45 fee limit, charging interest rates that can exceed 700% or 800%.
- Check the DFPI Database: Visit the California Department of Financial Protection and Innovation website to verify a lender's license.
- Review the Contract: Ensure the contract clearly states the "Finance Charge" and the "Annual Percentage Rate." Under the Federal Truth in Lending Act (TILA), these must be disclosed prominently.
- Look for Physical Presence: Storefronts in Fresno are subject to local inspections and state oversight. Online-only lenders with no physical California address are higher risk.
Step-by-Step: What to Do if You Can't Repay
By 2026, California has strengthened protections for borrowers who find themselves unable to pay back their Fresno payday loan. If you are facing a default, follow these steps:
- Request a Payment Plan: While not mandatory for all lenders under all conditions, many Fresno lenders will offer an "Extended Payment Plan" (EPP) if you notify them before the check is cashed.
- Revoke ACH Authorization: If you borrowed online, you have the right to revoke the lender's access to electronically withdraw funds from your bank account. You must do this at least three business days before the scheduled payment.
- Consult the DFPI: If a lender in Fresno threatens you with criminal prosecution (jail time), they are violating the law. Payday loans are civil matters, not criminal. You can file a complaint with the DFPI.
Frequently Asked Questions
Can I have multiple payday loans in Fresno at once?
Under California law, you cannot have more than one loan with the same lender at a time. While the law doesn't strictly prevent you from going to a second lender, the industry uses databases like Clarity to see your active loans. Most reputable Fresno lenders will deny your application if they see another outstanding payday loan, as this significantly increases the risk of default.
Do Fresno payday lenders check my credit score?
Most do not perform a "Hard Pull" on your FICO score. They focus on your income and your history with other short-term lenders. This is why these loans are popular among Fresno residents with poor credit history. However, some 2026 fintech lenders may use "Soft Pulls" which do not affect your score but give them a better picture of your financial stability.
What happens if I move away from Fresno without paying?
The debt does not disappear. The lender can sell the debt to a collection agency, which will likely report it to the major credit bureaus, severely damaging your credit score for up to seven years. They can also sue you in civil court to garnish your wages, regardless of where you move within the United States.
Are online payday loans safer than storefronts in Fresno?
Storefronts are generally more transparent because they are easier for state regulators to monitor. Many online lenders claiming to serve Fresno are actually operating from outside California or the U.S. to bypass the $300 limit and 15% fee cap. Always ensure an online lender is licensed specifically by the California DFPI.
Is there a "cooling-off" period in California?
California law does not mandate a specific "cooling-off" period between loans with different lenders. However, it does prohibit "rollovers" with the same lender. Once you pay off a loan, the lender is technically allowed to issue you a new one immediately, though this is the primary mechanism of the debt trap.
Expert Recommendation
Before taking out a payday loan in Fresno in 2026, exhaust every other possibility. Start by contacting a local credit union like EECU or Noble to see if you qualify for a Payday Alternative Loan. If your need is driven by a utility bill, contact PG&E or the City of Fresno directly to ask for a hardship-based payment plan.
A payday loan is only "worth it" if it is used as a one-time surgical tool for a genuine emergency that costs more to ignore than the $45 fee. If you find yourself considering a payday loan to cover recurring costs like rent or groceries, the loan will likely worsen your situation rather than solve it. Seek local credit counseling services instead to address the underlying budget shortfall.