For the 2025 tax year, the IRS set the standard mileage rate at 67.5 cents per mile for business travel, a slight increase from the previous year. This rate allows taxpayers and businesses to calculate the deductible costs of operating an automobile for business, charitable, medical, or moving purposes without tracking every individual receipt for fuel and maintenance.
Understanding the 2025 mileage rates is essential for maintaining compliance with tax regulations and ensuring that reimbursements remain non-taxable. While many people use the term "per diem" to describe these rates, they are technically the IRS Standard Mileage Rates. However, they function similarly to a per diem by providing a fixed, simplified reimbursement amount per unit of activity—in this case, per mile driven.
The Official 2025 IRS Standard Mileage Rates
Each year, the Internal Revenue Service (IRS) adjusts the standard mileage rates based on an annual study of the fixed and variable costs of operating an automobile. This includes depreciation, insurance, repairs, tires, maintenance, gas, and oil. For the 2025 period (which remains the benchmark for 2025 tax filings completed in 2026), the rates are as follows:
| Category | 2025 Rate (per mile) | 2024 Rate (for comparison) |
|---|---|---|
| Business | 67.5 cents | 67 cents |
| Medical | 19 cents | 21 cents |
| Moving (Active Duty Military) | 19 cents | 21 cents |
| Charitable | 14 cents | 14 cents |
The slight increase in the business rate reflects the rising costs of vehicle ownership, including insurance premiums and vehicle maintenance, which balanced out fluctuations in fuel prices during the evaluation period. Interestingly, the medical and moving rates saw a decrease, primarily driven by changes in the variable cost components analyzed by the IRS’s independent contractor, Runzheimer International.
The Difference Between Mileage Rates and Per Diem
It is common to see the term "mileage per diem" in corporate policy manuals, but it is important to distinguish between two different IRS concepts: the Standard Mileage Rate and Per Diem Rates.
Standard Mileage Rate
This applies specifically to the use of a vehicle. It covers all costs associated with the car. If an employee is paid 67.5 cents per mile in 2025, that payment is intended to cover their gas, the wear and tear on the vehicle, their insurance, and even the eventual replacement of the car (depreciation).
Per Diem (M&IE and Lodging)
Per diem, governed largely by the General Services Administration (GSA) for domestic travel, refers to daily allowances for lodging, meals, and incidental expenses (M&IE). For 2025, these rates vary significantly by location (e.g., a higher per diem for New York City than for a rural town). You can find specific daily rates on the GSA Per Diem Rates page.
When a company says they "pay a mileage per diem," they are usually referring to the IRS standard mileage rate applied to the distance traveled, often in addition to a standard per diem for food and lodging if the trip involves an overnight stay.
How the 2025 Rates are Calculated
The IRS does not choose these numbers at random. The business rate is based on an annual study of the fixed and variable costs of operating an automobile. Fixed costs include items like insurance, registration fees, and depreciation. Variable costs include gas, oil, and maintenance.
For the charitable rate, the number is actually set by federal statute (Title 26 of the U.S. Code) and has remained at 14 cents per mile for many years. It requires an act of Congress to change, unlike the business and medical rates, which the IRS can adjust administratively based on economic data.
A critical technical detail for tax professionals is the depreciation component of the rate. For 2025, a specific portion of the 67.5 cents—typically around 30 cents per mile—is considered "depreciation." When a taxpayer uses the standard mileage rate, they must reduce the "basis" (the tax value) of their vehicle by this depreciation amount. This prevents a "double dip" where a taxpayer gets a deduction for the car's value twice.
Eligibility: Who Can Use the 67.5 Cent Rate?
Not every driver is eligible to use the standard mileage rate. There are specific restrictions designed to ensure the simplification doesn't lead to excessive deductions.
- Vehicle Ownership: You must own or lease the vehicle.
- Fleet Limits: You cannot use the standard mileage rate if you operate five or more cars at the same time (such as in a fleet operation).
- Method Consistency: If you want to use the standard mileage rate for a car you own, you must choose to use it in the first year the car is available for business use. In later years, you can switch between the standard mileage rate and the "actual expenses" method. However, if you lease a vehicle and choose the standard mileage rate, you must use it for the entire lease period.
- No Section 179: You cannot use the standard mileage rate if you have previously claimed a Section 179 deduction or used the Modified Accelerated Cost Recovery System (MACRS) depreciation for that vehicle.
For employees, the 2025 landscape is governed by the Tax Cuts and Jobs Act (TCJA). Under current law, most W-2 employees cannot deduct unreimbursed business expenses, including mileage, on their federal tax returns. This makes it vital for employees to seek reimbursement through an Accountable Plan provided by their employer.
Implementing an Accountable Plan in 2025
To ensure that mileage reimbursements are not treated as taxable income to the employee, businesses must operate an "Accountable Plan." If a plan is not accountable, the 67.5 cents per mile paid to the employee is treated as wages, subject to W-2 reporting and payroll taxes.
To qualify as an Accountable Plan under IRS rules, the following conditions must be met:
- Business Connection: The expense must have been incurred while performing services as an employee.
- Adequate Accounting: The employee must provide the employer with the date, mileage, destination, and business purpose of the trip within a reasonable period (usually 60 days).
- Returning Excess: If the employer pays the employee more than the standard mileage rate (or more than the actual substantiated miles), the employee must return the excess within a reasonable period (usually 120 days).
If an employer chooses to pay more than the 67.5 cents per mile rate, the excess amount is considered taxable income and must be reported on the employee’s Form W-2.
Record-Keeping Requirements for 2025
The IRS is famously strict regarding documentation for mileage. If a taxpayer is audited, "estimates" or "ballpark figures" are routinely disqualified. To "unpack" the 2025 rates effectively, one must look at the required elements of a mileage log.
According to IRS Publication 463, a contemporaneous log should include:
- The Date: When the trip occurred.
- The Mileage: The starting and ending odometer readings, or the total distance driven.
- The Destination: The specific location (address or business name).
- The Business Purpose: A brief description of why the trip was necessary (e.g., "Client meeting with Smith Corp" or "Post office for business mailings").
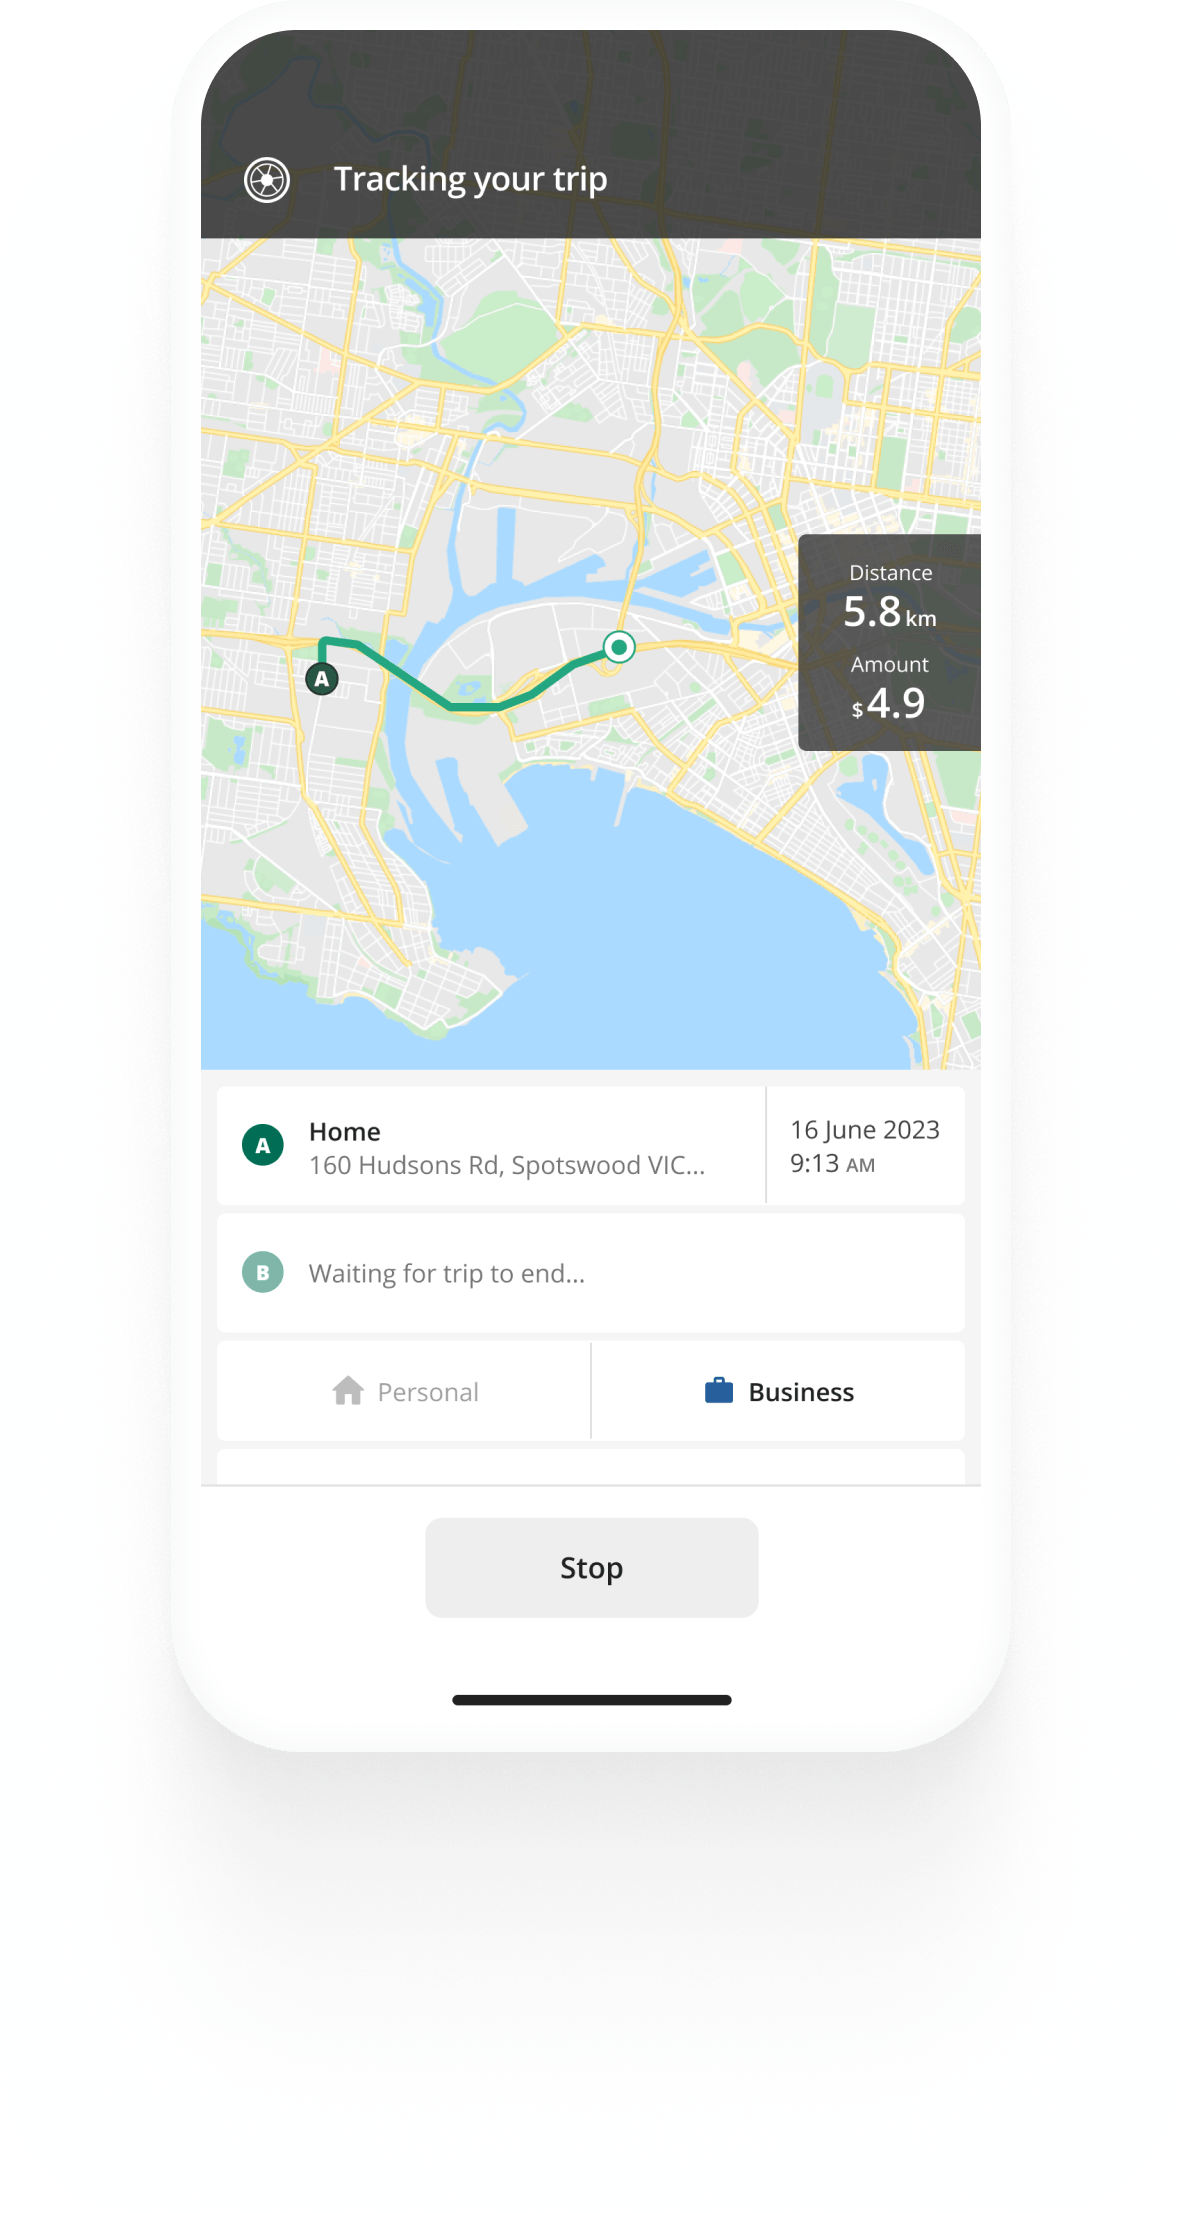
Digital solutions have largely replaced paper logs. In 2026, most businesses require employees to use GPS-based tracking apps that automatically log trips and classify them as "business" or "personal." These apps provide the "high-integrity" data that tax authorities prefer.
Special Considerations: FAVR Plans
For larger organizations, the 67.5 cents per mile rate might not be the most efficient way to handle vehicle costs. Many use a FAVR (Fixed and Variable Rate) plan.
A FAVR plan is a more complex reimbursement method that pays a periodic fixed amount (to cover insurance and registration) plus a periodic variable rate (to cover gas and oil). This method is often seen as more equitable for employees who drive in high-cost areas where the standard 67.5-cent rate might not fully cover their expenses. However, FAVR plans have strict administrative requirements, including a minimum number of miles driven and specific vehicle age and value limits.
Common Pitfalls and Mistakes
Even with a clear rate of 67.5 cents, taxpayers often make errors that result in penalties or lost deductions.
The Commuting Rule
The most common mistake is attempting to deduct "commuting miles." The IRS defines commuting as the trip from your home to your regular place of business. This is considered a personal expense and is never deductible or reimbursable under an accountable plan, regardless of whether you are answering emails or taking business calls during the drive.
Charitable Intent
For the 14-cent charitable rate, the mileage must be directly related to the service you are providing to a qualified 501(c)(3) organization. Simply driving to a church service is not deductible; driving to the post office to mail flyers for a church-run food bank is.
Dual-Purpose Trips
If a trip is part business and part personal, you can only claim the mileage for the business portion. For example, if you drive 50 miles to a business meeting and then drive another 20 miles to visit a relative before returning home, only the direct mileage to and from the business meeting is eligible for the 2025 rate.
Frequently Asked Questions
Can I use the 2025 mileage rate for a motorcycle?
Yes. The IRS standard mileage rate applies to automobiles, which include vans, pickups, and panel trucks, as well as motorcycles. The same 67.5-cent rate for business travel applies to motorcycles in 2025.
What happens if I forgot to keep a log for part of 2025?
While the IRS prefers a contemporaneous log (made at the time of the trip), you can reconstruct a log using calendars, appointment books, and emails. However, this is less reliable and may be scrutinized more heavily during an audit. It is better to use digital records (like Google Maps history) to verify distances if odometer readings were not recorded.
Does the 2025 rate cover tolls and parking?
No. The 67.5-cent rate covers only the operation of the vehicle. You can deduct or be reimbursed for parking fees and tolls separately, in addition to the mileage rate. These are considered separate business expenses.
Is the mileage rate different for electric vehicles (EVs)?
No. As of 2025, the IRS has not established a separate standard mileage rate for electric or hybrid vehicles. The 67.5-cent rate applies regardless of whether the vehicle uses gasoline, diesel, electricity, or hydrogen.
How do the medical mileage rates work for 2025?
In 2025, the rate for medical travel is 19 cents per mile. This applies to travel to and from medical treatments, including trips to the pharmacy or physical therapy. Like charitable mileage, this is only deductible if you itemize your deductions on Schedule A and if your total qualified medical expenses exceed a certain percentage of your adjusted gross income.
Final Recommendation for 2025/2026
For business owners and self-employed individuals, the move from 67 cents to 67.5 cents represents an opportunity to slightly increase deductions for the 2025 tax year. The most effective action you can take is to audit your mileage records now. Ensure that every business trip is supported by a clear destination and business purpose.
If you are an employer, verify that your reimbursement policy explicitly references the 2025 rates to avoid underpaying employees or creating taxable events. If your documentation is lacking, 2026 is the time to implement a digital tracking solution to ensure that next year's filing is seamless and fully compliant with IRS standards.