In short, payday loans in Lebanon (whether referring to the cities in Pennsylvania and Tennessee or the country of Lebanon) are rarely "worth it" due to effective annual percentage rates (APRs) that often exceed 400%. While they offer immediate liquidity for emergencies, the high fees and exceptionally short repayment windows frequently trap borrowers in a persistent cycle of debt.
The term "payday loan" refers to a high-interest, short-term bridge loan intended to cover expenses until the borrower's next paycheck. Because "Lebanon" is a name shared by a sovereign nation in the Middle East and several significant municipalities in the United States—most notably Lebanon, Pennsylvania, and Lebanon, Tennessee—the answer to whether these loans are worth it depends heavily on the local regulatory environment and the specific economic conditions of 2026.
Resolving the Lebanon Location Ambiguity
When evaluating the value of a payday loan in Lebanon, one must first identify the jurisdiction. In the United States, "payday lending" is a specific legal category of finance. In the Republic of Lebanon, the financial sector has faced extreme volatility since 2019, making formal "payday loans" almost non-existent in the traditional sense, replaced instead by informal lending or high-interest micro-credit.
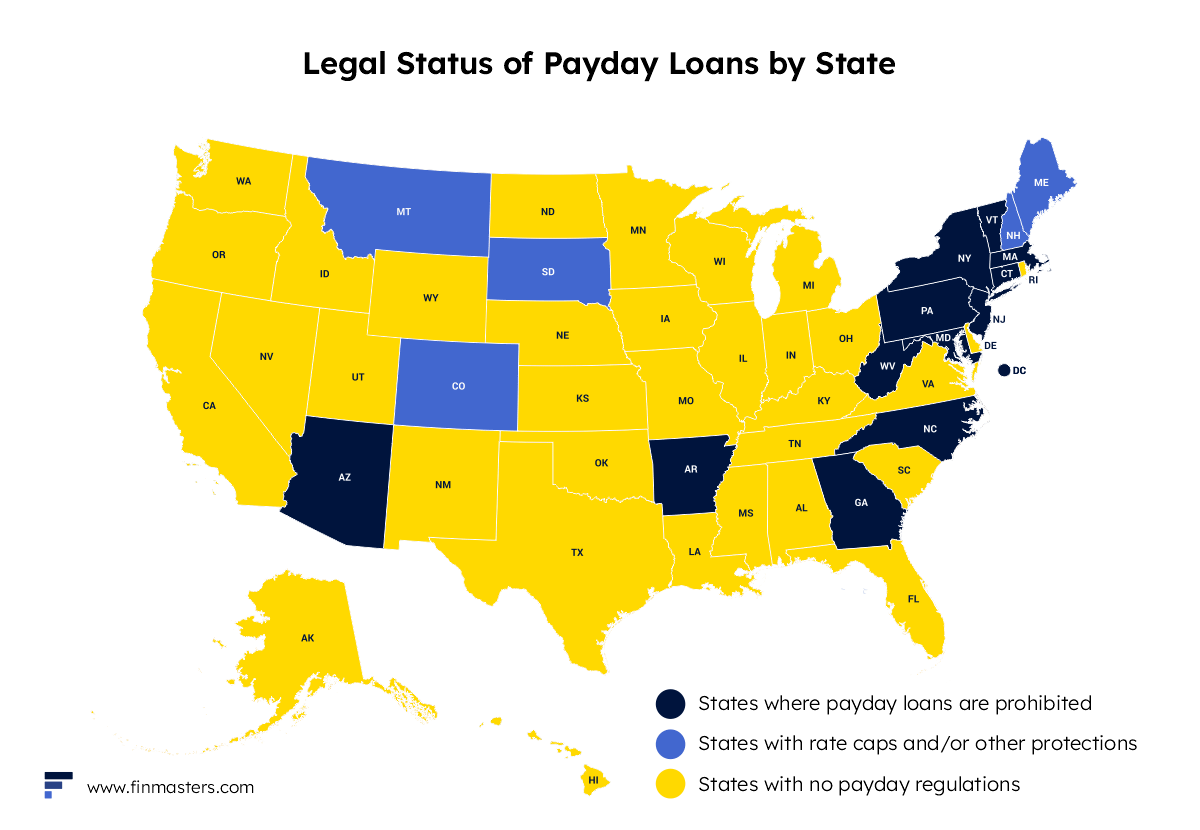
- Lebanon, Pennsylvania: Here, traditional storefront payday lending is effectively prohibited by state usury laws. Borrowers often encounter online lenders or "installment" products that mimic payday loans but operate under different regulations.
- Lebanon, Tennessee: In this jurisdiction, payday lending is legal and regulated. It is a common "quick-fix" for residents, but it remains one of the most expensive ways to borrow money.
- The Republic of Lebanon: In the national context, the collapsed banking sector means that "worth it" is measured against survival. Formal credit is scarce, and informal lenders may charge rates that make American payday loans look modest.
The Financial Mechanics of Payday Loans
To understand why these loans are generally considered a poor financial choice, one must look past the "flat fee" and examine the Annual Percentage Rate (APR). A typical payday loan involves a fee of $15 for every $100 borrowed. To a borrower in a crisis, $15 seems like a small price for $100 in immediate cash.
However, payday loans are usually due in 14 days. When you annualize that $15 fee over a 365-day year, the interest rate becomes astronomical.
Calculating the True Cost
If you borrow $500 in Lebanon, TN, with a $15 per $100 fee, you will owe $575 in two weeks.
- Interest Paid: $75
- Loan Term: 14 Days
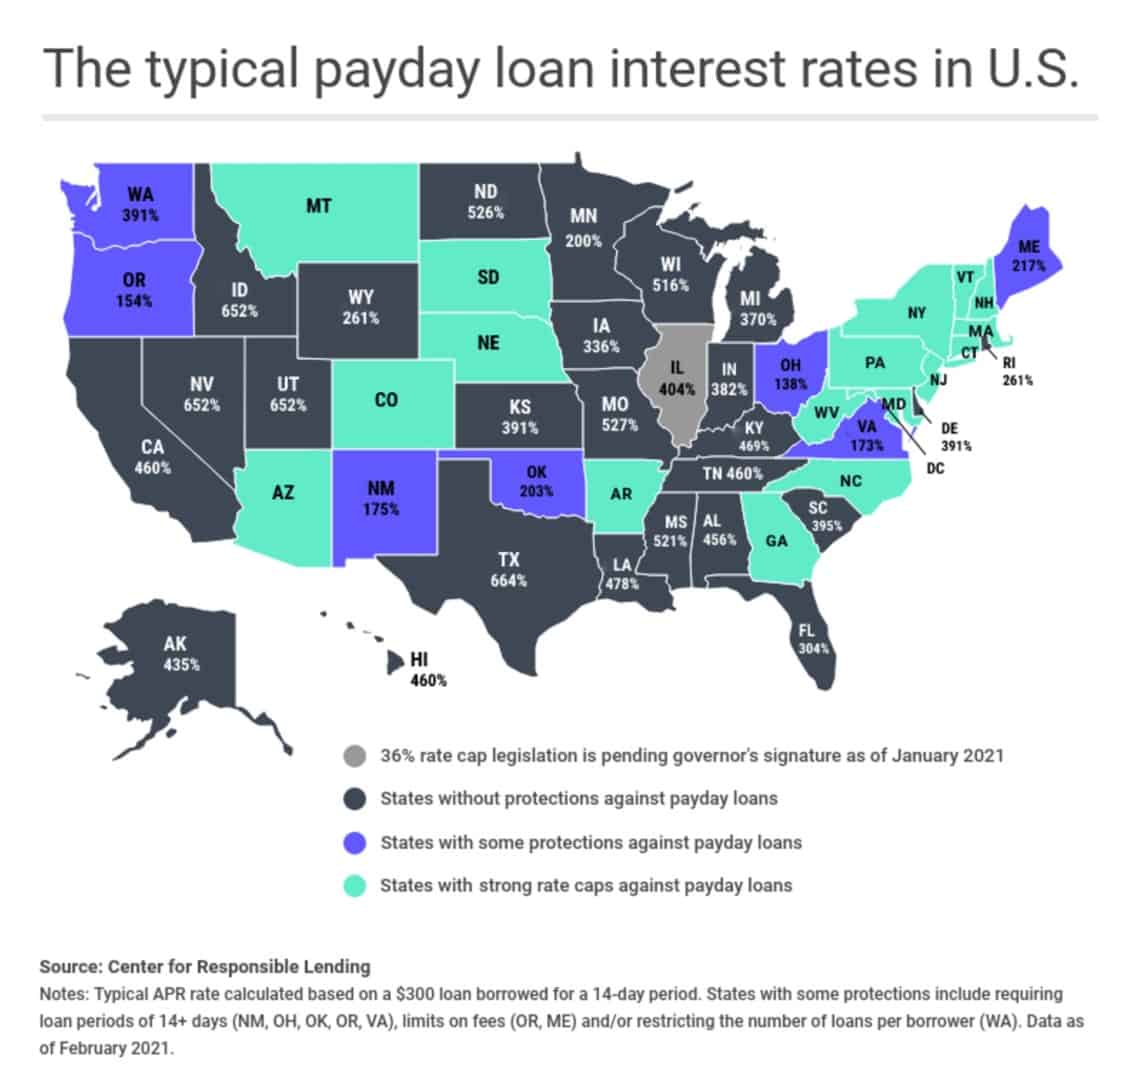
- APR Calculation: ($75 / $500) x (365 / 14) x 100 = 391% APR
In 2026, where standard personal loans from credit unions might carry an APR of 8% to 15%, paying nearly 400% is mathematically devastating to long-term wealth.
Are Payday Loans in Lebanon, Pennsylvania Worth It?
In Lebanon, PA, the answer is a firm no, primarily because the state’s Consumer Discount Company Act and the Loan Interest and Protection Law protect consumers from triple-digit interest rates. Pennsylvania is one of several states that effectively bans traditional payday lending by capping interest on small loans at roughly 6% to 24% for unlicensed/licensed lenders.
The Rise of "Pseudo-Payday" Loans in PA
Because traditional payday storefronts cannot operate in Lebanon, PA, residents often turn to online lenders who claim "tribal sovereignty" to bypass state laws. These loans are never worth it. They are legally dubious, and the Pennsylvania Department of Banking and Securities frequently issues warnings against them.
If a resident of Lebanon, PA, takes out an online loan with a 400% APR, they are paying for a product that is technically illegal in their own state. The lack of local physical recourse and the predatory nature of these online entities make them significantly more dangerous than regulated products.
Are Payday Loans in Lebanon, Tennessee Worth It?
In Lebanon, TN, payday loans (legally known as Deferred Presentment Services) are widely available along corridors like West Main Street. Because they are legal under the Tennessee Deferred Presentment Services Act, they are at least regulated, which provides some consumer protections that are absent in the online "black market."
When it Might Be "Worth It"
A payday loan in Tennessee might be "worth it" only in a narrow, life-altering emergency where:
- The alternative cost is higher: For example, if a $500 loan prevents an eviction (which could cost thousands in legal fees and moving costs) or a utility shutoff (which involves high reconnect fees).
- It is a one-time event: The borrower has a verified, guaranteed influx of cash coming in 14 days that will cover the loan and their living expenses for the following month.
Why it Usually Fails
Most borrowers in Lebanon, TN, find that once they pay back the $575 from their $2,000 paycheck, they no longer have enough money to pay their rent or buy groceries for the next month. This leads to "re-borrowing"—taking out a new loan immediately after paying off the old one. This is the Debt Trap, and once a borrower enters it, the loan is objectively not worth the financial trauma.
The Cost of Payday Loans vs. Alternatives (2026 Projections)
| Loan Type | Typical APR (2026) | Max Loan Amount | Repayment Term | Best For |
|---|---|---|---|---|
| Payday Loan (TN) | 390% - 460% | $500 | 14 - 31 Days | Extreme Emergency |
| Credit Card Cash Advance | 24% - 36% | Varies by Limit | Monthly | Small Gaps |
| PAL (Credit Union) | 28% | $200 - $1,000 | 1 - 6 Months | Controlled Borrowing |
| Earned Wage Access App | 0% - 15% (Tips/Fees) | $100 - $500 | Next Payday | Avoiding Interest |
| Personal Loan | 7% - 18% | $2,000+ | 12 - 60 Months | Major Expenses |
The Global Perspective: Payday Lending in the Republic of Lebanon
If the query refers to the country of Lebanon, the concept of "worth it" is fundamentally different. As of 2026, the Lebanese economy continues to struggle with the aftermath of the 2019 financial collapse. Traditional banking credit is largely frozen, and the Lebanese Pound (LBP) has seen massive fluctuations.
The Reality of Small Loans in a Crisis Economy
In the country of Lebanon, "payday loans" are usually informal arrangements. A borrower might borrow USD or "Fresh" LBP from a local lender or a money exchange office.
- The Risk: Since there is little to no regulatory oversight in the informal lending market, interest rates are "market-driven," which in a crisis means they can be 10% to 20% per month.
- The Verdict: These loans are almost never worth it unless they are used for productive purposes (e.g., buying stock for a small business) or medical emergencies. Borrowing to cover consumption in a high-inflation environment leads to a permanent loss of purchasing power.
Practical Alternatives in Lebanon (PA & TN)
Before considering a payday loan, residents should exhaust these 2026-era financial tools:
1. Earned Wage Access (EWA) Apps
Apps like Earnin, Dave, or Brigit have become mainstream by 2026. These allow you to "unlock" wages you have already earned but have not yet been paid. While they often charge a small monthly subscription or an optional "tip," the effective cost is a fraction of a payday loan.
2. Credit Union "PALs"
Lanco Federal Credit Union (near Lebanon, PA) or US Community Credit Union (near Lebanon, TN) often offer Payday Alternative Loans (PALs). These are specifically designed to provide small-dollar credit at interest rates capped by federal law at 28%. They also provide a longer repayment period (up to six months), making the monthly hit to your budget manageable.
3. Local Community Action Partnerships
In Lebanon, PA, organizations like Community Action Partnership (CAP) can sometimes provide emergency assistance for utilities or rent. In Lebanon, TN, local churches and the Mid-Cumberland Community Action Agency offer similar safety nets. Using these resources is always better than taking on high-interest debt.
4. 2026 Credit Card Features
By 2026, many major credit card issuers have integrated "Plan It" or "My Chase Plan" features that allow users to convert a purchase into a fixed-fee monthly installment plan. This is significantly cheaper than a payday loan or even a standard cash advance.
The Long-Term Impact on Credit Scores
One of the most misunderstood aspects of payday loans in Lebanon is their impact on credit. Most payday lenders do not report your on-time payments to the major credit bureaus (Equifax, Experian, TransUnion). This means taking the loan does not help you build credit.
However, if you fail to pay back the loan, the lender will likely sell the debt to a collection agency. Collections agencies do report to credit bureaus. Therefore, a payday loan has "all risk and no reward" for your credit profile. In a 2026 economy where credit scores determine insurance premiums and even job eligibility in some sectors, this risk is substantial.
How to Apply if You Must (Lebanon, TN Only)
If you have weighed all options and determined a payday loan in Lebanon, TN, is your only path forward, ensure you follow these steps to minimize damage:
- Verify the License: Ensure the storefront is licensed by the Tennessee Department of Financial Institutions.
- Bring Documentation: You will typically need a government-issued ID, your most recent pay stub, and a blank check or bank statement.
- Borrow the Minimum: If you need $200, do not borrow the $500 maximum just because it is offered.
- Create a Repayment Plan: Before you leave the store with the cash, identify exactly which expense you will cut from your next paycheck to ensure the loan is paid in full without needing to re-borrow.
Expert Guidance: Breaking the Cycle
If you are already trapped in a payday loan cycle in Lebanon, do not panic. In Tennessee, you may be eligible for an Extended Payment Plan (EPP). State law often allows borrowers to repay their loan in installments rather than a lump sum if they request it before the due date.
In Pennsylvania, because the loans are often from out-of-state or online entities, you should contact the Pennsylvania Office of Attorney General. They can often help negotiate a settlement or determine if the loan is even legally enforceable under PA's strict usury limits.
FAQ
Are payday loans legal in Lebanon, PA?
No, traditional storefront payday loans are not legal in Pennsylvania. The state’s interest rate caps (Consumer Discount Company Act) prevent lenders from charging the high APRs typically associated with payday lending. Any entity offering such loans in Lebanon, PA, is likely an unlicensed online lender.
What is the maximum I can borrow in Lebanon, TN?
Under Tennessee law, the maximum amount for a payday loan (deferred presentment) is $500. This includes the fees. For example, if the fee is $15 per $100, you would receive $425 in cash and owe $500, or receive $500 and owe $575, depending on the lender's structure and your eligibility.
Will a payday loan in Lebanon help my credit score?
Almost certainly not. Most payday lenders do not report positive payment history to credit bureaus. They only report to specialized databases (like Teletrack) that other payday lenders use. However, a default will likely end up on your standard credit report via a collections agency.
What happens if I can’t pay back a payday loan in Lebanon?
In Tennessee, the lender can attempt to deposit your check or debit your account. If it bounces, you may owe additional NSF fees. While you cannot be arrested for simply failing to pay a debt, the lender can sue you in civil court to garnish your wages. In Pennsylvania, because the loans are often illegal, the lender's ability to sue is severely limited, but they may still engage in aggressive (and sometimes illegal) collection tactics.
Are there "Payday Loan" stores in the country of Lebanon?
There are no Western-style "Payday Loan" franchises in the Republic of Lebanon. Financial assistance is primarily handled through commercial banks (currently limited), micro-finance NGOs like Al-Majmoua, or informal community lenders.
Final Verdict: Is it Worth It?
For the vast majority of people in Lebanon (PA, TN, or abroad), payday loans are not worth it. They are a high-cost "band-aid" for a deep financial wound. The 390%+ APR creates a mathematical hurdle that most household budgets cannot clear in a single two-week period.
If you are in Lebanon, PA, seek credit union alternatives or state assistance. If you are in Lebanon, TN, use the legal protections of an Extended Payment Plan if you fall behind. If you are in the Republic of Lebanon, prioritize NGO-backed micro-loans over informal high-interest lenders. In all cases, the "speed" of the cash is rarely worth the long-term cost of the debt.