Amica Mutual Insurance Company is a mutual insurer, meaning it is owned by its policyholders rather than outside shareholders. Because of this structure, eligible whole life insurance policyholders may receive annual dividends based on the company’s financial performance. While these dividends are not guaranteed, Amica has maintained a long-standing practice of distributing them to participating policyholders, reflecting its conservative underwriting approach and commitment to long-term financial stability.
The Mechanism of Dividends in Mutual Insurance
To understand the dividend history of an Amica whole life insurance policy, it is first necessary to grasp how mutual insurance companies operate. Unlike stock insurance companies, which seek to generate profit for external investors, a mutual company functions with the primary goal of providing insurance protection to its members at an equitable cost.
When an insurer collects premiums, it allocates those funds to pay future claims, cover administrative expenses, and maintain a reserve surplus. If the company performs better than expected—due to lower-than-anticipated mortality rates among policyholders, prudent investment returns, or efficient operational management—the insurer may find itself with a surplus of funds. The company’s board of directors may choose to distribute a portion of this excess back to policyholders in the form of a dividend.
In the context of Amica, dividends are considered a return of premium rather than taxable investment income. This distinction is crucial for policyholders evaluating the internal rate of return on their life insurance assets. Because these funds are viewed as a refund of previously paid premiums, they are generally not taxable unless the total dividends received exceed the total premiums paid into the policy.
Evaluating Amica’s Financial Stability
The history of dividend payments at any insurance company is inextricably linked to its financial strength. Amica is well-known in the industry for its conservative fiscal management. As a mutual company, it prioritizes long-term solvency over short-term aggressive growth. This philosophy is reflected in its rating agency profiles, which consistently highlight the company's superior capital position.
When assessing the reliability of dividend payments, prospective and current policyholders look to the company’s "A.M. Best" rating and other financial strength indicators. A company with high financial ratings is generally better positioned to withstand economic volatility, ensuring that it can continue to honor its obligations to policyholders, including the potential for future dividend declarations.
While historical performance is never a guarantee of future results, Amica’s status as a mutual insurer provides a structural incentive to maintain dividend payments as part of the overall value proposition to its member-owners. The consistency of these payments is often a primary factor for individuals who prioritize the cash value growth and death benefit protection provided by whole life insurance.
Factors Influencing Dividend Declarations
Dividend scales are not static; they are adjusted annually by the insurer based on three primary drivers: investment returns, mortality experience, and expense management.
- Investment Returns: A significant portion of a life insurance company’s assets is invested in high-grade bonds and other conservative financial instruments. The interest earned on these portfolios forms a large part of the surplus that can be distributed as dividends. If interest rates rise or the company’s portfolio yields improve, the potential for higher dividends generally increases. Conversely, prolonged periods of low interest rates can pressure the dividend scale.
- Mortality Experience: Life insurance companies calculate premiums based on actuarial expectations of life expectancy. If the policyholder pool experiences lower mortality than forecasted—meaning fewer death claims are paid out than the company anticipated—this creates a "mortality gain." This surplus contributes to the dividend pool.
- Expense Management: The cost of doing business, including underwriting, marketing, and policy administration, impacts the bottom line. Amica’s reputation for internal efficiency and customer retention contributes to lower operational costs, which helps preserve the surplus available for distribution.
Historical Perspective and Market Conditions
Throughout the early 2020s and into 2026, the insurance industry faced shifting economic landscapes, including fluctuating interest rates and evolving mortality data. Amica’s historical approach has been to maintain a steady, sustainable dividend scale rather than pursuing volatile, short-term increases.
Policyholders comparing Amica to other carriers should note that "dividend history" refers to the insurer's overall practice of paying dividends, not a fixed percentage applied to every policy equally. The specific dividend credited to a policy is determined by the policy’s age, the cash value amount, and the specific terms of the contract. Older policies often see different dividend performance compared to new policies due to the compounding effect of the cash value growth over time.
Strategic Uses of Dividends
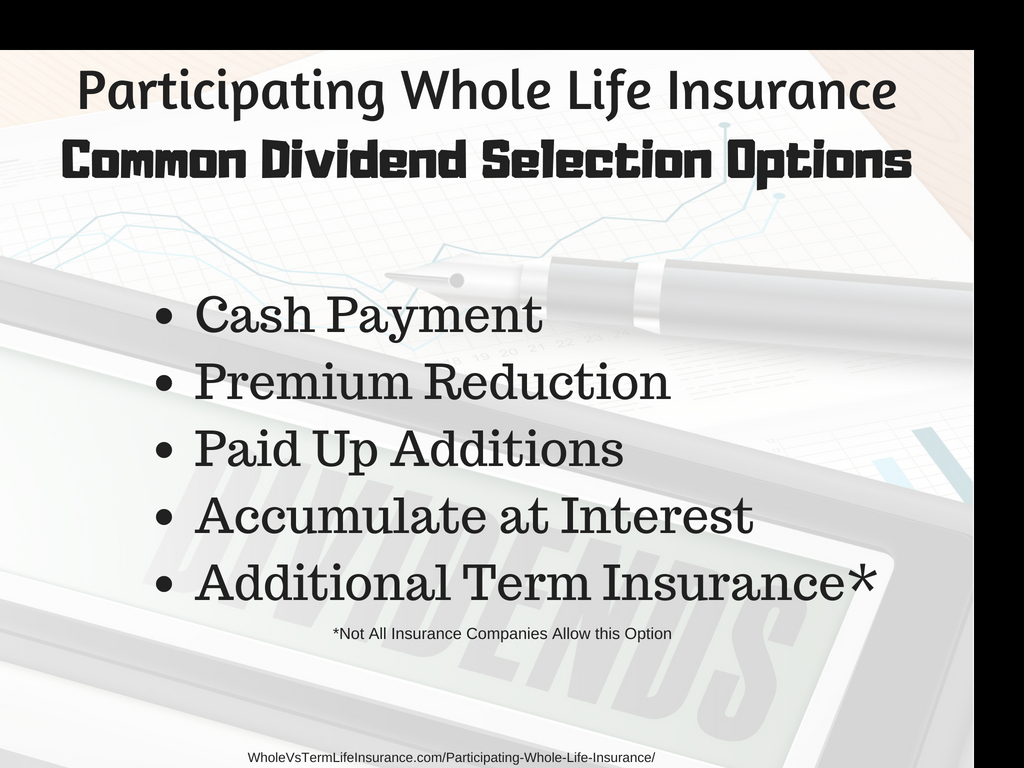
For policyholders, dividends are not merely cash payouts; they are flexible financial tools. When an Amica policyholder receives a dividend, they typically have several options for how those funds are applied, each with different long-term implications:
- Premium Reduction: Dividends can be used to lower the out-of-pocket cost of the policy’s annual premium. This is a common choice for policyholders who want to maintain coverage while minimizing ongoing expenses.
- Paid-Up Additions (PUAs): This is often considered the most powerful use of dividends. The dividend is used to purchase a small amount of additional permanent life insurance. This increases the total death benefit and simultaneously grows the cash value of the policy. Because these additions are paid-up, they also qualify for future dividends, creating a compounding effect that accelerates the growth of the policy’s total value.
- Cash Withdrawal: Policyholders can choose to receive the dividend as a cash payment. While this provides immediate liquidity, it does not contribute to the compounding growth of the policy’s cash value.
- Accumulation at Interest: The dividend can be left with the insurance company to earn interest at a rate set by the insurer. This acts similarly to a high-yield savings account within the policy structure.
Comparison of Dividend-Paying Mechanisms
| Option | Primary Benefit | Impact on Policy Value |
|---|---|---|
| Paid-Up Additions | Compounding Growth | Increases both death benefit and cash value |
| Premium Reduction | Cash Flow | Reduces the net cost of the insurance |
| Cash Withdrawal | Immediate Liquidity | No impact on long-term policy growth |
| Accumulation at Interest | Liquidity & Growth | Earns interest based on company rates |
Prerequisites for Dividend Participation
Not every policy issued by Amica is eligible for dividends. Dividends are typically a feature of "participating" whole life insurance policies. A "non-participating" policy, by contrast, is one where the premium and benefit amounts are fixed with no expectation of additional payouts.
Before expecting dividends, a policyholder should verify their policy contract. Furthermore, dividend distributions are discretionary. Even if a policy is participating, the company is not legally obligated to pay a dividend in a given year. The dividend declaration is an action taken by the Board of Directors based on the annual financial review of the company.
Common Misconceptions
One of the most frequent errors in understanding dividend history is the expectation that dividends are interest payments. They are not. Investors often confuse the "dividend interest rate" used by insurance companies with a bank's APY. It is vital to remember that an insurance dividend is a distribution of surplus funds. If an insurance company markets a "dividend interest rate," it is an internal metric used to calculate the dividend allocation, not a guarantee of a direct percentage return on the premiums paid.
Another common mistake is comparing the dividend history of a large, century-old mutual company with that of a smaller, newer stock company. The scale, operational costs, and risk tolerance of these entities are vastly different, making a direct numerical comparison of their dividend scales inaccurate.
Navigating Policy Statements
To track the performance of a specific policy, the policyholder should regularly review their annual statements. These documents provide clarity on:
- Current Cash Value: The total amount accumulated in the policy.
- Dividend Applied: The exact amount credited to the policy for the current year.
- Dividend Option Selection: Which of the aforementioned methods (e.g., Paid-Up Additions) is currently active on the account.
If a policyholder finds that their dividend performance is not meeting their expectations, they should consult with their insurance agent to ensure that the chosen dividend option is still aligned with their long-term financial goals. For example, a policyholder who previously chose "Cash Withdrawal" might find that switching to "Paid-Up Additions" better serves their goal of increasing their death benefit as they move through different life stages.
Practical Advice for Policyholders
When evaluating Amica’s whole life insurance, consider the following steps:
- Review the Illustration: Always ask for a current ledger or illustration when making decisions about your policy. This document will show projected growth and historical dividend impacts.
- Understand the "Non-Guaranteed" Nature: Always build your financial plan around the guaranteed elements of the policy—the fixed death benefit and the minimum guaranteed cash value—rather than relying on dividends to meet essential needs. Think of dividends as an added benefit to the core policy structure.
- Check Financial Strength: Periodically check Amica’s rating from agencies such as A.M. Best. As long as the company maintains its high financial standing, the likelihood of stable dividend declarations remains strong.
If you are currently researching Amica and need to determine how a specific policy type performed, you should contact their customer service or a licensed representative. They can provide specific information regarding the dividend scales for different generations of policies, as older, legacy policies may operate under different dividend structures than those being issued in 2026.
Disclaimer: This information is for educational purposes and does not constitute financial, legal, or tax advice. Life insurance dividends are not guaranteed and are subject to the financial performance of the issuing company. Always consult with a qualified financial advisor before making decisions regarding your life insurance coverage or investment strategies.
Frequently Asked Questions
Are Amica dividends guaranteed? No, dividends are not guaranteed. They are declared annually by the Board of Directors based on the company’s financial surplus, which is influenced by investment income, mortality experience, and operational expenses.
How does Amica determine the dividend amount for my policy? The dividend amount is determined by the contribution of your specific policy to the company’s surplus. Factors include the type of policy, the duration it has been in force, and the current dividend scale approved by the company's board for that specific block of policies.
Can I change my dividend option after the policy is in effect? Yes, most whole life insurance policies allow you to change your dividend option—such as switching from cash payments to paid-up additions—at any time. You should contact your Amica representative to request this change.
Does receiving a dividend affect the death benefit of my policy? If you choose the "Paid-Up Additions" option, your death benefit will increase over time as dividends are used to purchase extra coverage. If you take dividends as cash or use them to reduce premiums, the death benefit typically remains stable, depending on the terms of your specific contract.
Are life insurance dividends taxable? Generally, dividends are considered a return of excess premium and are not taxable up to the total amount of premiums paid into the policy. Once total dividends exceed the premiums paid, the excess may be subject to taxation. You should consult with a tax professional regarding your specific situation.