Athene Annuity and Life Company, often referred to by consumers as Athenean, is a leading provider of retirement solutions that primarily focuses on fixed and fixed indexed annuities. While the company retains "Life" in its name and manages legacy life insurance blocks, it does not currently issue new individual term or whole life insurance policies, instead specializing in products designed for asset accumulation and death benefits through annuity structures.
The landscape of the insurance industry has shifted significantly over the last decade, and Athene (often colloquially searched for as Athenean) stands as a prime example of a company that has narrowed its focus to excel in a specific niche. For consumers in 2026, understanding what "Athenean life insurance" actually entails requires a look at both the company’s history and its current product lineup, which leans heavily toward retirement security rather than traditional mortality-based insurance.
Understanding the "Athenean" Identity and Brand History
To understand Athene's current offerings, consumers must first navigate the brand's evolution. The name "Athene" is derived from the Greek goddess Athena, symbolizing wisdom. In the consumer market, the term "Athenean" is frequently used by those seeking the company's services, though the official corporate entity is Athene Holding Ltd., a subsidiary of Apollo Global Management.
Athene rose to prominence through the acquisition of several large insurance blocks, most notably the U.S. life and annuity operations of Aviva in 2013. This acquisition gave Athene a massive footprint in the life insurance sector. However, in a strategic pivot that concluded a few years later, Athene sold a substantial portion of its individual life insurance business to Accordia Life (a subsidiary of Global Atlantic Financial Group).
As of 2026, if you are a consumer looking for "Athenean life insurance," you likely fall into one of three categories:
- Legacy Policyholders: You hold an older life insurance policy originally issued by Aviva or Athene that is still being serviced or was part of the Accordia transfer.
- Institutional Clients: You are part of a group life or pension risk transfer (PRT) where Athene provides the underlying financial backing.
- Annuity Seekers: You are looking for a product that provides a "death benefit"—a core feature of life insurance—but through a fixed indexed annuity (FIA) structure.
Life Insurance vs. Annuities: The Athene Approach
The most common point of confusion for consumers in 2026 is the distinction between a traditional life insurance policy and an annuity with a death benefit. Athene specializes in the latter.
Traditional Life Insurance
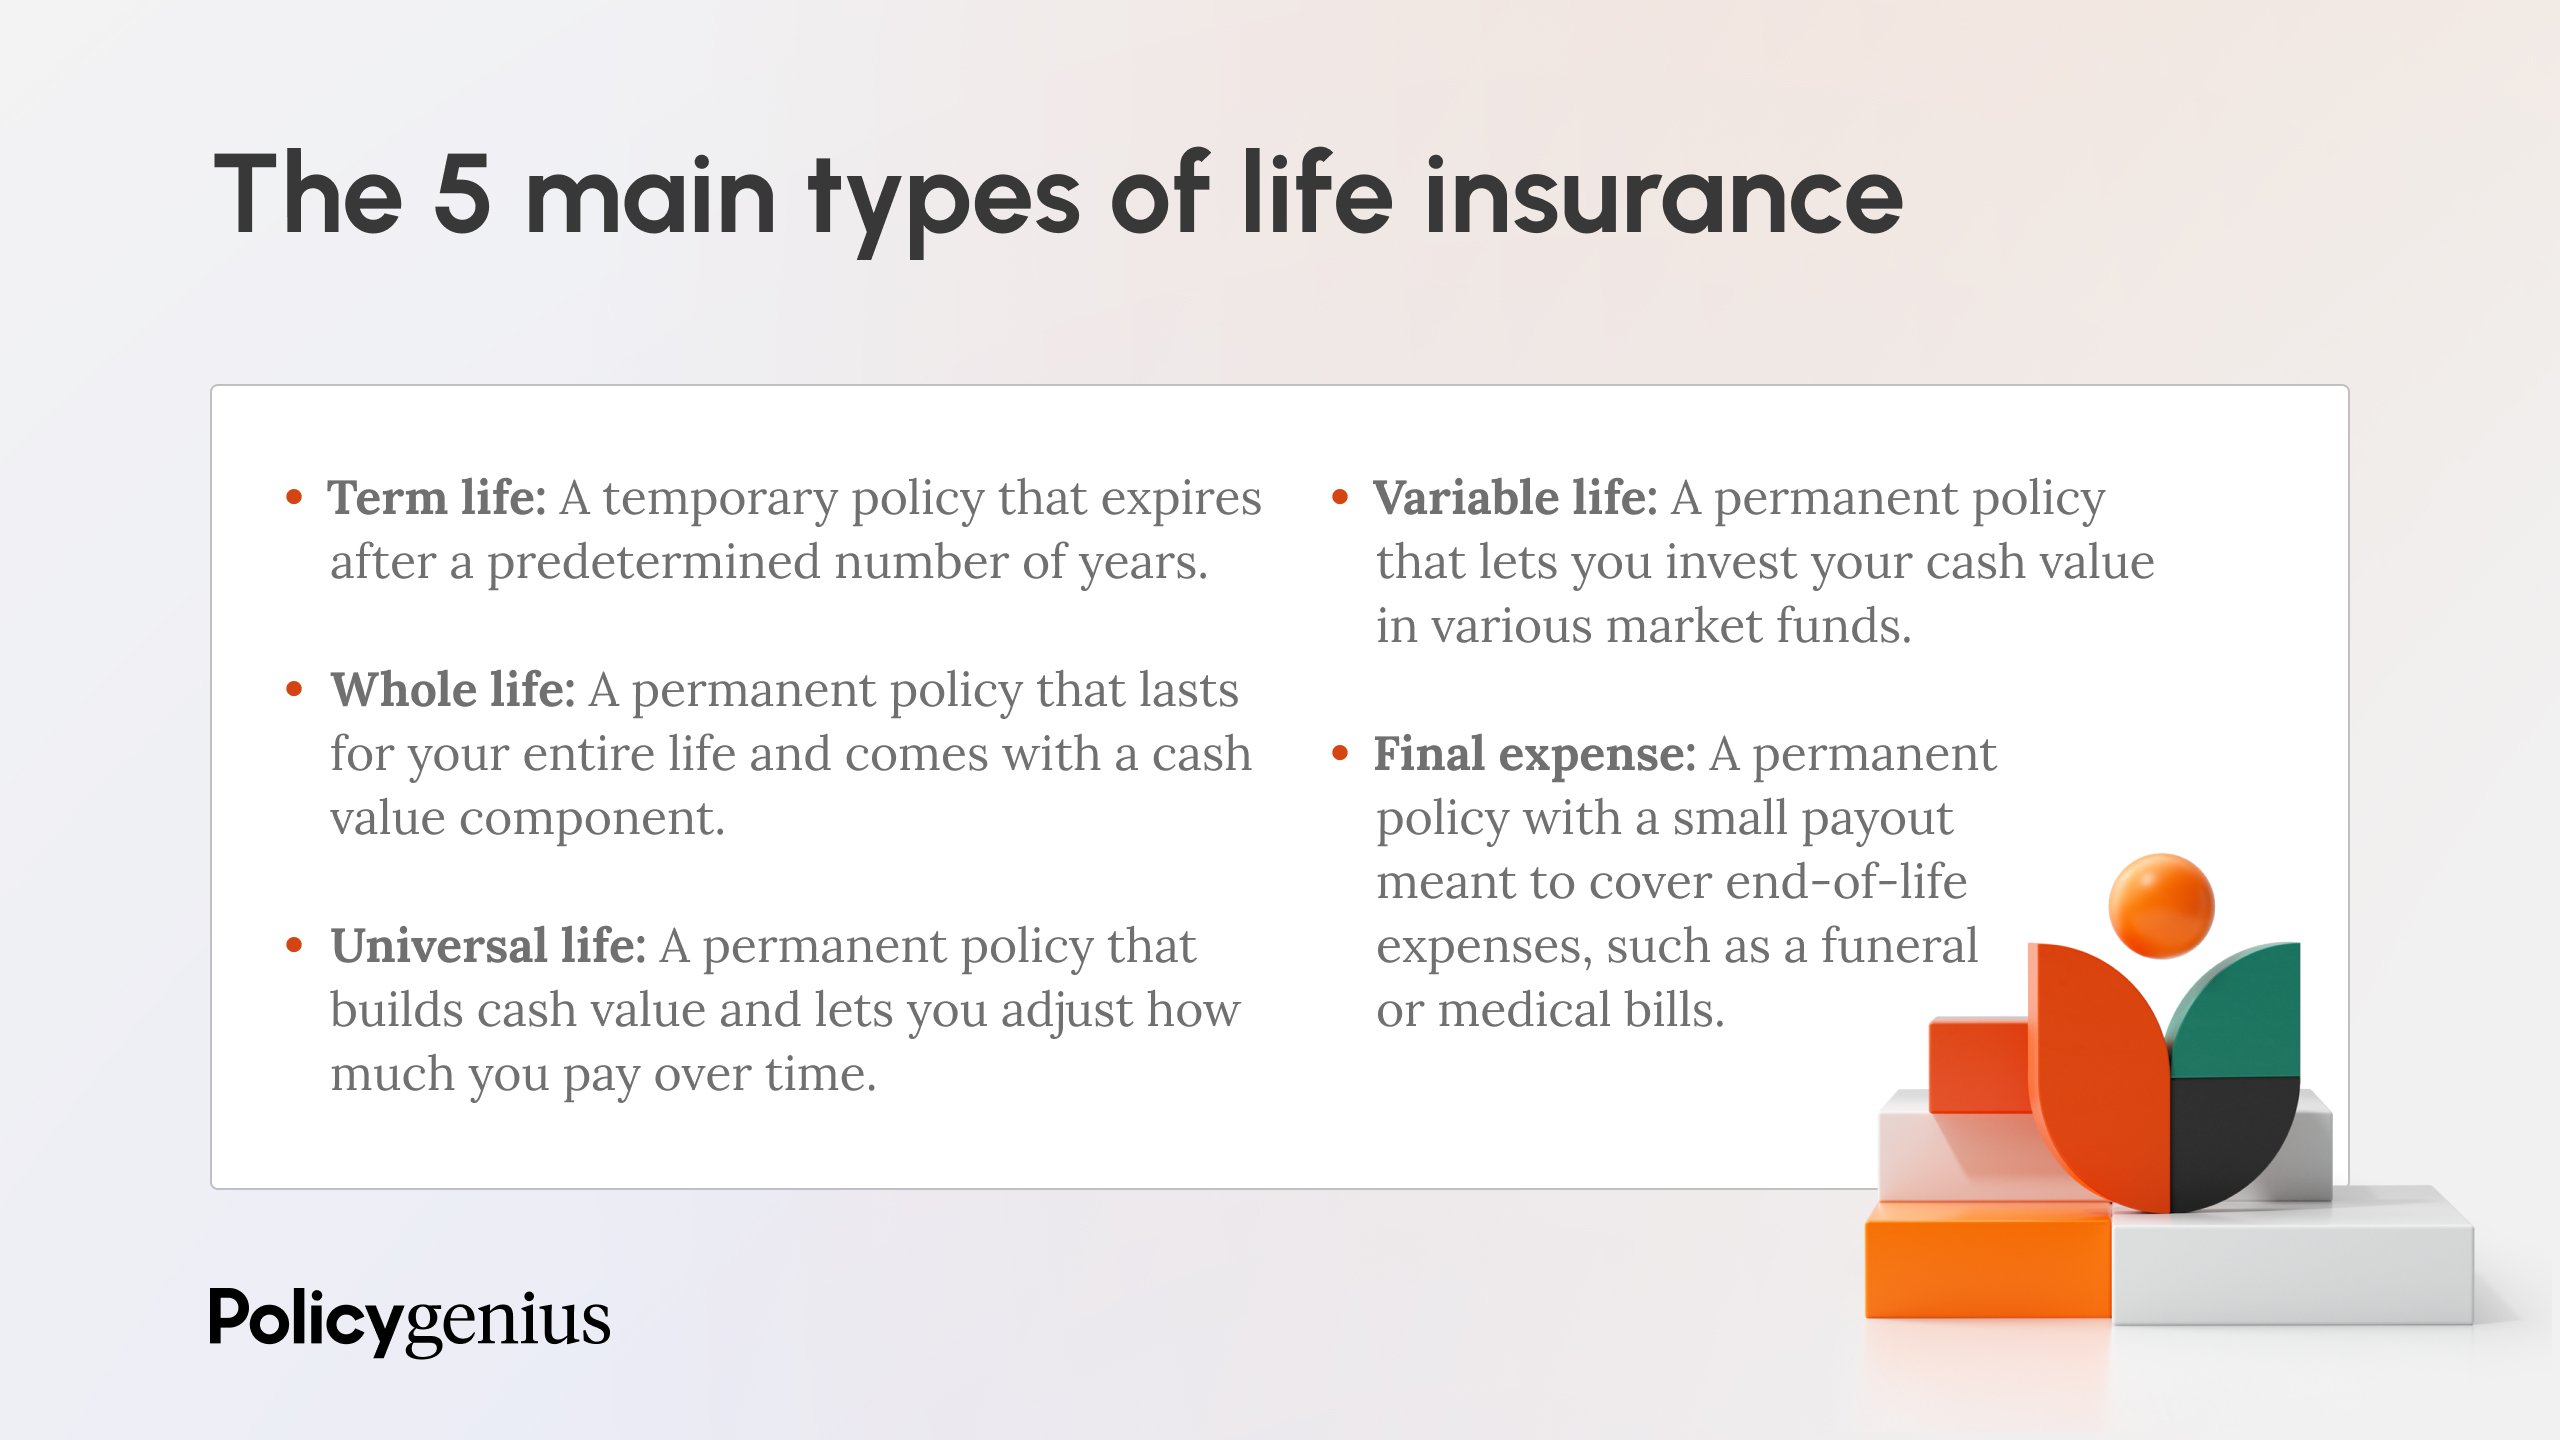
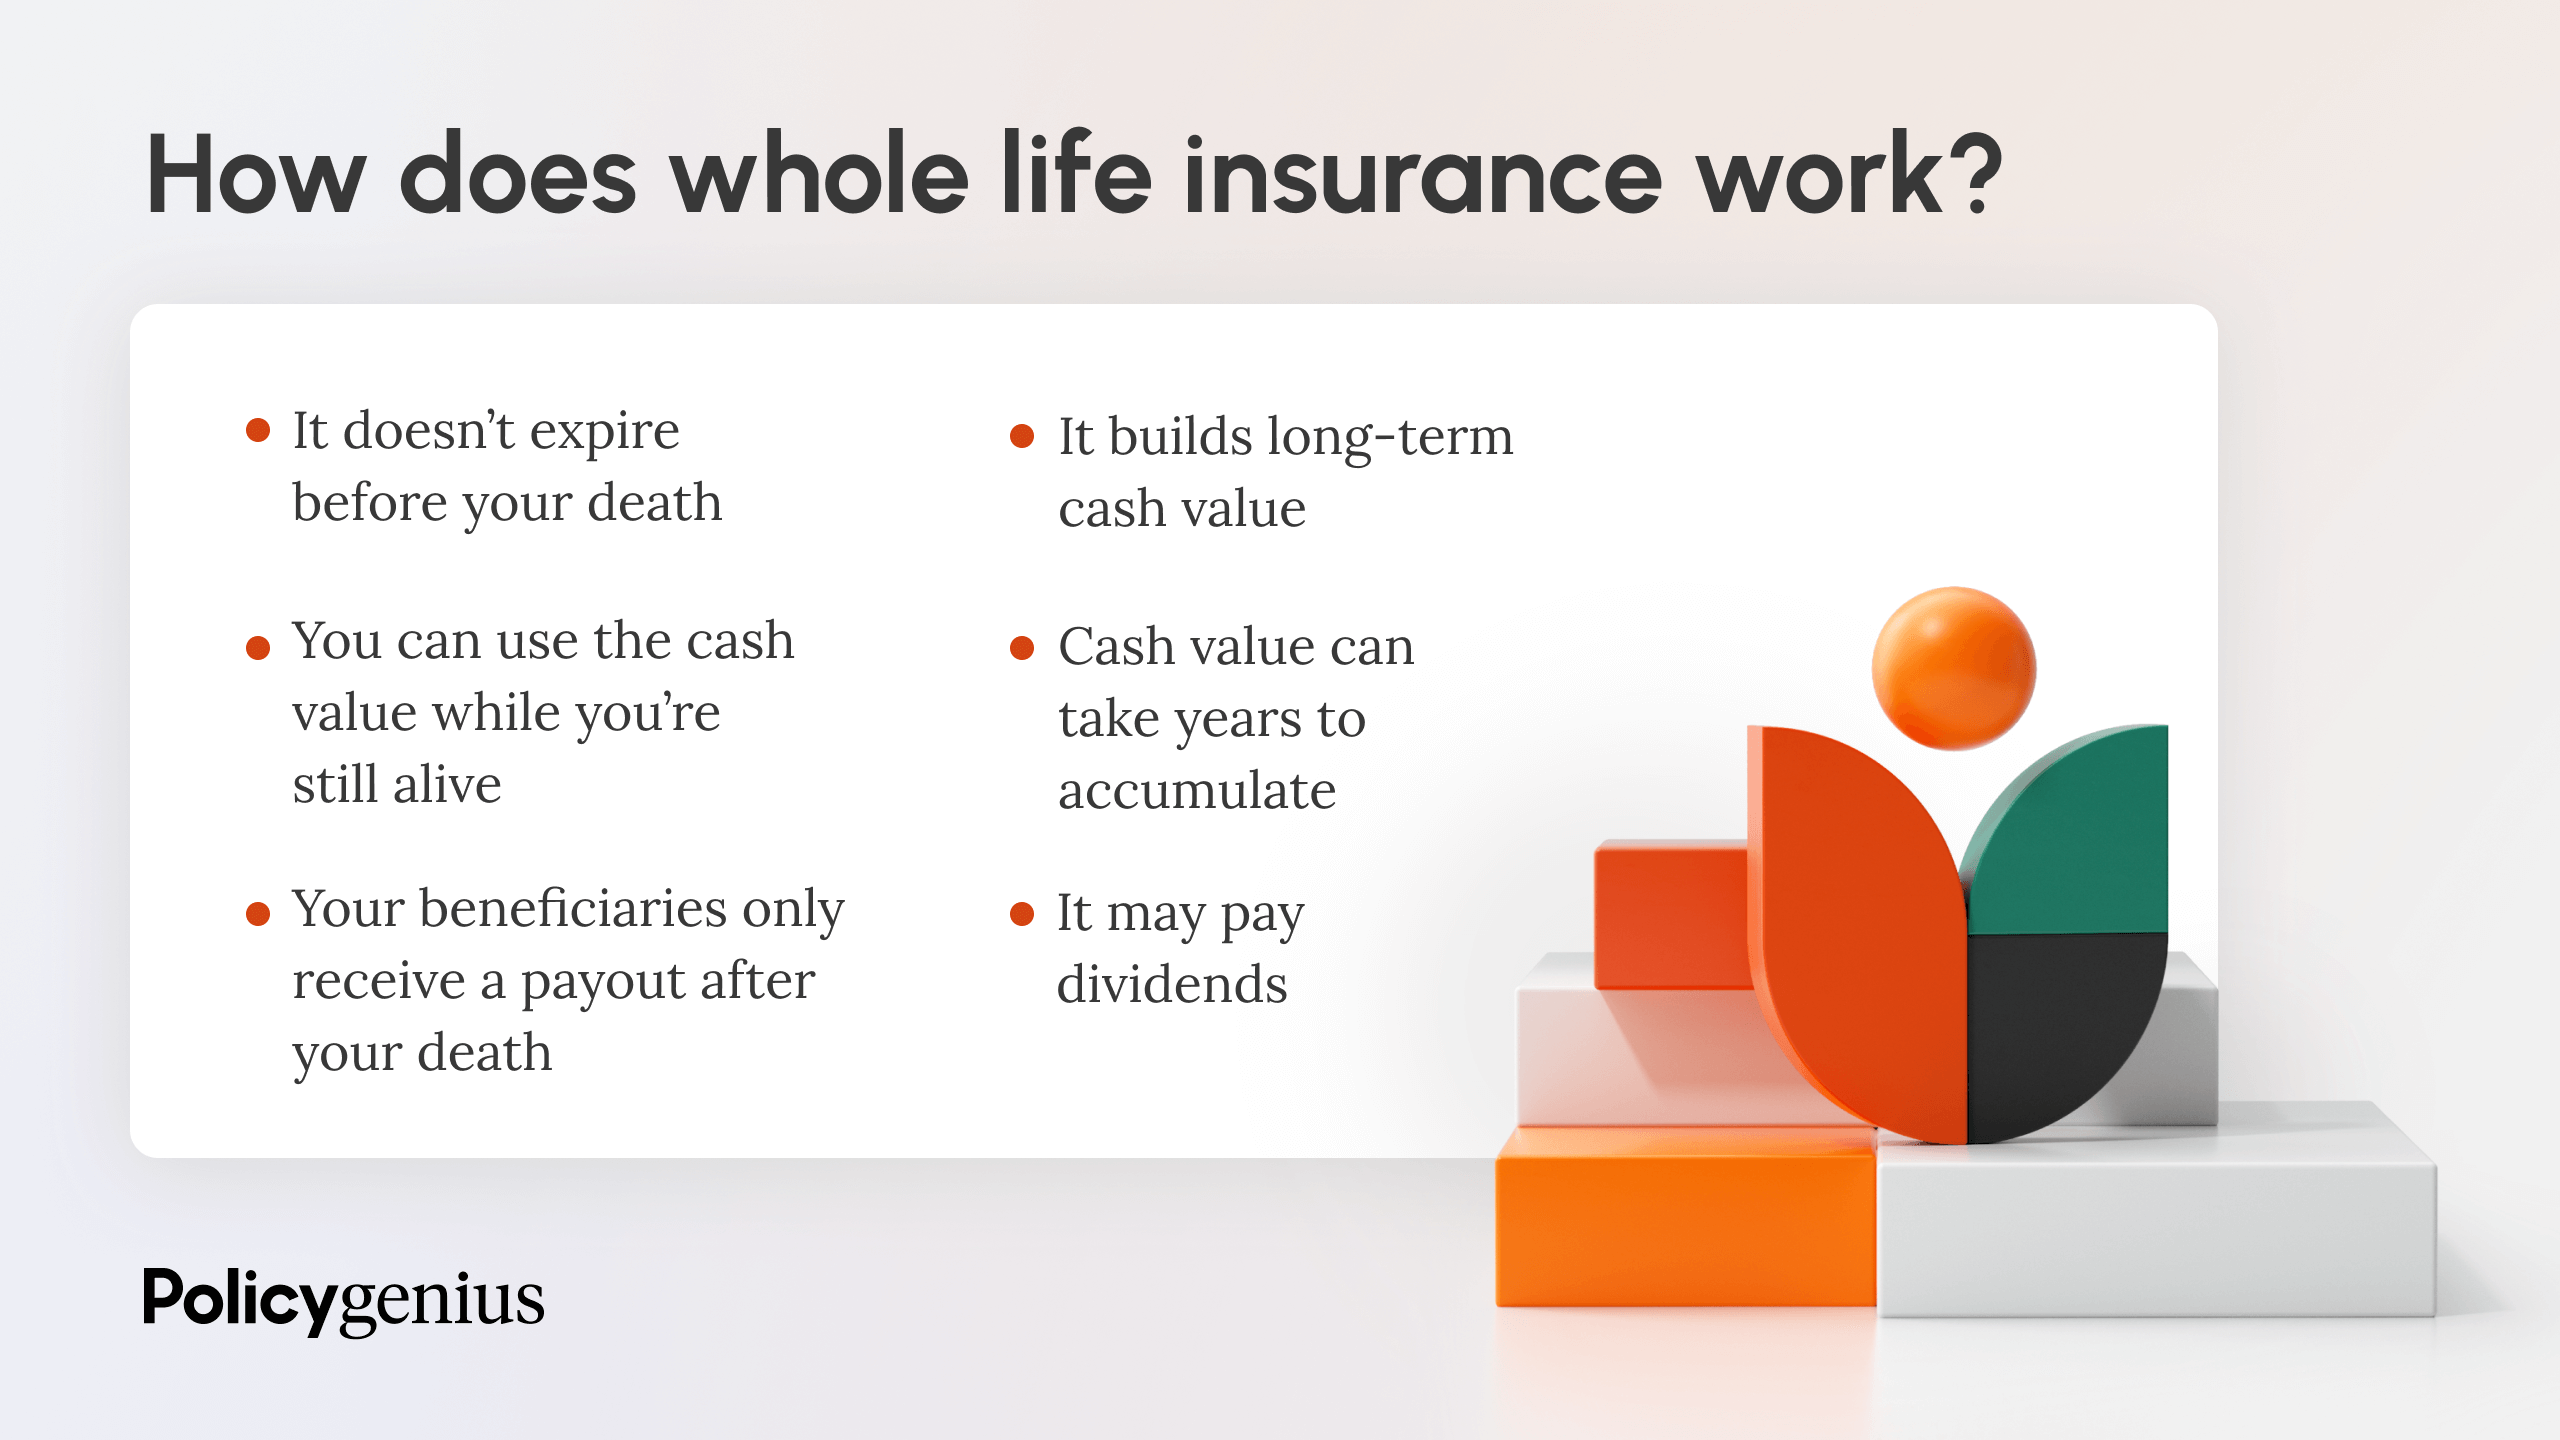
Traditional life insurance (Term, Whole, or Universal Life) is designed primarily to provide a tax-free lump sum to beneficiaries upon the death of the insured. You pay a premium, and the insurance company takes on the "mortality risk."
Athene’s Retirement-Centric "Life" Solutions
Athene’s primary consumer products are fixed indexed annuities. While these are retirement savings vehicles, they carry significant "life insurance-like" qualities. Most Athene annuities include a death benefit provision. If the owner or annuitant dies before the contract is annuitized (turned into a stream of payments), the accumulated value of the account is paid out to the named beneficiaries.
For many consumers, an annuity serves as a "hybrid" solution. It protects against the risk of outliving one’s money (longevity risk) while ensuring that if the individual dies early, the principal and earned interest are not lost but are passed on as an inheritance.
Managing Legacy Athenean Life Insurance Policies
If you already own a life insurance policy labeled "Athene" or "Athenean," it is likely a legacy product. Managing these policies in 2026 requires understanding the servicing structure.
When Athene transitioned its individual life block to Accordia Life, a "reinsurance" and "administration" agreement was established. This means that while the paper might say Athene, the daily management, premium collection, and claims processing are often handled by Accordia or a third-party administrator.
How to Verify Your Policy Status
- Check the Policy Number: Most legacy Athene policies have specific prefixes that indicate their origin (e.g., Aviva-originated policies).
- Locate the Administrator: Visit the Athene customer service portal to determine if your policy is managed in-house or through Accordia Life.
- Review the Death Benefit: Legacy universal life policies from the Athene/Aviva era often have "cash value" components. In 2026, it is vital to review your "annual statement" to ensure the cost of insurance (COI) isn't depleting your cash value, a common issue with older universal life products.
The Role of Death Benefits in Athene Annuities
For new consumers in 2026, the "life insurance" aspect of Athene is found within their annuity riders. A rider is an optional add-on that modifies the base contract.
Enhanced Death Benefit Riders
Many Athene products, such as the Athene Ascent or Athene Agility series, offer optional riders that can increase the amount of money left to heirs. These riders often guarantee that the death benefit will grow by a certain percentage (a "rollup rate") regardless of market performance.
For example, if a consumer invests $200,000 into a fixed indexed annuity with an enhanced death benefit rider, the rider might guarantee a 5% simple interest growth on the death benefit base. If the investor dies ten years later, the beneficiaries might receive a payout significantly higher than the actual account value, provided the conditions of the rider are met.
Tax Implications for Consumers
It is crucial to note that unlike traditional life insurance proceeds, which are generally received income tax-free under Internal Revenue Code Section 101(a), the death benefit from an annuity is handled differently. The gain in the annuity (the amount above the original investment) is typically taxed as ordinary income to the beneficiary. This is a critical distinction for consumers comparing Athene products to traditional life insurance.
Athene’s Financial Strength and Stability in 2026
When choosing a company to manage a life insurance legacy or a retirement annuity, the financial "weather-worthiness" of the institution is paramount. Athene is consistently ranked highly by independent credit rating agencies. These ratings reflect the company’s ability to meet its long-term obligations to policyholders.
| Rating Agency | 2026 Rating | Meaning |
|---|---|---|
| A.M. Best | A+ (Superior) | Extremely strong ability to meet ongoing insurance obligations. |
| S&P Global | A+ (Strong) | Very strong capacity to meet financial commitments. |
| Fitch Ratings | A+ (Strong) | High credit quality and low default risk. |
| Moody’s | A1 (Good) | Low credit risk; high ability to pay back-end claims. |
These ratings are particularly important because Athene’s business model involves managing high volumes of institutional liabilities. As a consumer, these scores provide peace of mind that the "life" component of your contract—the promise to pay your beneficiaries—is backed by a solvent and robust balance sheet.
Key Considerations for Consumers
Before committing to an Athene product as a life insurance alternative, consumers should evaluate several factors that define the user experience and financial outcome.
1. Liquidity and Surrender Charges
Unlike a term life insurance policy, which you can cancel at any time (though you get no money back), Athene's annuity products are long-term commitments. Most have "surrender periods" lasting 5, 7, or 10 years. If you attempt to withdraw more than the "free withdrawal" amount (typically 10% per year) during this period, you will face significant penalties.
2. Market Participation vs. Protection
Athene’s fixed indexed annuities allow consumers to earn interest based on the movement of a market index (like the S&P 500) without actually being invested in the market. This means the "life insurance" value (the death benefit) is protected from market crashes. However, your growth is often "capped" or subject to a "participation rate," meaning you won't capture the full upside of a bull market.
3. Beneficiary Designations
Because Athene products are often used as wealth transfer tools, keeping beneficiary designations current is vital. In 2026, Athene allows for "per stirpes" designations, which ensures that if a primary beneficiary predeceases the policyholder, the benefit passes down to that beneficiary's children rather than being divided among other surviving primary beneficiaries.
How to Apply or Access Athene Services
Athene does not sell directly to consumers through a "buy now" website. Instead, they operate through a network of independent financial advisors, insurance agents, and bank partners.
Steps for New Consumers:
- Consult an Independent Agent: Seek an advisor who is "Athene-contracted." They can provide illustrations showing how the death benefit riders work.
- Underwriting: Unlike traditional life insurance, which requires medical exams and blood tests, most of Athene's current products are "guaranteed issue" or have very simplified "suitability" checks. This is a major advantage for consumers with health issues who cannot qualify for traditional life insurance.
- The Suitability Review: Athene is known for a rigorous internal suitability review process. They will evaluate your age, income, and liquidity needs to ensure the product is appropriate for your financial situation before issuing the contract.
Frequently Asked Questions
Does Athene still sell term life insurance?
No. As of 2026, Athene Annuity and Life Company does not offer new individual term life insurance policies. They have transitioned their focus entirely to annuities and institutional retirement products. If you need term insurance, you would typically look to providers like State Farm, Northwestern Mutual, or specialized online term providers.
Is my old Aviva life insurance policy safe with Athene?
Yes. If your policy remained with Athene or was transferred to Accordia Life, it is protected by state guaranty associations (up to certain limits) and the high capital reserves of the parent companies. Athene is heavily regulated by state insurance departments, which require specific reserve levels to ensure all death claims can be paid.
What is the "Athenean" death benefit?
While "Athenean" is a common consumer misspelling, the death benefit in an Athene annuity refers to the payment made to beneficiaries. In a standard contract, this is the greater of the account value or the minimum guaranteed contract value. If an optional rider was purchased, the death benefit could be significantly higher based on a guaranteed growth rate.
How do beneficiaries file a claim with Athene?
Beneficiaries can initiate a claim through the Athene Claims Center. You will typically need the policy number, a certified copy of the death certificate, and a completed "Claimant’s Statement" form. Athene generally processes undisputed claims within 5 to 10 business days of receiving all required paperwork.
Can I change my Athene life insurance to an annuity?
If you have a legacy life insurance policy with cash value, you may be able to perform a 1035 Exchange. This is a tax-free transfer of the cash value from your life insurance policy into an Athene annuity. This is often done by consumers who no longer need the large death benefit of life insurance but want to use the accumulated cash for retirement income.
Final Recommendation for Consumers
If you are looking for "Athenean life insurance" in 2026, your best course of action depends on your primary goal. If you need pure protection to replace your income for a young family, you should look elsewhere for a term life policy.
However, if you are near or in retirement and want a vehicle that protects your principal, provides potential for market-linked growth, and ensures a guaranteed legacy for your heirs through a robust death benefit, Athene is a premier choice. Their high financial ratings and specialized retirement products make them a stable partner for long-term wealth transfer. Always work with a qualified financial professional to compare the tax implications of annuity death benefits versus traditional life insurance proceeds to ensure your estate plan is optimized for your specific jurisdiction and needs.