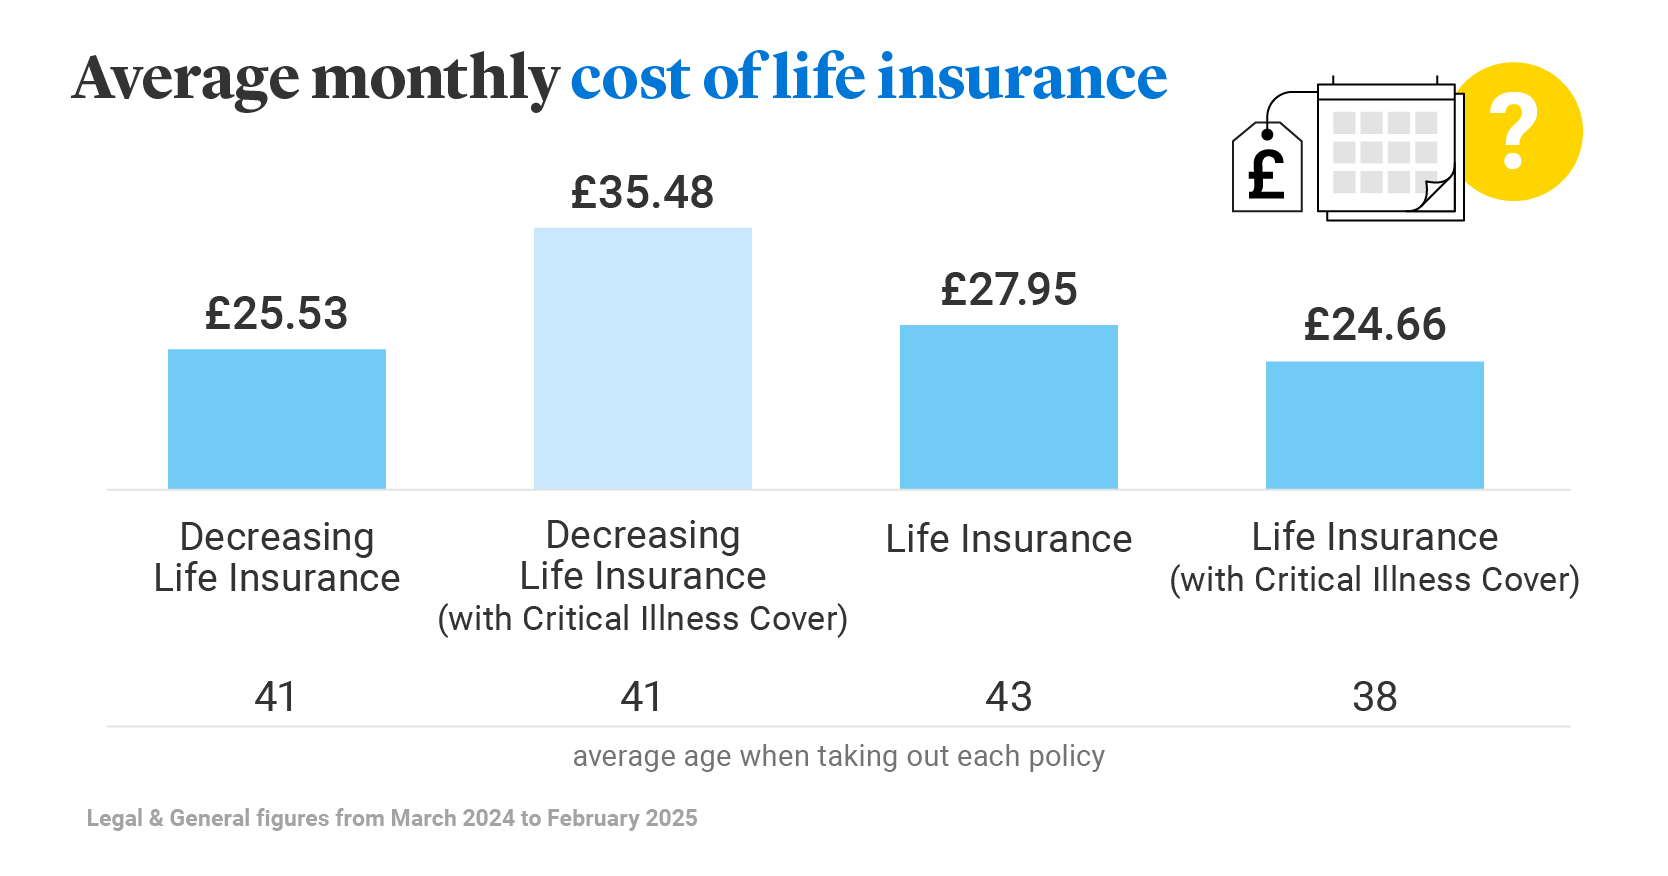
Legal & General is one of the oldest and most established financial services and insurance providers operating globally, offering a robust suite of life insurance products designed to provide financial security to families and businesses. When evaluating whether Legal & General life insurance is a viable option, consumers generally find a stable provider with high financial strength ratings, diverse policy types ranging from term to whole life, and flexible underwriting standards tailored to various health profiles and financial objectives.
Introduction to Legal & General Life Insurance
Evaluating life insurance options requires an understanding of a provider's market history, financial stability, product availability, and underwriting guidelines. Legal & General, tracing its origins back to 1836 in London, has grown into a major multinational financial services company. In the United States, its primary life insurance operations are conducted through Legal & General America (LGA), which encompasses Banner Life Insurance Company and William Penn Life Insurance Company of New York.
For consumers asking whether Legal & General life insurance policies are legitimate, dependable, and suitable for their needs, the short answer is yes. The company consistently ranks among the top term life insurance providers in North America and the United Kingdom, backed by strong financial ratings from major credit rating agencies. However, like any major insurer, its offerings come with specific structural parameters, underwriting rules, and cost variables that require careful analysis before application.
Understanding how Legal & General structures its products requires looking at the core types of coverage available, the mechanics of its application and underwriting processes, the financial backing of the institution, and the comparative advantages or disadvantages relative to other carriers in the marketplace.
Corporate Background and Financial Stability
When purchasing a life insurance policy—a contract that may last for decades or only pay out upon death—the financial health of the issuing carrier is of paramount importance. Policyholders must feel confident that the company will remain solvent and capable of paying claims far into the future.
Global Presence and US Operations
Legal & General Group Plc operates across multiple markets, managing substantial assets globally. In the United States, Banner Life Insurance Company (licensed in 49 states and the District of Columbia) and William Penn Life Insurance Company of New York (licensed in New York) underwrite the vast majority of the group's US life insurance portfolio. This dual-company structure allows the organization to serve nearly the entire US market while complying with state-specific regulatory frameworks.
Financial Strength Ratings
Financial strength ratings assigned by independent agencies provide an objective assessment of an insurer's financial stability and claim-paying ability. Legal & General's primary operating insurance subsidiaries routinely receive high marks from major rating agencies:
- A.M. Best: Typically assigns very high ratings (such as A+ or Superior) reflecting strong balance sheet strength, operating performance, and favorable business profile.
- Standard & Poor's (S&P): Regularly awards strong financial strength ratings, indicating a robust capacity to meet financial commitments to policyholders.
- Moody's Investors Service: Evaluates the insurer with investment-grade ratings, underscoring low credit risk and stable capitalization.
These ratings do not constitute a guarantee against all market fluctuations, but they place Legal & General among the more secure and reliable life insurance providers in the industry.
Core Life Insurance Products Offered
Legal & General specializes in certain types of coverage while maintaining a focused product catalog. Consumers looking for permanent lifetime coverage with complex investment accumulation features will find a different product mix than those seeking straightforward, cost-effective income replacement.
Term Life Insurance
Term life insurance is the flagship offering for Legal & General America. It provides pure death benefit protection for a specified period, typically ranging from 10 to 40 years.
- Affordability: Term policies offer the highest coverage amounts for the lowest initial premium outlay, making them ideal for income replacement during working years, covering mortgages, or funding children's education.
- Convertibility: Most Legal & General term policies feature a conversion privilege. This allows the policyholder to convert all or part of their term coverage into a permanent life insurance policy issued by the company without undergoing new medical exams or health underwriting, up to a certain age or policy anniversary.
Universal Life Insurance
For individuals seeking lifetime protection alongside flexible premium payment schedules and cash value accumulation potential, Legal & General offers universal life (UL) insurance products.
- Flexibility: Policyholders can adjust their premium payments and death benefits within contractually defined limits, responding to changing financial circumstances.
- Cash Value Growth: A portion of the premium payment is allocated to a cash value account that earns interest based on prevailing market rates or index performance, depending on the specific UL variant selected.
Whole Life Insurance
While less central to their US marketing strategy compared to term and universal life, permanent whole life options provide guaranteed death benefits, fixed premium payments, and cash value that grows at a guaranteed rate. These products are designed for estate planning, final expense coverage, and long-term asset accumulation.
Underwriting Process and Eligibility Criteria
The underwriting process determines whether an applicant qualifies for coverage and what premium rate they will pay. Legal & General utilizes a risk-classification system that ranges from preferred plus (for exceptionally healthy individuals) to standard or table-rated categories for those with pre-existing medical conditions.
Medical and Lifestyle Assessments
Securing a policy typically involves an evaluation of several health and lifestyle factors:
- Medical History: Detailed review of personal health records, including past surgeries, chronic conditions, and prescription drug usage.
- Family Medical History: Evaluation of hereditary conditions, such as heart disease or certain cancers, occurring in parents or siblings.
- Driving Record: Examination of motor vehicle reports for speeding tickets, DUIs, or reckless driving incidents.
- Hobbies and Occupation: Scrutiny of hazardous activities (such as skydiving, scuba diving, or private aviation) and dangerous occupations.
- Tobacco Use: Strict differentiation between cigarette smokers, cigar users, e-cigarette users, and non-users, as tobacco drastically impacts premium costs.
Accelerated Underwriting and Exam-Free Options
Legal & General offers accelerated underwriting programs for qualified applicants. Under specific age and coverage amount thresholds, individuals may be approved for term life insurance without requiring a traditional paramedical exam (blood draw and urine sample). Instead, eligibility is determined using algorithmic analysis of electronic health records, prescription databases, motor vehicle reports, and criminal background checks. This streamlines the application process, reducing approval times from weeks to days.
| Feature / Aspect | Legal & General Term Life | Legal & General Universal Life |
|---|---|---|
| Primary Purpose | Temporary income replacement, debt coverage | Lifetime protection, estate planning, cash accumulation |
| Duration | Fixed terms (10, 15, 20, 25, 30, 35, 40 years) | Lifetime (as long as premiums maintain positive cash value) |
| Premium Structure | Level premiums guaranteed for the duration of the term | Flexible premiums adjustable within contract limits |
| Medical Exam Requirement | Possible paramedical exam, or accelerated no-exam path for qualified applicants | Usually requires underwriting and medical evaluation |
| Cash Value Component | None (pure protection) | Yes, builds cash value over time |
| Convertibility | Typically convertible to permanent coverage before age 70 | N/A (already permanent) |
Advantages of Choosing Legal & General
Consumers evaluating Legal & General life insurance benefit from several distinct institutional and product advantages:
- Competitive Pricing for Term Coverage: Legal & General frequently ranks among the most cost-effective carriers for healthy applicants seeking long-term level term policies, particularly for 20-year and 30-year durations.
- Broad Issue Ages: The company offers term coverage to older applicants relative to many competitors, allowing some individuals up to age 75 or older to secure term policies depending on the specific product terms.
- High Coverage Limits: For high-net-worth individuals, business owners, or those with substantial family obligations, Legal & General underwrites very high face-value policy amounts, accommodating millions in coverage.
- Financial Stability: Backed by centuries of collective operating history and strong multi-agency ratings, providing peace of mind regarding long-term claims-paying integrity.
Limitations and Potential Drawbacks
Despite its strong market standing, Legal & General may not represent the optimal choice for every consumer:
- Strict Underwriting for Pre-Existing Conditions: While competitive for healthy individuals, applicants with managed chronic illnesses (such as controlled diabetes, mild anxiety, or past histories of cancer) may find more lenient underwriting guidelines with specialized high-risk carriers.
- Limited Direct-to-Consumer Digital Experience: While application intake is increasingly digitized, much of the process is mediated through independent insurance agents and brokers rather than a purely self-service online checkout platform.
- Fewer Living Benefits Add-ons: While accelerated death benefits for terminal illness are standard, certain comprehensive living benefit riders (such as chronic illness or critical illness riders that pay out for non-terminal conditions) may be less robust or flexible compared to competitors specializing in living benefits.
Common Questions Regarding Legal & General Life Insurance
Is Legal & General a legitimate and safe life insurance company?
Yes. Legal & General is a globally recognized financial institution with operations dating back to 1836. In the United States, its subsidiaries (Banner Life and William Penn) maintain high financial strength ratings from independent agencies like A.M. Best, confirming their strong capitalization and historical ability to honor claims.
Can I get Legal & General life insurance without a medical exam?
Yes, under specific circumstances. Legal & General offers accelerated underwriting programs for qualifying applicants within certain age brackets and coverage limits. If you meet their criteria, underwriting relies on electronic databases and prescription history checks rather than a physical paramedical exam, though the company reserves the right to request an exam if red flags appear.
What happens at the end of a Legal & General term life policy?
Once the fixed term (e.g., 20 or 30 years) expires, the pure death benefit coverage terminates unless renewed or converted. Most term policies include a conversion option that permits policyholders to switch to a permanent life insurance policy without proving insurability. If the policy expires without conversion, coverage ceases and no premiums are refunded unless you purchased a specialized return-of-premium rider.
How do I purchase a policy from Legal & General?
Legal & General distributes its products primarily through independent insurance agents, financial advisors, and digital brokerage platforms. You cannot typically purchase a policy directly over the counter from the corporate website without going through an authorized licensed agent or broker who can run quotes and submit the formal application.
Are premiums guaranteed to stay the same?
For level-term life insurance and fixed universal life policies, premiums are guaranteed to remain level for the duration specified in the contract, provided you pay the required amounts on time. However, yearly renewable term policies or adjustable universal life policies may experience premium adjustments based on changing administrative costs or interest rate environments.
Conclusion and Next Actions
Legal & General stands as a reliable, financially secure, and competitively priced provider of life insurance, particularly for term life products designed for income replacement and family protection. Prospective buyers should first determine their exact coverage needs—calculating future financial obligations, debt liabilities, and income replacement horizons.
The most effective next step is to consult with an independent insurance broker who can compare Legal & General quotes against other top-tier carriers. Requesting a preliminary health screening or checking eligibility for accelerated underwriting will help clarify whether you qualify for preferred rates, ensuring you secure the most appropriate and cost-effective coverage for your long-term financial plan.