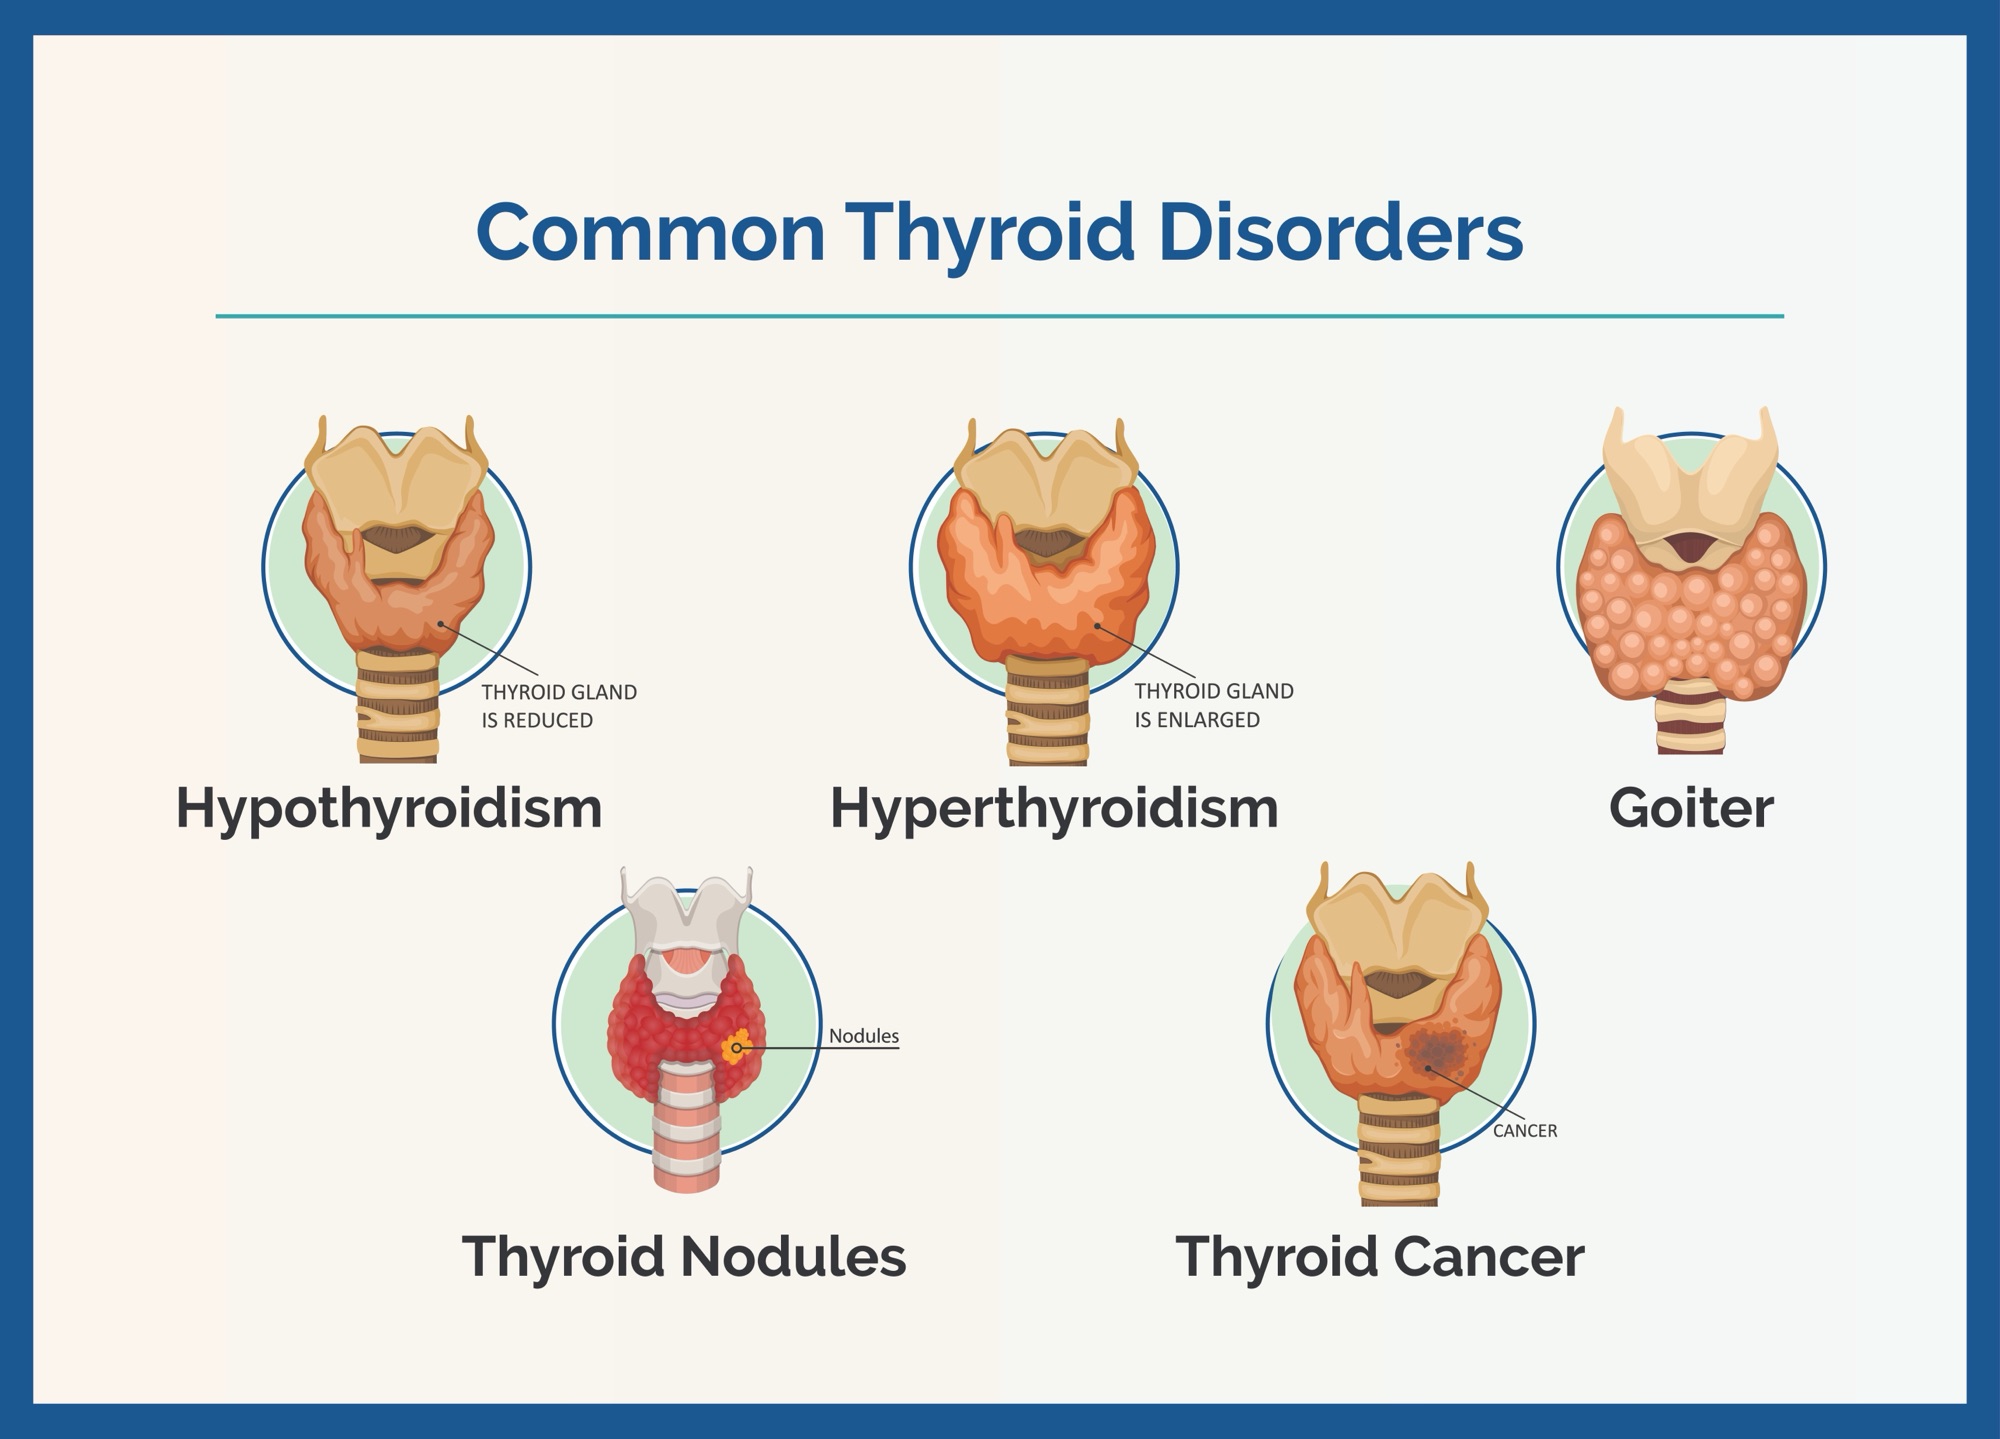
Medicare coverage for Armour Thyroid depends primarily on your specific Part D prescription drug plan or Medicare Advantage plan's formulary. While many plans exclude natural desiccated thyroid (NDT) drugs due to their classification as high-risk for seniors, coverage is possible through formulary exceptions or prior authorizations if your physician demonstrates medical necessity.
As of 2026, navigating the intersection of thyroid health and federal insurance requires a nuanced understanding of how Medicare evaluates "natural" versus "synthetic" hormones. For decades, the standard of care for hypothyroidism has leaned heavily toward synthetic levothyroxine (T4). However, a significant number of patients report better symptom management on Armour Thyroid, which contains both T4 and T3 (triiodothyronine) derived from porcine thyroid glands. This preference often creates a friction point between patient needs and Medicare’s cost-containment strategies.
Understanding Armour Thyroid and Its Clinical Standing
Armour Thyroid is the oldest branded form of natural desiccated thyroid (NDT). Unlike synthetic medications like Synthroid or generic levothyroxine, which provide only the T4 hormone, Armour Thyroid provides a combination of T4 and T3, along with T1, T2, and calcitonin. For many patients, the inclusion of T3 is vital because their bodies may struggle to convert T4 into the active T3 hormone efficiently.
In the eyes of Medicare and many private insurers, however, Armour Thyroid is often viewed with caution. This caution stems largely from the American Geriatrics Society’s Beers Criteria, a list of medications deemed potentially inappropriate for older adults. NDT medications have historically been included on this list due to concerns over potency stability and the potential for the T3 component to cause heart palpitations or cardiac stress in elderly patients. While modern manufacturing has largely solved the stability issues of the mid-20th century, the "high-risk" label remains a significant barrier to universal Medicare coverage in 2026.
How Medicare Part D Handles Armour Thyroid in 2026
Medicare Part D (prescription drug coverage) is provided by private insurance companies approved by Medicare. Each company creates its own formulary, which is a tiered list of covered drugs. In 2026, the landscape of Part D has been significantly altered by the provisions of the Inflation Reduction Act, which has redesigned the benefit structure.
The Tiering System
Most Part D plans categorize drugs into five or six tiers. Armour Thyroid is rarely found on Tier 1 (Preferred Generics) or Tier 2 (Generics). Instead, when it is covered, it typically occupies:
- Tier 3 (Preferred Brand): Requires a higher copayment.
- Tier 4 (Non-Preferred Drug): Requires a high coinsurance percentage (often 30% to 50% of the drug’s cost).
- Excluded: Some plans omit Armour Thyroid entirely, preferring that patients use synthetic alternatives.
The 2026 Benefit Redesign
It is important to note that starting in 2025 and continuing through 2026, Medicare Part D has a $2,000 out-of-pocket maximum. This is a major protection for beneficiaries. However, there is a crucial catch: only payments made for covered drugs count toward this $2,000 limit. If your plan excludes Armour Thyroid and you pay for it out-of-pocket without an approved exception, those costs do not contribute to your deductible or your out-of-pocket maximum.
The Challenge of the "High-Risk Medication" (HRM) Flag
One of the primary reasons a Medicare beneficiary might find their Armour Thyroid prescription rejected at the pharmacy is the High-Risk Medication (HRM) flag. Medicare monitors the use of certain drugs in the 65+ population to ensure safety. When a pharmacist runs a claim for Armour Thyroid, the system may generate a "soft" or "hard" reject.
A "soft" reject is an alert to the pharmacist to verify that the doctor is aware of the risks. A "hard" reject requires a Prior Authorization (PA). This means your prescribing physician must submit documentation to the insurance company explaining why Armour Thyroid is safer or more effective for you than the preferred synthetic alternatives. Common reasons for medical necessity include:
- Failure to achieve normal TSH/T3 levels on synthetic T4 alone.
- Allergic reactions to fillers in synthetic medications.
- Persistent hypothyroid symptoms (brain fog, fatigue, weight gain) despite "normal" lab results on levothyroxine.
Comparing Armour Thyroid Coverage with Alternatives
When evaluating your options for 2026, it is helpful to see how Armour Thyroid compares to other thyroid treatments in terms of Medicare's general coverage trends.
| Medication Type | Common Brand Names | Medicare Tier (Average) | Coverage Likelihood | 2026 Estimated Monthly Cost (Out-of-Pocket) |
|---|---|---|---|---|
| Synthetic T4 | Levothyroxine, Synthroid, Tirosint | Tier 1 or 2 | Very High | $4 – $25 (Generic) |
| Synthetic T3 | Liothyronine, Cytomel | Tier 2 or 3 | High | $15 – $40 (Generic) |
| Natural Desiccated (NDT) | Armour Thyroid | Tier 3, 4, or Excluded | Moderate to Low | $40 – $90 |
| Generic NDT | NP Thyroid | Tier 3 or 4 | Moderate | $30 – $60 |
Note: Costs are estimates for a standard 60mg (1 grain) dose and vary significantly by pharmacy and geography.
Strategies for Obtaining Coverage
If your Medicare Part D or Medicare Advantage plan does not list Armour Thyroid on its formulary, you are not necessarily out of options. There are specific administrative paths you can take to secure coverage or lower your costs.
Requesting a Formulary Exception
A formulary exception is a type of coverage determination. You or your doctor can ask the plan to cover a drug that is not on its list. To succeed, your doctor must provide a statement supporting the request. They must certify that all covered drugs on the plan’s formulary would not be as effective as Armour Thyroid or would cause adverse effects.
Tiering Exceptions
If Armour Thyroid is on your plan's formulary but is placed in a high-cost tier (like Tier 4), you can request a Tiering Exception. This asks the plan to provide the drug at the lower cost-sharing terms applicable to drugs in a more favorable tier. Note that you generally cannot request a tiering exception for a drug that is in the "Specialty Tier."
Using the Appeals Process
If your request for an exception is denied, you have the right to appeal. The Medicare appeals process has five levels, starting with a redetermination from your plan and potentially moving up to an Administrative Law Judge. Many patients find that persistence in the appeals process, backed by strong clinical data from their endocrinologist, eventually leads to coverage.
Costs Outside of Medicare: When to Bypass Your Plan
In some cases, the "contracted rate" through a Medicare Part D plan is actually higher than the cash price available through other means. This occurs frequently with Armour Thyroid because it is a relatively inexpensive drug to produce, but its "Non-Preferred" status in Part D plans inflates the coinsurance.
Discount Cards and Coupons
Programs like GoodRx, SingleCare, or WellRx can often bring the price of Armour Thyroid down to $30–$50 per month. Crucially, if you use these discount programs, you are bypassing your Medicare insurance. The amount you pay will not count toward your $2,000 Medicare out-of-pocket limit. However, if you are not a high-utilizer of other expensive brand-name drugs, paying cash for your thyroid medication might be the most economical choice.
Manufacturer Assistance
AbbVie, the manufacturer of Armour Thyroid, occasionally offers savings programs. However, federal "anti-kickback" laws generally prohibit Medicare beneficiaries from using manufacturer co-pay cards. Always check the fine print, as most of these coupons are restricted to patients with commercial (private) insurance.
Compounding Pharmacies
If you require a specific ratio of T4 to T3 that Armour Thyroid does not provide, a compounding pharmacy can create a customized NDT or synthetic combo. Be aware that Medicare almost never covers compounded medications, as they are not FDA-approved in their final compounded form.
Clinical Considerations for Seniors in 2026
As you manage thyroid health under Medicare, it is essential to work closely with an endocrinologist who understands the nuances of NDT. Because Armour Thyroid contains T3, it has a shorter half-life than T4-only medications. This can lead to peaks in hormone levels shortly after taking the pill.
For beneficiaries over 65, the primary concern is subclinical hyperthyroidism. If the dose of Armour Thyroid is even slightly too high, it can increase the risk of:
- Atrial Fibrillation (irregular heartbeat).
- Bone density loss (Osteoporosis).
- Insomnia and anxiety.
Regular blood testing in 2026 remains the gold standard. Most Medicare plans cover TSH (Thyroid Stimulating Hormone) and Free T4 tests, but you may need to ensure your doctor also orders Free T3 tests to get a complete picture of how Armour Thyroid is working in your system. Medicare covers these diagnostic tests under Part B, usually at 100% if they are part of a Medicare-covered office visit.
Frequently Asked Questions
Does Medicare Part B cover Armour Thyroid?
No. Medicare Part B covers "medical" costs like doctor visits, lab tests, and drugs administered by a physician (like infusions). Since Armour Thyroid is a self-administered oral tablet, it falls under Part D (Prescription Drug Coverage).
Why did my pharmacist say Armour Thyroid is "not covered" when it was covered last year?
Medicare Part D plans can change their formularies every year. A drug that was Tier 3 in 2025 may be excluded or moved to Tier 4 in 2026. Additionally, the plan may have added new "Step Therapy" requirements, requiring you to try and fail on levothyroxine before they will pay for Armour Thyroid.
Is there a generic version of Armour Thyroid covered by Medicare?
Technically, "Armour Thyroid" is a brand name for Natural Desiccated Thyroid. There are other NDT brands like NP Thyroid (by Acella) or Adthyza (by Azurity). While not "generics" in the traditional sense, some Medicare plans prefer NP Thyroid over Armour because it may be listed at a lower price point. Always ask your pharmacist to check coverage for all NDT brands.
Can I use my Health Savings Account (HSA) for Armour Thyroid if Medicare doesn't cover it?
If you are enrolled in Medicare, you can no longer contribute to an HSA. However, if you have existing funds in an HSA from your pre-Medicare years, you can absolutely use those tax-free dollars to pay for Armour Thyroid, whether or not your Medicare plan covers it.
What should my doctor write on the prescription to help with coverage?
To avoid unwanted substitutions and to assist with the Prior Authorization process, your doctor should write "Dispense as Written" (DAW) or "Brand Medically Necessary" on the prescription. They should also be prepared to provide clinical notes showing your T3 levels remain low on synthetic alternatives.
Practical Recommendation for 2026
If you are starting 2026 with an Armour Thyroid prescription, your first step should be to use the Medicare.gov Plan Finder tool. Enter your specific dosage and zip code to see which Part D or Medicare Advantage plans in your area include Armour Thyroid on their formulary.
If you are already enrolled in a plan that denies coverage, do not simply pay the high retail price. Request that your doctor initiate a Formulary Exception immediately. While the paperwork can be tedious, an approved exception can save you hundreds of dollars annually and ensure that your spending counts toward your $2,000 out-of-pocket maximum for the year. If the exception is denied, compare the "cash price" at local pharmacies using discount tools—sometimes the most straightforward path to thyroid health is found outside the traditional insurance framework.