Car loans through Arrow-branded institutions—primarily referring to Arrowhead Credit Union or the banking subsidiaries of Arrow Financial Corporation (Glens Falls National Bank and Saratoga National Bank)—offer competitive interest rates, flexible terms up to 84 months, and personalized local service. Borrowers can typically secure financing for new, used, or refinanced vehicles with low down payment requirements and streamlined digital application processes.
Car financing is a significant financial commitment that requires a clear understanding of the specific lender’s ecosystem. Because the term "Arrow Bank" is frequently used by consumers to describe two distinct financial entities—Arrowhead Credit Union and the banks managed by Arrow Financial Corporation—it is essential to distinguish between them to ensure you are applying to the correct institution for your geographic location and financial needs.
Navigating the "Arrow" Financial Landscape
When searching for an "Arrow Bank car loan" in 2026, you are likely looking for one of two major regional players. Resolving this ambiguity is the first step in your application journey.
- Arrowhead Credit Union: Based in Southern California, this member-owned cooperative is widely recognized for its aggressive auto lending rates and "member-first" philosophy. As a credit union, it requires membership, which is generally available to those who live, work, or worship in specific California counties (such as San Bernardino or Riverside).
- Arrow Financial Corporation (Glens Falls National Bank & Saratoga National Bank): Based in New York, this bank holding company operates local community banks. Their car loan products are traditional bank loans, often available through a network of local dealerships or direct branch applications in the Northeastern United States.
Both entities prioritize relationship-based lending, meaning they often look beyond just a credit score to consider the borrower's overall history with the institution.
Core Features of Arrowhead Credit Union Auto Loans
Arrowhead Credit Union remains a dominant force in the 2026 auto loan market due to its specific focus on high-LTV (Loan-to-Value) financing and flexible repayment structures.
Competitive Interest Rates and Terms
In 2026, interest rates remain sensitive to central bank shifts, but Arrowhead typically maintains a "Rate Beat" program or competitive baseline rates that undercut national commercial banks by 0.5% to 1.5%. They offer terms ranging from 36 months to 84 months. While 84-month terms carry higher interest rates, they provide the lower monthly payments often necessary for high-value modern vehicles.
New, Used, and Refinance Options
Arrowhead distinguishes between "New" (typically the current or previous model year with low mileage) and "Used" vehicles. Their refinance program is particularly robust, designed for borrowers who originally financed through a dealership at a higher rate and wish to move the debt to a credit union to reduce their monthly overhead.
The "Skip-a-Pay" Program
A hallmark of the Arrowhead experience is the Skip-a-Pay feature. Subject to approval and a small administrative fee, qualified borrowers can skip one monthly payment per year (usually during the holiday season or summer). This does not cancel the payment but moves it to the end of the loan term, providing temporary liquidity for the household.
Understanding Arrow Financial Corporation (GFNB and SNB) Car Loans
For those in the Northeast, the banks under the Arrow Financial umbrella (Glens Falls National and Saratoga National) offer a more traditional banking approach to car loans.
Community-Focused Underwriting
Unlike large national banks that rely purely on algorithmic scoring, Arrow Financial’s subsidiaries often employ manual underwriting for borderline cases. If you have a long-standing checking or savings account with them, your "internal score" can sometimes mitigate a slightly lower external credit score.
Dealer-Direct Financing
Many car buyers interact with "Arrow Bank" without ever visiting a branch. Arrow Financial maintains "indirect lending" partnerships with hundreds of dealerships. When you are in the dealership F&I (Finance and Insurance) office, you can specifically request that the dealer check rates with Glens Falls National or Saratoga National Bank.
Eligibility Requirements and Prerequisites
Securing a car loan in 2026 requires meeting several standardized criteria. While the two "Arrow" entities have different geographic footprints, their core documentation requirements are similar.
Membership and Residency
- Arrowhead CU: You must be a member. Membership involves opening a small savings account (often with as little as $5.00) and meeting residency requirements in San Bernardino, Riverside, or parts of Los Angeles and Orange Counties.
- Arrow Financial Banks: Membership is not required, but you generally need to reside within their service area in New York or neighboring states to facilitate the lien-holding process and account management.
Financial Documentation
Lenders in 2026 utilize automated income verification, but you should have the following ready:
- Proof of Income: Recent pay stubs, W-2s, or, for self-employed individuals, the last two years of tax returns.
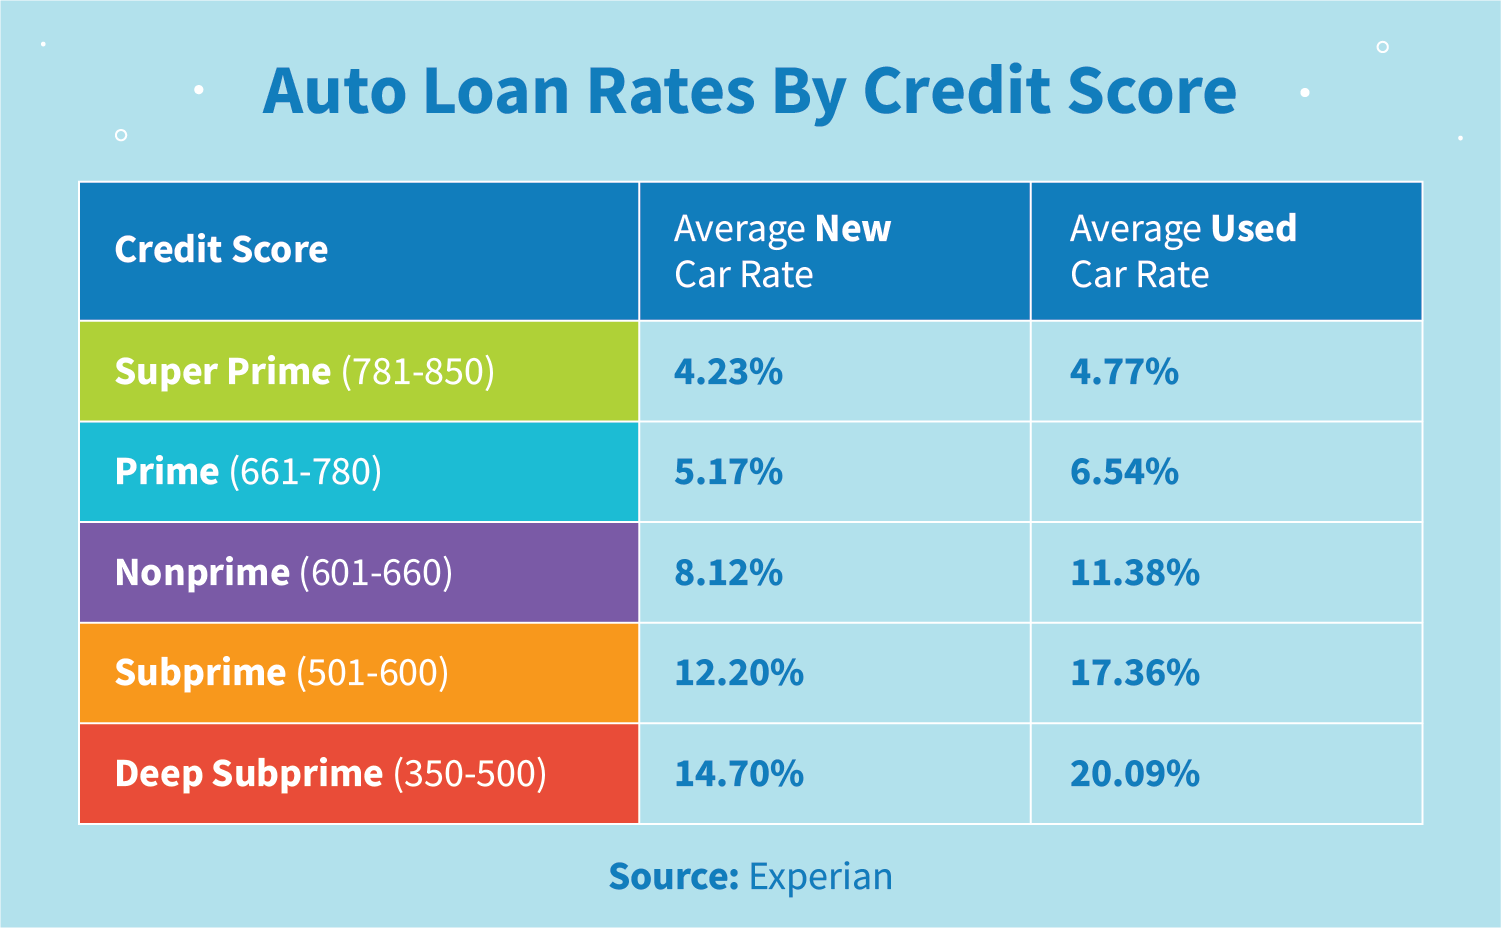
- Credit History: A minimum credit score is not strictly published, but "Prime" rates usually require a score of 720 or higher. "Subprime" options exist but come with significantly higher APRs.
- Debt-to-Income (DTI) Ratio: Most Arrow-branded loans require your total monthly debt payments (including the new car loan) to be below 45% of your gross monthly income.
Vehicle Restrictions
Not every car qualifies for a loan. Generally, the vehicle must:
- Have a clean title (no salvaged or branded titles).
- Be under a certain mileage threshold (typically 100,000 to 120,000 miles).
- Be newer than 10-12 years old.
The Application Process: Step-by-Step
Applying for an Arrow car loan has been optimized for the 2026 digital environment, allowing for near-instant "soft pull" pre-approvals.
- Get Pre-Approved: Before visiting a dealership, apply online through the respective Arrow website. Pre-approval gives you "cash-in-hand" bargaining power and sets a firm budget.
- Vehicle Selection: Once pre-approved, you have a specific window (usually 30 to 60 days) to find a vehicle. The loan amount is capped based on the vehicle's collateral value (NADA or Kelly Blue Book values).
- Verification of Collateral: Provide the lender with the Vehicle Identification Number (VIN), mileage, and a bill of sale. The lender will verify there are no existing liens that cannot be cleared.
- Finalize Documentation: This includes signing the Promissory Note and the Security Agreement. In 2026, this is almost exclusively done via secure e-signature platforms.
- Funding: For direct loans, the lender issues a check to the seller or dealership. For indirect loans (at the dealer), the funds are transferred electronically between the dealer and the bank.
Comprehensive Loan Comparison Table
The following table compares the typical structures found within the Arrow lending ecosystem in 2026.
| Feature | Arrowhead Credit Union | Arrow Financial (Banks) |
|---|---|---|
| Primary Region | Southern California | Upstate New York / Vermont |
| Loan Types | New, Used, Refinance, Private Party | New, Used, Dealer-Direct |
| Max Loan Term | Up to 84 Months | Up to 72-84 Months |
| Standard APR Range | 5.24% - 14.99% (Estimated) | 5.49% - 15.50% (Estimated) |
| Max Loan-to-Value | Up to 125% (includes taxes/fees) | Typically 100% - 110% |
| Application Fee | Generally $0 | May vary by region |
| Membership Needed | Yes | No |
| Online Management | Full Mobile App Support | Full Mobile App Support |
Note: APR ranges are estimates based on 2026 market projections and vary based on individual creditworthiness.
Associated Costs and Technical Considerations
When calculating the cost of an Arrow bank car loan, you must look beyond the monthly payment.
Interest Amortization
Arrow loans typically use Simple Interest. This means interest is calculated daily based on the remaining principal balance. If you pay your loan off early or make extra payments toward the principal, you significantly reduce the total interest paid over the life of the loan. There are generally no pre-payment penalties for Arrow car loans in 2026.
Loan-to-Value (LTV) and "Underwater" Risks
Arrowhead Credit Union allows for LTVs up to 125%. This is beneficial because it allows you to finance the sales tax, registration fees, and even extended warranties into the loan. However, this increases the risk of becoming "upside down" or "underwater"—where you owe more than the car is worth. To mitigate this, Arrow lenders strongly recommend GAP (Guaranteed Asset Protection) insurance.
Add-on Products
During the loan process, you will be offered:
- GAP Insurance: Covers the difference between the insurance payout and the loan balance if the car is totaled.
- MBP (Mechanical Breakdown Protection): Similar to an extended warranty, covering major repairs after the manufacturer’s warranty expires.
- Debt Protection: Cancels or suspends loan payments in the event of disability, involuntary unemployment, or death.
Common Mistakes to Avoid
- Ignoring the Total Cost of Credit: Borrowers often focus on the monthly payment. An 84-month loan at Arrowhead might have a low monthly cost, but the total interest paid over seven years can be thousands of dollars higher than a 60-month loan.
- Forgetting Membership Requirements: For Arrowhead CU, you cannot get the loan funded until your membership is fully processed. Do not wait until you are at the dealership on a Sunday afternoon to start this process.
- Not Checking Your Credit Report First: Ensure there are no errors on your TransUnion or Equifax reports. A single error can push you from a "Prime" tier to a "Near-Prime" tier, costing you significant money in interest.
Frequently Asked Questions (FAQ)
Can I get a car loan from Arrowhead Credit Union if I live outside California? Generally, no. Arrowhead is a regional credit union with a specific "field of membership." To be eligible for their car loans, you must meet their residency, employment, or familial relationship criteria within their approved California counties. However, if you are an existing member who moved away, you may still be eligible to apply for new credit.
Does Arrow Bank offer financing for private party sales? Yes, Arrowhead Credit Union is particularly well-known for facilitating private party sales. This process is slightly more complex than buying from a dealer, as the credit union must ensure the seller’s existing lien is paid off and the title is correctly transferred. Arrow Financial’s banks also offer this, though they may require an inspection of the vehicle first.
What is the minimum credit score for an Arrow car loan? There is no absolute "hard" minimum, but scores below 620 are generally considered "subprime." Borrowers in this range may require a larger down payment (20% or more) or a co-signer to mitigate the lender's risk. Those with scores above 740 will qualify for the lowest advertised rates.
How long does the approval process take? In 2026, the initial automated decision often takes less than five minutes through the online portal. If the application requires manual review (due to complex income or credit issues), it typically takes one to two business days. Once approved, funding can happen the same day if all documents are signed electronically.
Can I refinance a car loan I already have with another bank to Arrow? Yes, refinancing is a core product for both Arrowhead and Arrow Financial banks. This is a strategic move if interest rates have dropped since you originally purchased the car, or if your credit score has improved significantly. Arrow often offers incentives, such as "no payments for 90 days," for refinance customers.
Practical Recommendation
If you are a resident of Southern California, your first step should be to apply for a pre-approval through Arrowhead Credit Union. Their member-centric model and high LTV allowances make them ideal for buyers who want to minimize their out-of-pocket "drive-off" costs.
For those in the Northeast, contact Glens Falls National Bank or Saratoga National Bank before going to the dealership. Ask for their current "direct-to-consumer" rates. If the dealership offers you a lower rate through another lender, you can use your Arrow quote as leverage to ensure you are getting the best possible deal. Regardless of which "Arrow" you choose, always aim for a loan term of 60 months or less to maintain equity in your vehicle and minimize total interest expenses.