AIG Direct whole life insurance, now primarily serviced under the Corebridge Financial brand, is a permanent life insurance solution designed to provide lifelong coverage, fixed premiums, and a guaranteed cash value component. Reviews in 2026 highlight the company's strong financial stability and the accessibility of its guaranteed issue products, though some users note that the digital application process can occasionally require manual follow-up.
Understanding the Relationship Between AIG Direct and Corebridge Financial
To accurately review AIG Direct whole life insurance in 2026, one must first understand the corporate evolution of the entity. Formerly known as AIG Life & Retirement, the company completed its rebranding and separation into Corebridge Financial several years ago. While the "AIG Direct" marketing channel remains a familiar entry point for many consumers, the underlying policies are issued and serviced by Corebridge Financial subsidiaries, such as American General Life Insurance Company.
For the consumer, this transition has largely meant improved digital interfaces and a more focused approach to retirement and life insurance products. When researching reviews, it is essential to look at both "AIG Direct" feedback and "Corebridge Financial" ratings, as they represent the same product suite. The 2026 market sees Corebridge as a standalone powerhouse, maintaining the high-grade financial ratings previously associated with the AIG parent company.
Core Features of AIG Direct Whole Life Insurance
AIG Direct focuses heavily on permanent protection. Unlike term life insurance, which expires after a set number of years, whole life insurance remains in effect for the insured's entire lifetime, provided premiums are paid.
1. Guaranteed Death Benefit
The primary purpose of the policy is the death benefit. AIG Direct whole life policies offer a fixed amount that will be paid to beneficiaries tax-free. This is a critical feature for those looking to cover final expenses, such as funeral costs, or to leave a small legacy for family members. In 2026, these policies remain a staple for "final expense" planning.
2. Level Premiums
One of the most praised aspects in consumer reviews is the premium stability. Once a policy is issued, the monthly or annual premium is locked in for life. It will not increase as the policyholder ages or if their health declines. This predictability is vital for seniors on fixed incomes who need to budget for the long term.
3. Cash Value Accumulation
Every whole life policy through AIG Direct includes a cash value component. A portion of each premium payment is diverted into a savings-like account that grows at a guaranteed rate. Over time, the policyholder can borrow against this cash value or surrender the policy for its current value. In the 2026 economic environment, this guaranteed growth offers a conservative hedge against market volatility.
Analysis of Consumer Reviews in 2026
Consumer sentiment regarding AIG Direct whole life insurance is generally positive, particularly among the 50-80 age demographic. However, a nuanced look at the feedback reveals specific areas of excellence and occasional friction.
High Marks for Accessibility and "Guaranteed Issue"
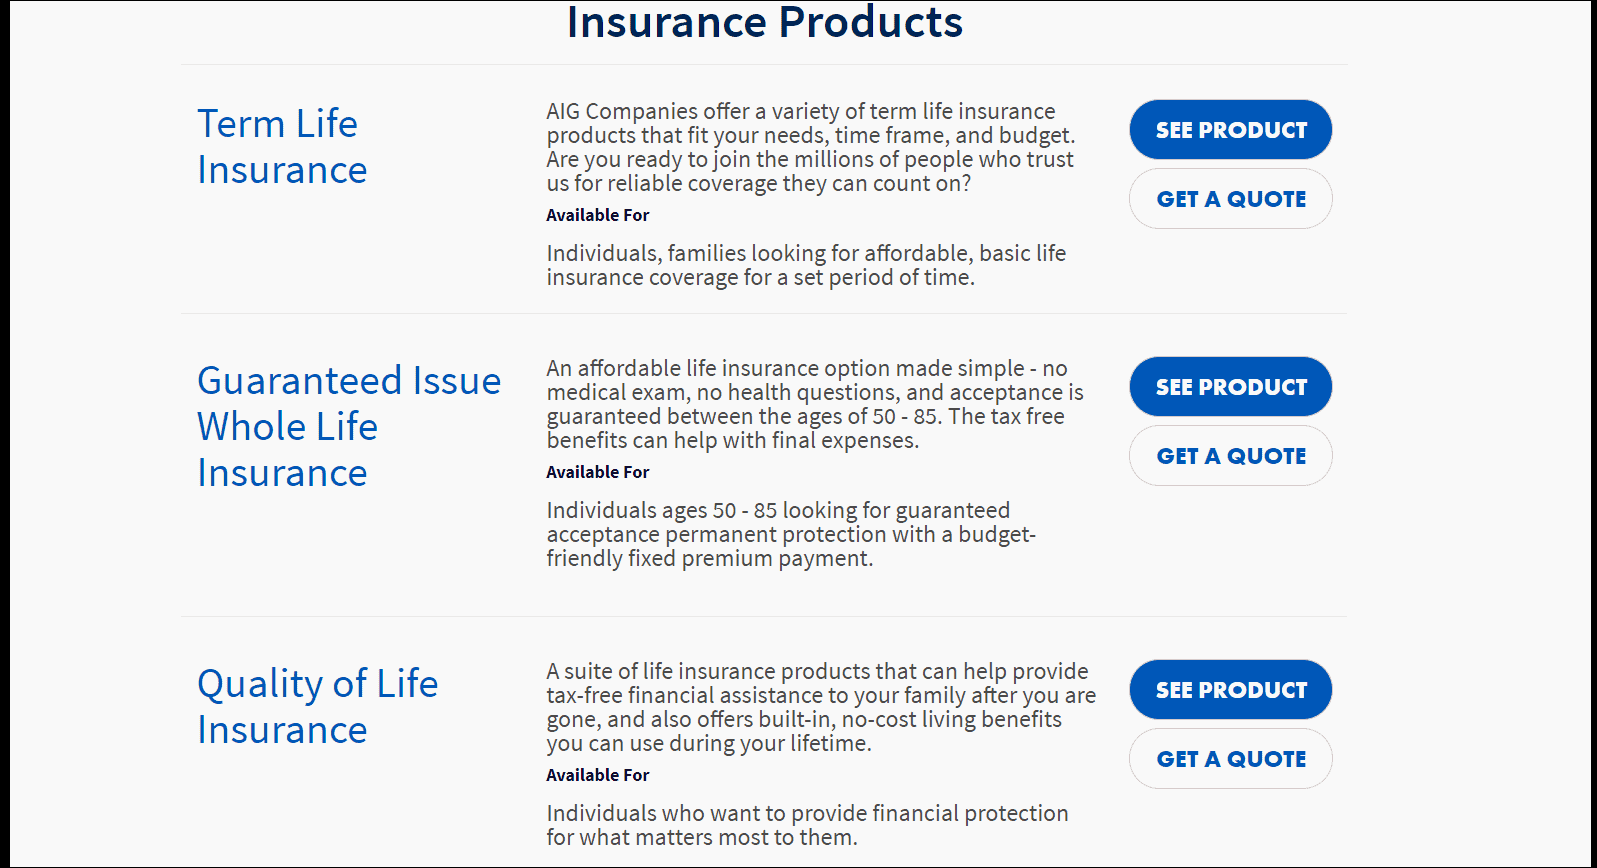
A significant portion of AIG Direct’s whole life business is Guaranteed Issue Whole Life (GIWL). Reviews frequently cite the ease of obtaining coverage as a major "pro." Because these policies do not require a medical exam or even health questions, they are a lifeline for individuals with pre-existing conditions who have been turned down elsewhere.
- User Perspective: "I was worried my heart condition would prevent me from getting coverage. AIG Direct made it simple. No needles, no doctors, just a straightforward application."
- Expert Insight: The trade-off for this accessibility is a "graded death benefit." Most reviews mention that if the insured passes away from natural causes within the first two years, the beneficiaries receive the premiums paid plus interest, rather than the full face amount.
Customer Service and Digital Experience
In 2026, the shift toward a "digital-first" experience under Corebridge Financial has seen mixed reviews. Younger beneficiaries and tech-savvy seniors appreciate the online portal for making payments and updating beneficiaries. However, some traditionalists report longer-than-expected wait times when calling for complex claims or policy changes.
Claims Processing
A critical metric for any insurance review is the claims process. Most 2026 reviews indicate that Corebridge/AIG Direct is reliable in paying out claims once the necessary documentation is submitted. The company’s high financial strength ratings (typically A or better from agencies like AM Best) provide peace of mind that the funds will be available when needed.
Comparing AIG Direct Whole Life with Competitors
To determine if AIG Direct is the right choice, it is helpful to see how it stacks up against other major players in the 2026 life insurance market.
| Feature | AIG Direct (Corebridge) | Mutual of Omaha | State Farm |
|---|---|---|---|
| Primary Focus | Guaranteed Issue / Seniors | Broad Whole Life Options | Agent-Driven Full Life |
| Issue Ages | 50–80 (typical for GIWL) | 45–85 | 0–80 |
| Medical Exam | Not required for GIWL | Required for some plans | Often required |
| Cash Value | Guaranteed Growth | Dividend potential (some plans) | Guaranteed Growth |
| Financial Strength | A (Excellent) | A+ (Superior) | A++ (Superior) |
| Application Speed | Rapid (Minutes) | Moderate | Slower (Agent-dependent) |
The Application Process: What to Expect
If you are considering AIG Direct based on positive reviews, the process is designed to be streamlined. Here is the typical path to securing a whole life policy in 2026:
- Initial Quote: You provide your age, gender, state of residence, and the amount of coverage you desire (typically ranging from $5,000 to $25,000 for guaranteed issue).
- Selection: You choose the premium schedule that fits your budget.
- No-Medical Application: For the guaranteed issue product, you skip the physical exam. You will need to provide basic identification and beneficiary details.
- Review and Approval: Because it is guaranteed issue, "approval" is essentially automatic once the application is submitted and the first premium is processed.
- Policy Delivery: In 2026, most policies are delivered electronically for immediate review, though paper copies are still available upon request.
Technical Considerations: The Graded Death Benefit
A recurring theme in technical reviews of AIG Direct whole life is the two-year graded death benefit. It is crucial for consumers to understand this mechanic to avoid disappointment.
Because the company takes on the risk of insuring individuals without a medical exam, they protect themselves by implementing a waiting period. If the insured dies within the first 24 months of the policy from natural causes (illness, old age), the death benefit is not the full $10,000 or $20,000 face value. Instead, the company returns all premiums paid to date plus a fixed percentage of interest (often 10%). If the death is accidental (e.g., a car crash), the full benefit is usually paid from day one. After the 24-month mark, the full benefit is active for all causes of death.
Potential Drawbacks Found in Reviews
While the company is a top-tier provider, certain "cons" appear in critical reviews:
- Cost per Thousand: Because guaranteed issue policies include everyone regardless of health, the premiums are higher per dollar of coverage compared to a policy that requires a medical exam. If you are in excellent health, reviews often suggest looking at a simplified issue or fully underwritten policy instead.
- Low Coverage Ceilings: These policies are generally capped at $25,000. If you need $100,000 or more to cover a mortgage or provide for a young family, AIG Direct's whole life products (specifically the direct-to-consumer ones) may not be sufficient.
- Rebranding Confusion: Some older reviews still refer to "AIG" and express confusion when receiving correspondence from "Corebridge Financial." Ensuring customers understand they are dealing with the same established entity is an ongoing challenge for the brand.
Financial Strength and Reliability
In 2026, the financial viability of an insurance provider is more important than ever. Corebridge Financial (the issuer of AIG Direct policies) maintains strong ratings from the major credit agencies. This is a non-negotiable factor for whole life insurance, as you are essentially entering into a contract that could last 30 or 40 years.
- AM Best: Continues to rate the core operating subsidiaries with an "A" (Excellent) rating, reflecting a strong balance sheet and favorable operating performance.
- Fitch Ratings: Typically assigns an "A" or "A+" rating, citing the company's significant scale in the US life insurance market.
- JD Power: Recent studies on individual life insurance customer satisfaction often place Corebridge in the middle-to-high pack, noting improvements in their digital claim filing tools.
Is AIG Direct Whole Life Right for You?
Based on a comprehensive review of the 2026 landscape, AIG Direct (Corebridge) is an ideal choice for specific profiles:
- Seniors (Ages 50–80): Specifically those looking for "burial insurance" or "final expense" coverage.
- Individuals with Health Issues: If you have been denied coverage elsewhere due to diabetes, heart disease, or other chronic conditions, the guaranteed issue whole life policy is a premier option.
- Those Prioritizing Simplicity: If you want to avoid the hassle of blood tests and physician statements, the direct-to-consumer model is highly efficient.
However, if you are under 50 or in excellent health, you may find better value in a policy that rewards your health status with lower premiums, which may require looking beyond the "guaranteed issue" products.
Frequently Asked Questions
Does AIG Direct whole life insurance require a medical exam?
For their flagship Guaranteed Issue Whole Life product, no medical exam or health questions are required. For other whole life products that offer higher coverage amounts, a medical exam or a health questionnaire may be necessary to determine your premium rate.
Is AIG Direct the same as Corebridge Financial?
Yes. In the early 2020s, AIG separated its life and retirement business into a new company called Corebridge Financial. AIG Direct is the marketing arm that consumers often interact with first, but the policies are legally issued and serviced by Corebridge.
What is the maximum coverage amount for whole life at AIG Direct?
The direct-to-consumer guaranteed issue policies typically cap out at $25,000. This is intended to cover funeral costs, small debts, and final medical bills rather than providing long-term income replacement for a family.
Can I cancel my AIG Direct policy if I change my mind?
Yes. Most policies come with a "Free Look" period (typically 10 to 30 days depending on your state). During this time, you can cancel the policy and receive a full refund of any premiums paid. After this period, you can cancel at any time, but you will only receive the "cash surrender value" accumulated in the policy, which is minimal in the early years.
How does the cash value work in an AIG Direct whole life policy?
A portion of your premium is set aside in a cash value account. This account grows at a guaranteed minimum interest rate set by the company. You can take a loan against this value, but it is important to remember that any unpaid loans will be deducted from the final death benefit paid to your beneficiaries.
Final Recommendation
For those seeking a "set it and forget it" permanent insurance policy, particularly seniors or those with health challenges, AIG Direct (Corebridge Financial) remains a top-tier contender in 2026. The company’s combination of financial heritage and streamlined digital application processes makes it a reliable choice for final expense planning. While the premiums reflect the high risk the company takes on for guaranteed coverage, the peace of mind provided by a guaranteed death benefit and fixed premiums is often worth the cost for many families.