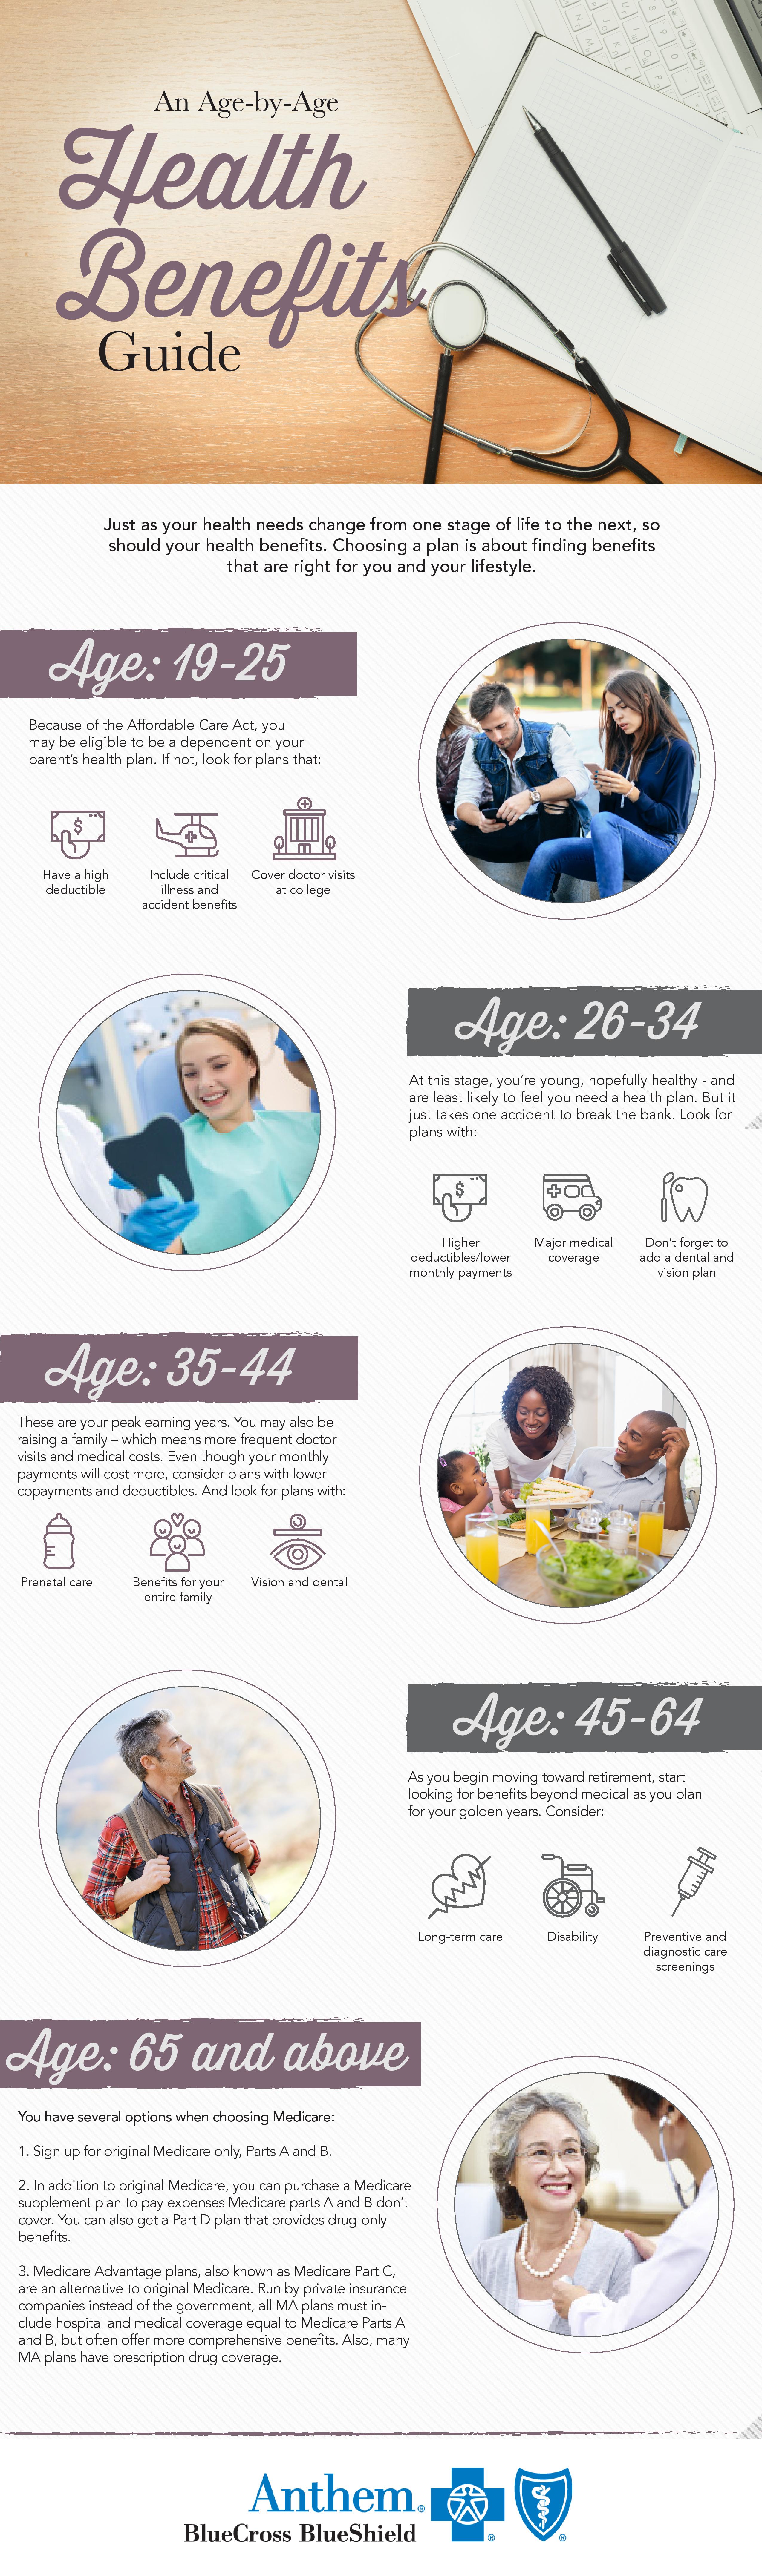
Anthem Blue Cross and Blue Shield is the primary brand for Elevance Health in Indiana, offering a diverse range of health insurance products including individual Marketplace plans, Medicare, Medicaid, and employer-sponsored coverage. For Indiana residents in 2026, Anthem remains the most prominent insurer, utilizing extensive provider networks and integrated digital tools like the Sydney Health app to manage care delivery across all 92 counties.
Understanding Anthem's presence in Indiana requires a look at how they segment their offerings to meet different life stages and financial needs. Whether you are an entrepreneur looking for a Marketplace plan, a senior navigating Medicare, or a low-income resident qualifying for the Healthy Indiana Plan (HIP), Anthem provides a specific infrastructure for each.
The Foundation of Anthem in Indiana
Anthem is the trade name of Anthem Insurance Companies, Inc., and is an independent licensee of the Blue Cross and Blue Shield Association. In Indiana, this distinction is critical because it gives members access to the BlueCard® program, which allows for coverage outside of the state through other Blue Cross Blue Shield affiliates.
In 2026, Anthem continues to dominate the Indiana landscape due to its historical roots in the state and its massive network of hospitals and physicians. Choosing an Anthem plan often comes down to the balance between monthly premiums and the breadth of the provider network. Because they hold a significant market share, most major healthcare systems in Indiana—such as IU Health, Community Health Network, and Franciscan Health—typically participate in at least one of Anthem's many networks, though specific plan participation can vary.
Individual and Family Marketplace Plans (ACA)
For those who do not have access to employer-sponsored insurance, the Affordable Care Act (ACA) Marketplace is the primary avenue for coverage. Anthem’s individual plans in Indiana are often branded under the "Pathway" or "Blue Access" names.
Metal Tiers and Cost Sharing
Anthem categorizes its Indiana Marketplace plans into metal tiers, which determine how you and the insurer split costs:
- Bronze Plans: These generally have the lowest monthly premiums but the highest deductibles. They are designed for individuals who do not expect to need frequent medical care but want protection against catastrophic costs.
- Silver Plans: These represent the "middle ground" and are the only plans eligible for Cost-Sharing Reductions (CSRs) if your income falls within certain limits. In 2026, Silver plans remain the most popular choice for Hoosiers qualifying for subsidies.
- Gold Plans: These have higher monthly premiums but lower out-of-pocket costs at the point of service. They are ideal for individuals with chronic conditions or those who anticipate frequent specialist visits.
Network Types: Pathway vs. Blue Access
A common point of confusion when Anthem health insurance in Indiana is explained is the difference between networks.
- Pathway (HMO/EPO): Many individual plans use the Pathway network. These plans often require you to stay within a specific list of providers to have coverage (except for emergencies).
- Blue Access (PPO): Generally available through employers or certain higher-tier individual plans, this offers more flexibility to see out-of-network providers, though at a higher cost.
Anthem Medicare Options in Indiana
As the population ages, Anthem’s Medicare footprint in Indiana has expanded. Hoosiers who are 65 or older, or those with specific disabilities, have three primary ways to access Anthem’s Medicare coverage in 2026.
Medicare Advantage (Part C)
Anthem Medicare Advantage plans replace original Medicare (Parts A and B) and often include prescription drug coverage (Part D). These plans are popular in Indiana because they frequently offer "extra" benefits that original Medicare does not, such as:
- Dental, vision, and hearing coverage.
- SilverSneakers fitness memberships.
- Allowances for over-the-counter (OTC) health items.
- Transportation assistance to medical appointments.
Medicare Supplement (Medigap)
For those who prefer to keep Original Medicare but want to limit their out-of-pocket exposure (like the 20% coinsurance), Anthem offers Medigap plans. These plans are standardized (Plan G, Plan N, etc.) and allow you to see any doctor in the U.S. that accepts Medicare.
Prescription Drug Plans (Part D)
If you have a Medigap plan or Original Medicare alone, you need a standalone Part D plan to cover medications. Anthem offers several tiers of Part D plans in Indiana, ranging from basic low-premium options to comprehensive plans with no deductibles on generic drugs.
Medicaid and the Healthy Indiana Plan (HIP)
Anthem is a major contractor for the State of Indiana’s Medicaid programs. This is a vital component of the state's healthcare safety net.
Healthy Indiana Plan (HIP)
The Healthy Indiana Plan is a health insurance program for low-income adults ages 19-64. Anthem’s HIP plans focus on preventive care and personal responsibility through the POWER Account—a special savings-like account used to pay for healthcare. In 2026, Anthem continues to provide HIP Plus (which includes vision and dental) and HIP Basic options depending on member contributions and eligibility.
Hoosier Healthwise and Hoosier Care Connect
Anthem also manages coverage for children, pregnant women, and individuals with disabilities or complex medical needs through these state-sponsored programs. These plans emphasize care coordination, ensuring that members with chronic illnesses have a dedicated case manager to help navigate the healthcare system.
Comparison of Anthem Indiana Plan Categories
| Feature | Marketplace (Individual) | Medicare Advantage | Healthy Indiana Plan (HIP) |
|---|---|---|---|
| Eligibility | IN Residents (Non-Employer) | Age 65+ or Disability | Low-income Adults (19-64) |
| Subsidies | Income-based (APTC) | N/A (Federal funding) | State/Federal funded |
| Primary Network | Pathway / Blue Access | Medicare Provider Network | Anthem Medicaid Network |
| Dental/Vision | Often an Add-on | Typically Included | Included in "Plus" plans |
| Drug Coverage | Included in most plans | Usually Included (MAPD) | Included |
Key Features and Member Tools in 2026
To differentiate itself from competitors like UnitedHealthcare or CareSource, Anthem has invested heavily in technology and integrated services within the Indiana market.
Sydney Health App
The Sydney Health mobile app is the central hub for Anthem members. In 2026, the app allows Indiana members to:
- Access digital ID cards.
- Check the status of claims and view "Explanation of Benefits" (EOB) statements.
- Use a "Find Care" tool to locate in-network doctors, labs, and urgent care centers.
- Sync with fitness trackers to participate in wellness rewards programs.
Telehealth via LiveHealth Online
Anthem has fully integrated telehealth into its Indiana plans. Members can access board-certified doctors 24/7 for non-emergency issues like the flu, allergies, or sinus infections. In many 2026 plans, the copay for a virtual visit is significantly lower than a visit to an urgent care clinic, making it a cost-effective first step for minor ailments.
Carelon: The Health Services Link
Anthem’s parent company, Elevance Health, uses its Carelon brand to manage specific services like pharmacy benefits (CarelonRx) and behavioral health. For an Indiana member, this means that your prescriptions and mental health services are often managed under the same umbrella, theoretically leading to better data sharing between your pharmacist and your therapist.
Navigating Costs: Premiums, Deductibles, and Subsidies
When Anthem health insurance in Indiana is explained, cost is usually the primary concern. Your total expenditure is the sum of your monthly premium and your out-of-pocket costs when you receive care.
- Monthly Premiums: This is the fixed cost you pay every month to keep your insurance active. In Indiana, premiums vary by rating area (e.g., Indianapolis vs. Evansville) and age.
- Deductibles: This is the amount you must pay for covered services before Anthem begins to pay. In 2026, some Anthem "Enhanced" plans offer $0 deductibles for certain services like primary care visits, even if the overall plan deductible hasn't been met.
- Advanced Premium Tax Credits (APTC): For Marketplace plans, these subsidies act as a discount on your monthly premium. They are based on your estimated household income for 2026. If you earn between 100% and 400% (and sometimes higher) of the Federal Poverty Level, these credits can drastically reduce your costs.
Common Pitfalls and How to Avoid Them
Even with comprehensive coverage, Indiana residents can face unexpected bills if they don't follow specific plan rules.
- Out-of-Network Surprises: While the "No Surprises Act" protects you in emergency situations, elective procedures at an out-of-network facility can result in massive bills. Always verify that both the facility and the specific surgeon or anesthesiologist are in-network for your Anthem plan.
- Prior Authorization: Anthem requires prior approval for many surgeries, advanced imaging (like MRIs), and specialty drugs. Ensure your provider has secured this authorization before proceeding with treatment.
- Formulary Changes: Anthem updates its list of covered drugs (formulary) annually. A medication that was covered in 2025 might be in a different cost tier or excluded in 2026. Review your plan's "Notice of Change" sent every autumn.
Selecting the Right Anthem Plan in Indiana
To choose the best plan, follow these three steps:
- Audit Your Usage: Look at your medical records from the past 24 months. How many prescriptions do you take? How many specialist visits do you have annually? If your usage is high, a Gold plan or a PPO might be cheaper in the long run despite the higher premium.
- Check Your Doctors: Use the Anthem "Find Care" tool specifically for the 2026 plan year. Do not assume your doctor is in-network just because they were last year.
- Evaluate Total Cost of Risk: Consider the "Maximum Out-of-Pocket" (MOOP) limit. This is the absolute most you would have to pay in a calendar year for covered in-network services. If you had a major accident, could you afford the MOOP of a Bronze plan? If not, a Silver or Gold plan might be a safer financial choice.
Frequently Asked Questions
Is Anthem the same as Blue Cross Blue Shield in Indiana?
Yes, Anthem is the specific company that owns the rights to the Blue Cross and Blue Shield names and trademarks in the state of Indiana. While other companies might use the Blue Cross name in other states (like Illinois or Michigan), Anthem is the sole provider of BCBS plans for Indiana residents.
Does Anthem Indiana cover weight loss medications in 2026?
Coverage for weight loss medications (such as GLP-1 agonists) depends entirely on the specific plan type. Many employer-sponsored plans and some high-tier Marketplace plans may cover them with prior authorization, but most Medicare Part D plans currently exclude medications specifically for weight loss unless they are prescribed for a different FDA-approved use, like Type 2 diabetes.
How do I find out if my Indiana doctor is in Anthem's network?
The most reliable method is to log into the Sydney Health app or the Anthem website and use the "Find Care" tool. You should filter the search by your specific plan name (e.g., "Anthem Pathway X" or "Blue Access PPO") because a doctor might accept one Anthem network but not another.
Can I use my Anthem Indiana plan in another state?
If your plan is a PPO or has the BlueCard® symbol (a small suitcase icon) on your ID card, you can access Blue Cross Blue Shield providers nationwide. If you have an HMO or a "Pathway" plan, your coverage is generally restricted to Indiana providers, except in the case of a true medical emergency.
What is the difference between Anthem HIP and regular Anthem Medicaid?
Anthem HIP (Healthy Indiana Plan) is specifically for adults ages 19-64. Regular Anthem Medicaid (often under Hoosier Healthwise) is generally for children and pregnant women. HIP requires members to participate in the POWER account system, whereas Hoosier Healthwise does not typically have the same contribution requirements.
Final Recommendations for Hoosiers
For 2026, Indiana residents should view Anthem not as a single product, but as a suite of options. The "best" plan is the one that aligns with your specific health trajectory. If you are healthy and rarely see a doctor, a Bronze Pathway plan offers the best protection against financial ruin. If you manage multiple chronic conditions, the Gold PPO or a Medicare Advantage plan with low copays will likely serve you better. Always re-evaluate during the Open Enrollment period, as network shifts and subsidy changes can significantly alter the value proposition of your current coverage.
Disclaimer: Health insurance regulations and plan details are subject to change. Always refer to your Summary of Benefits and Coverage (SBC) or consult with a licensed insurance agent in Indiana for personalized financial advice.