Finding affordable auto insurance in Marion, IA requires balancing Iowa’s statutory minimum liability laws with adequate protection for daily commuting and unpredictable Midwest weather. Marion drivers can secure lower premiums by comparing quotes from national and regional carriers, leveraging policy discounts, raising deductibles appropriately, and maintaining a clean driving record.
Iowa Car Insurance Requirements: Statutory Minimums Explained
Driving legally in Marion and throughout Linn County requires meeting the financial responsibility standards established under Iowa Code Chapter 321A. Iowa enforces a "20/40/15" mandatory minimum liability insurance structure. This means every policy sold in the state must provide at least:
- $20,000 for Bodily Injury or Death per Person: Covers medical bills, lost wages, and legal defense costs if you injure one individual in an at-fault accident.
- $40,000 for Bodily Injury or Death per Accident: Limits total payouts for medical injuries when two or more people are hurt in a single collision you cause.
- $15,000 for Property Damage per Accident: Pays to repair or replace another person's vehicle, fence, utility pole, or structure damaged in a crash.
While carrying state minimum limits satisfies legal obligations to register and operate a motor vehicle, it leaves drivers exposed to financial liability. Modern repair costs and emergency medical expenses frequently exceed these limits. For instance, colliding with a late-model truck or causing a multi-vehicle pileup on Highway 100 can easily surpass $15,000 in property damage, leaving the at-fault driver personally responsible for the remaining balance through asset seizure or wage garnishment.
Uninsured and Underinsured Motorist Regulations
In Iowa, insurance providers are legally required to offer Uninsured Motorist (UM) and Underinsured Motorist (UIM) coverage on every auto policy. While state law allows policyholders to reject these coverages in writing, insurance experts strongly advise retaining them. UM/UIM protection covers your medical expenses, rehabilitation, and lost earnings if you are struck by a hit-and-run driver or a motorist carrying insufficient liability limits.
Key Rating Factors Shaping Auto Insurance Costs in Marion
Insurance carriers calculate auto premiums using actuarial algorithms designed to predict risk. In Marion (primarily covering the 52302 ZIP code), several localized and individual variables dictate your final monthly rates.
- Geographic Location: Traffic density on IA-100, US-151, and I-380
- Midwest Weather: Winter snow/ice hazards & spring hail storms
- Credit Score: Credit-based insurance scores (Iowa regulations)
- Driving History: Moving violations, accidents, and claims history
- Vehicle Selection: Safety features, repair costs, vehicle value
1. Suburban Geography and Daily Commuting Routes
Marion’s suburban growth has led to increased traffic volume along key arteries, including Highway 13, US-151, and the Collins Road extension (IA-100). Drivers who regularly commute into Cedar Rapids or take Interstate 380 toward Iowa City log higher annual mileage during peak rush hours, statistically increasing collision probability. Insurers evaluate your daily commuting distance and typical primary routes when setting baseline comprehensive and collision rates.
2. Severe Midwest Weather Patterns
Eastern Iowa experiences intense seasonal weather variations that influence claim frequencies:
- Winter Driving Risks: Sub-zero temperatures, black ice, and heavy snowfalls frequently lead to slide-offs, rear-end collisions, and single-vehicle accidents against guardrails or trees.
- Spring and Summer Severe Weather: Linn County falls within region-wide storm tracks that produce severe thunderstorms, microbursts, and heavy hail. Hail damage claims under comprehensive coverage can easily run into thousands of dollars for dent removal and glass replacement.
3. Credit-Based Insurance Scores
Under rules governed by the Iowa Insurance Division, insurance companies are permitted to use credit-based insurance scores to help determine risk tiers. Statistically, policyholders with higher credit scores demonstrate fewer total claims. A solid credit history can drop your annual auto insurance costs by hundreds of dollars, whereas a poor credit profile can lead to surcharges even if your driving record remains flawless.
4. Vehicle Class, Electronics, and Safety Equipment
The make, model, and year of your car significantly affect insurance pricing. While newer vehicles equipped with Advanced Driver Assistance Systems (ADAS)—such as automatic emergency braking and lane departure warnings—qualify for safety discounts, they are also more expensive to repair. Replacing a bumper integrated with ultrasonic sensors or calibrating a radar-equipped windshield increases collision repair costs, which is reflected in comprehensive and collision coverage pricing.
Comparing National Carriers vs. Midwest Regional Insurers
When shopping for affordable auto insurance in Marion, residents generally choose between large national brands and regional Midwest insurers. Each business model has specific advantages depending on your driving background and coverage needs.
Major National Carriers
- State Farm: Maintains a strong agent footprint throughout Linn County. Often offers competitive rate structures when bundling home and auto insurance, alongside robust mobile app capabilities and driver-tracking discounts.
- Progressive: Known for rate customization tools and competitive options for drivers with minor violations or lapse histories. Offers competitive telematics options.
- GEICO: Direct-to-consumer model that often reduces overhead fees, offering low rates for military members, federal employees, and drivers with clean driving histories.
- Allstate: Provides detailed policy add-ons such as vanishing deductibles and claim satisfaction guarantees, though baseline pricing can be higher unless leveraged with multiple policy discounts.
Midwest Regional Insurers
- Farm Bureau Financial Services: Highly popular throughout rural and suburban Iowa. Requires a membership fee but frequently delivers superior customer service ratings, local claims adjusters based directly in Linn County, and attractive rates for multi-policy owners.
- American Family Insurance: Strong presence across the Upper Midwest with competitive rates for homeowners, broad umbrella policy integration, and tailored youth driver safety programs.
- Auto-Owners Insurance: Sold exclusively through independent insurance agencies in Marion. Consistently ranks high in policyholder satisfaction, financial strength, and multi-policy discount incentives.
- Grinnell Mutual: A Midwest regional carrier specializing in local community underwriting, offering practical auto coverage solutions tailored to Eastern Iowa drivers.
Practical Strategies to Lower Car Insurance Rates in Marion
Achieving long-term savings on auto insurance requires proactive policy management. Implement the following actionable strategies to systematically reduce your annual premium expenses.
- Policy Bundling: 10-25% Off
- Adjust Deductibles: $250 to $1,000
- Utilize Telematics: Track Driving
- Maintain Clean Record: Avoid Claims
1. Bundle Auto with Homeowners or Renters Coverage
Multi-policy bundling remains one of the single most effective ways to drop auto insurance rates. Combining your vehicle insurance with a home, condo, or renters insurance policy routinely nets savings between 10% and 25% across both premiums.
2. Increase Physical Damage Deductibles
If your vehicle carries comprehensive and collision coverages, raising your deductible from $250 or $500 to $1,000 immediately lowers your annual premium. However, ensure you maintain sufficient cash reserves in an emergency fund to cover out-of-pocket costs if an accident occurs.
3. Participate in Usage-Based Telematics Programs
Most insurance providers operating in Iowa offer telematics programs (such as State Farm Drive Safe & Save, Progressive Snapshot, or Allstate Drivewise). These programs utilize smartphone sensors or OBD-II plug-in devices to monitor driving habits—including hard braking, acceleration, speed, nighttime driving, and mobile phone usage. Safe drivers can achieve policy discounts ranging from 10% to 30%.
4. Optimize Discounts for Students and Senior Drivers
- Good Student Discounts: Families in Marion with young drivers attending Linn-Mar High School, Marion High School, or local colleges can qualify for premium reductions of 10% to 15% if the student maintains a "B" grade average (3.0 GPA) or higher.
- Defensive Driving Courses: Drivers aged 55 and older can often complete an state-approved defensive driving course to earn a mandatory discount on liability limits under Iowa insurance guidelines.
5. Review Annual Mileage and Vehicle Usage
If your employment status changes, or if you transition to a remote work schedule, update your policy to reflect a reduced annual mileage limit. Vehicles driven fewer than 7,500 miles annually attract lower collision risk profiles compared to daily highway commuter vehicles.
Minimum vs. Full Coverage: Selecting the Right Protection Tier
Selecting appropriate insurance levels involves balancing your financial vulnerability against monthly budget constraints. The table below outlines how coverage options compare for Marion drivers:
| Coverage Level | Statutory / Typical Limits | Core Included Protections | Ideal Candidate / Use Case | Relative Premium Profile |
|---|---|---|---|---|
| State Minimum Liability | 20/40/15 Liability | Basic bodily injury and property damage for third parties only. | Older vehicles (market value under $4,000) with no lienholders. | Lowest (High personal financial risk) |
| Standard Recommended Liability | 50/100/50 or 100/300/50 Liability + UM/UIM | Elevated third-party liability, plus Uninsured/Underinsured protection for your vehicle occupants. | Commuters taking IA-100 or I-380 with modest personal assets. | Moderate (Balanced protection) |
| Full Coverage (Low Deductible) | 100/300/100 Liability + UM/UIM + Comp/Coll ($250-$500 Deductible) | Complete protection: bodily injury, property damage, hail, deer strikes, vandalism, collision repair. | Financed or leased vehicles; late-model cars; high-asset individuals. | Highest (Comprehensive peace of mind) |
| Full Coverage (High Deductible) | 100/300/100 Liability + UM/UIM + Comp/Coll ($1,000+ Deductible) | Full physical damage protection paired with higher out-of-pocket obligation during a claim. | Drivers wanting full protection who maintain liquid cash reserves for repairs. | Moderate-High (Cost-optimized full coverage) |
Disclaimer: Insurance rules, legal precedents, and personal financial needs vary. Consult a licensed insurance professional or legal advisor regarding specific coverage decisions.
What to Do After a Collision in Marion: Legal and Claim Steps
Knowing how to handle an auto collision in Marion ensures personal safety, regulatory compliance, and smooth insurance claim processing.
- Secure Scene & Check Injuries: Call 911 immediately
- Contact Police Department: Marion PD or Linn County Sheriff
- Exchange & Document Details: Photos, insurance, witness contacts
- Verify Iowa DOT Threshold: File Form 433003 if damage >= $1,500
- Report Claim to Insurer: Contact provider's claims department
1. Immediately Contact Local Law Enforcement
If an accident results in bodily injury, death, or noticeable vehicle damage, call 911. Crashes occurring within Marion city limits are handled by the Marion Police Department, while incidents on rural outer roads fall under the jurisdiction of the Linn County Sheriff’s Office or the Iowa State Patrol. An official police report provides critical evidence during insurance fault determinations.
2. Document the Collision Scene Thoroughly
- Exchange driver names, addresses, phone numbers, driver’s license details, and insurance policy numbers.
- Photograph all involved vehicles from multiple angles, showing point of impact, license plates, road conditions, skid marks, and weather factors.
- Obtain contact info from independent eyewitnesses before they leave the scene.
- Avoid making statements regarding fault or apologizing for the incident, as liability is determined after formal investigation.
3. File the Iowa Driver's Confidential Report (Form 433003)
Under Iowa Code § 321.266, drivers involved in an accident within Iowa resulting in injury, death, or total property damage equal to or exceeding $1,500 must file a Driver's Confidential Report of Motor Vehicle Accident (Form 433003) with the Iowa Department of Transportation within 72 hours if law enforcement does not submit an official report on their behalf.
Step-by-Step Guide to Shopping for Auto Insurance in Marion
To get the best rate on auto insurance, follow this systematic approach:
- Gather Key Information: Pull together your current policy declaration page, driver's license numbers for all household members, Vehicle Identification Numbers (VINs), and exact commuting mileage.
- Evaluate Coverage Needs: Decide whether your vehicle requires full coverage (collision and comprehensive) or liability-only based on market value, outstanding vehicle loans, and your asset exposure.
- Request Quotes from Multiple Insurers: Obtain quotes from at least two major national carriers and two Midwest regional insurers to get a broad view of market rates.
- Review Quote Details: Ensure liability limits, UM/UIM coverages, and deductibles are identical across all quotes to perform an accurate comparison.
- Verify Licensing: Ensure the agent or broker is active and registered with the Iowa Insurance Division.
- Cancel Old Policies Properly: Once your new policy takes effect, issue a written cancellation request to your previous insurer to prevent gaps in coverage or unnecessary billing.
Frequently Asked Questions
What is the average cost of auto insurance in Marion, IA?
Auto insurance rates in Marion fall below national averages due to Iowa’s overall favorable loss environment. However, exact premiums vary based on personal credit scores, driving records, vehicle age, and selected coverage levels. Drivers with clean records carrying state minimum liability generally pay significantly less than those choosing full coverage policies with low deductibles on new vehicles.
Is Iowa's 20/40/15 minimum coverage sufficient for daily driving?
While 20/40/15 liability limits satisfy state legal requirements, they are rarely sufficient to protect drivers against major financial losses. A single accident involving multiple vehicles or emergency room care can exceed $15,000 in property damage or $20,000 in medical bills. Insurance experts typically recommend carrying at least 100/300/50 liability coverage.
Does standard car insurance cover damage from hail or deer strikes in Linn County?
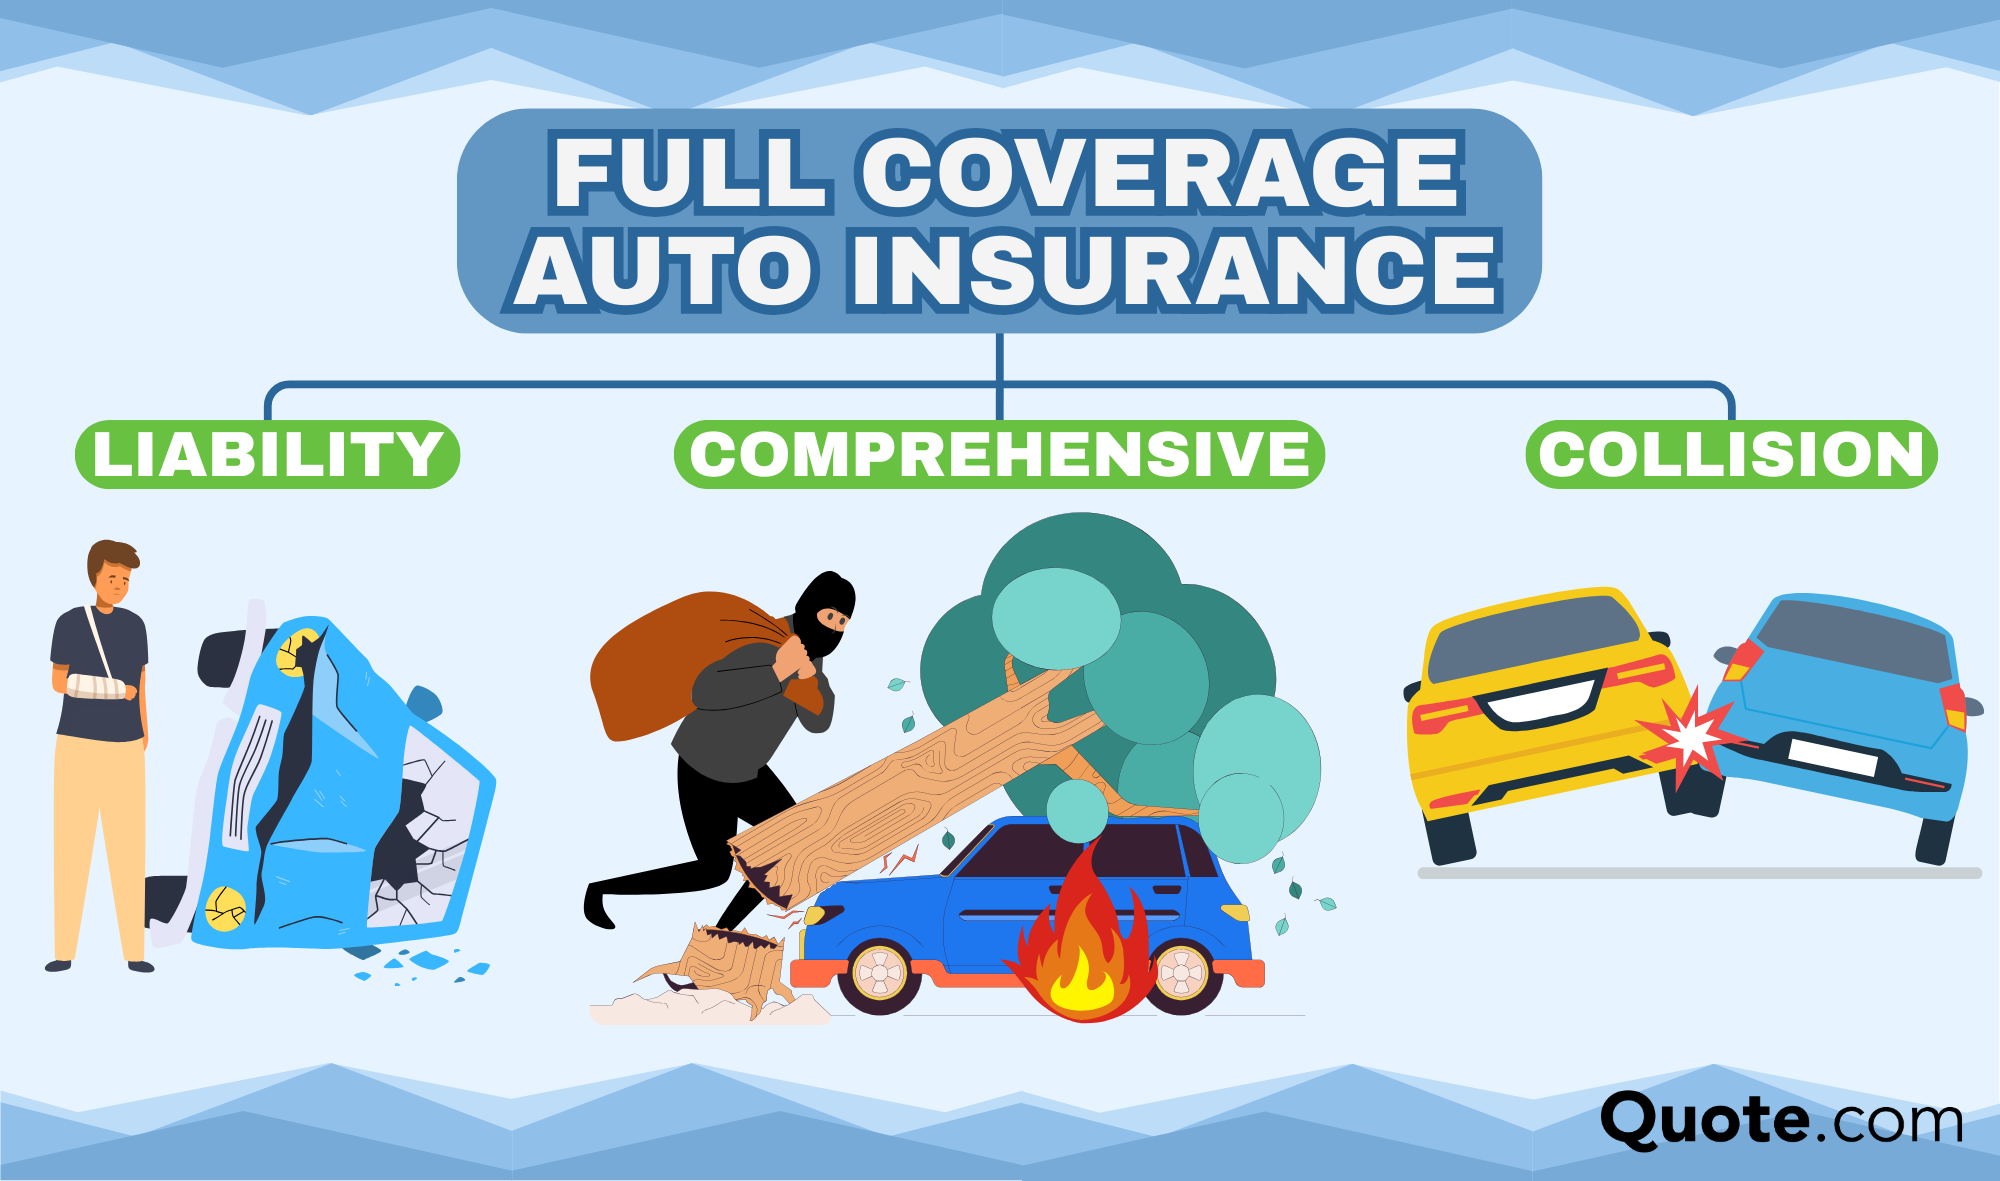
Yes, but only if your policy includes comprehensive coverage. Comprehensive insurance covers non-collision damage, including hail, falling tree limbs, windstorm damage, theft, vandalism, and collisions with animals such as deer. Minimum liability-only policies do not cover these occurrences.
Can an insurance company use my credit score to set rates in Iowa?
Yes. Under Iowa law, insurance companies can use credit-based insurance scores to calculate auto insurance rates. Maintaining a strong credit history can qualify you for lower insurance tiers, while poor credit scores may increase your rates.
What happens if I get hit by an uninsured driver in Marion?
If you have Uninsured Motorist (UM) coverage on your policy, your insurance provider pays for medical expenses, lost earnings, and related damages up to your policy limits. If you opted out of UM coverage in writing, you may have to cover your own medical bills or sue the uninsured driver directly to recover damages.
Next Steps for Marion Drivers
To lower your auto insurance rates while ensuring full protection on the road, start by gathering your current insurance declarations page. Check your existing liability limits, deductible amounts, and active discounts. Reach out to an independent insurance agent in Marion or request direct quotes online from regional and national carriers. Comparing options every one to two years ensures your coverage matches your driving habits, vehicle value, and financial situation.