AARP Life Insurance telesales refers to the specialized phone-based distribution channel through which AARP members purchase life insurance policies underwritten by New York Life Insurance Company. This system allows seniors to receive quotes, complete applications, and secure coverage without in-person medical exams, utilizing simplified underwriting and voice-signature technology to streamline the enrollment process.
In 2026, the landscape of senior-focused financial services is increasingly dominated by direct-to-consumer models. AARP Life Insurance, a program provided by New York Life, remains one of the most prominent examples of this shift. Telesales—the practice of selling products over the phone—is the primary engine behind this program’s accessibility. Whether you are a consumer looking to protect your family or a licensed professional considering a career in this niche, understanding the mechanics of AARP Life Insurance telesales is essential.
The Strategic Partnership: AARP and New York Life
The foundation of AARP Life Insurance telesales is the long-standing exclusive partnership between AARP and New York Life Insurance Company. While AARP is a non-profit interest group, it does not issue insurance policies itself. Instead, it endorses New York Life to provide coverage specifically designed for its members.
This relationship creates a unique telesales environment. Unlike "cold-calling" centers, AARP telesales operations primarily handle "warm" leads—individuals who have responded to direct mail, television advertisements, or digital prompts. In 2026, the integration of these marketing channels means that when a member calls the AARP Life Insurance program, the telesales agent often has immediate access to the member’s historical engagement, allowing for a more personalized and efficient consultation.
The Role of the Telesales Center
Most AARP Life Insurance telesales operations are managed through dedicated call centers, often located in hubs like Tampa, Florida, or Dallas, Texas, though remote work for licensed agents has become a standard offering in 2026. These centers are highly regulated and focus on high-volume, high-quality interactions. The goal is to move a caller from inquiry to "policy in force" in a single session whenever possible.
The Consumer Experience: How the Telesales Process Works
For the AARP member, the telesales process is designed to be low-friction. Because many seniors prefer the human touch of a conversation over a purely digital application, the phone remains a critical tool.
1. The Initial Consultation and Needs Analysis
When a member calls the telesales line, the agent begins with a needs analysis. This isn't just about price; it’s about determining which of the three main AARP products fits the member’s financial goals. The agent asks questions about funeral costs, outstanding debts, and legacy planning. In 2026, agents use sophisticated CRM (Customer Relationship Management) tools to help calculate coverage needs in real-time based on the member’s specific geographic cost of living.
2. Simplified Underwriting via Phone
One of the hallmarks of AARP Life Insurance telesales is the absence of a physical medical exam. Instead, agents conduct "Simplified Issue" underwriting over the phone. This involves:
- Health Questionnaires: A series of "Yes/No" questions regarding major medical conditions (e.g., cancer, heart disease, stroke).
- Database Checks: With the caller’s consent, the agent’s system checks prescription drug histories and MIB (formerly Medical Information Bureau) records instantly.
- Immediate Decisioning: In many cases, the agent can inform the caller if they are approved before the phone call ends.
3. Voice Signatures and E-Delivery
To comply with legal standards in 2026, telesales agents utilize voice signature technology. The agent reads a legal disclosure, and the member’s verbal "I agree" serves as a binding signature. Following the call, the policy documents are typically delivered via a secure email portal, though paper copies remain an option for those who prefer them.
Career Insights: Working in AARP Life Insurance Telesales
For insurance professionals, a role in AARP telesales is often seen as a "captive" agent position. This means the agent represents only New York Life products for AARP members.
Requirements and Licensing
To work in this field, an individual must hold a valid Life and Health Insurance License in their resident state. Furthermore, because these centers handle calls from across the country, agents must often be "non-resident licensed" in dozens of other states. Most large telesales organizations handle the administrative burden and cost of these additional licenses for their employees.
Training and Compliance
Training for AARP telesales is rigorous. Beyond learning the product specifications, agents must master the "Senior Sensitivity" training. This involves understanding the cognitive and emotional needs of the 50+ demographic. Compliance is also a major focus; every call is recorded, and "Quality Assurance" (QA) teams monitor for script adherence and ethical selling practices. In 2026, AI-driven monitoring tools provide real-time feedback to agents to ensure they are meeting both regulatory and brand standards.
Compensation Structures
Most telesales roles offer a base salary plus commission or performance-based bonuses. Unlike independent agents who must pay for their own leads, AARP telesales agents are provided with a steady stream of inbound callers. This trade-off—lower commission per policy but higher volume and no lead costs—makes it an attractive path for those who prefer a structured environment over the "hustle" of independent sales.
Product Portfolio Sold via Telesales
The AARP Life Insurance program offers three primary products through its telesales channel. Understanding the nuances of these products is vital for both the agent and the consumer.
| Product Name | Policy Type | Max Coverage (Typical) | Medical Exam? | Benefit Structure |
|---|---|---|---|---|
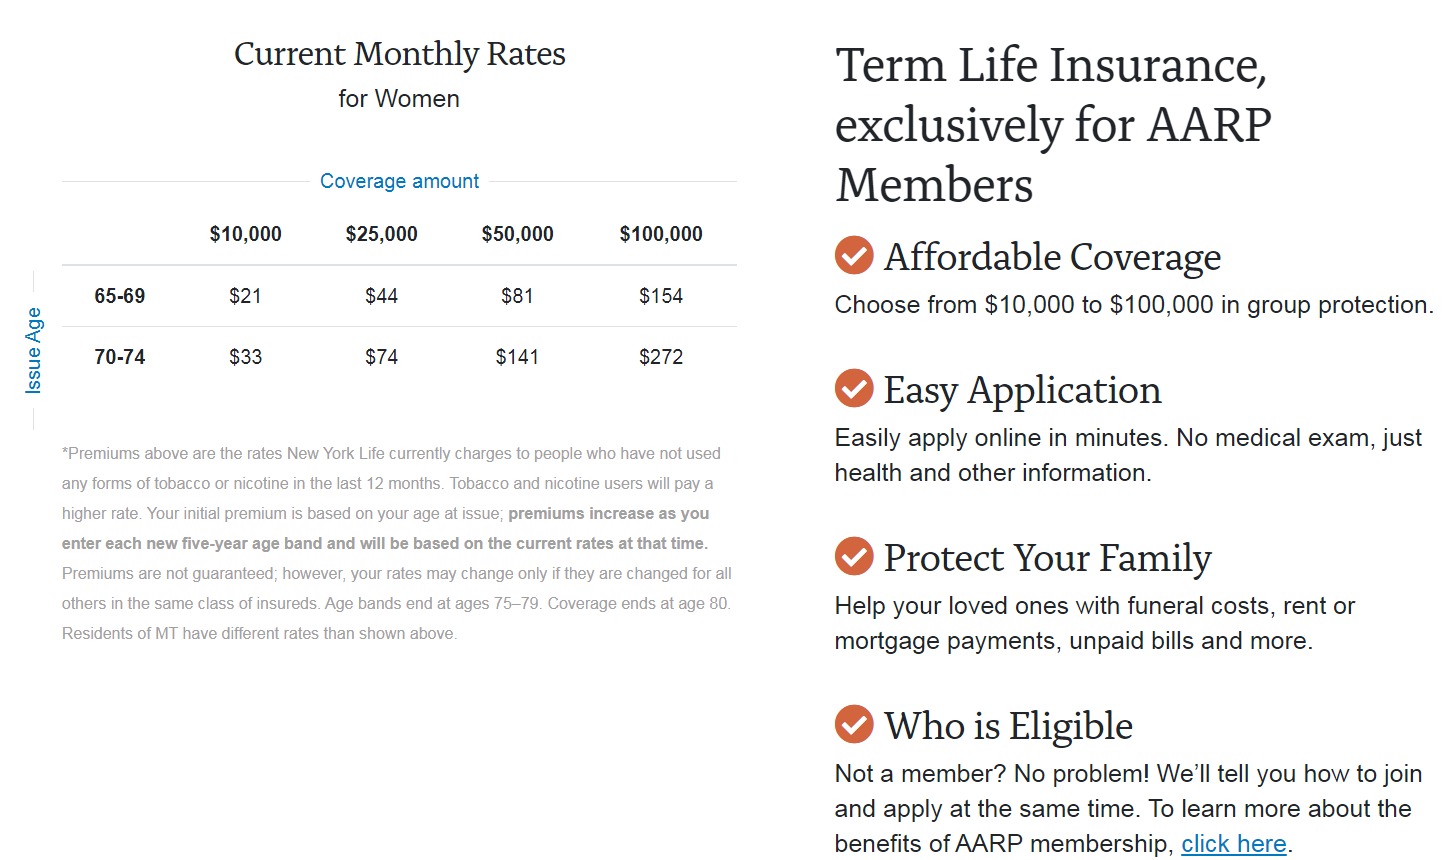
| AARP Term Life | Group Term | Up to $150,000 | No (Health Questions Only) | Increases in 5-year age bands |
| AARP Whole Life | Permanent | Up to $50,000 | No (Health Questions Only) | Fixed premiums; builds cash value |
| Guaranteed Acceptance | Whole Life | Up to $25,000 | No (None) | Graded benefit for first 2 years |
AARP Term Life Insurance
This is the most common product sold via telesales for members who want higher coverage amounts at a lower initial cost. It is designed to cover specific periods of risk, such as a remaining mortgage or the years until a spouse reaches retirement age. However, agents must be transparent that the premiums increase every five years as the member moves into a new age bracket.
AARP Permanent Whole Life Insurance
For those looking for final expense coverage, the Whole Life product is a staple of telesales. The premium is locked in at the age of purchase and never increases. This provides peace of mind for seniors on a fixed income. The cash value component also allows for a small level of "living benefits" should the policyholder need to borrow against the policy.
AARP Guaranteed Acceptance Life Insurance
This is a "last resort" product for members with significant health issues who cannot pass the simplified underwriting of the other plans. In the telesales environment, if a member is denied for Term or Whole Life due to health questions, the agent will often pivot to this product. It guarantees acceptance, but it features a "graded death benefit," meaning if the insured dies of natural causes within the first two years, the beneficiaries receive only the premiums paid plus interest.
Technical and Regulatory Considerations in 2026
The telesales environment is governed by several layers of regulation. In 2026, these have become more stringent to protect seniors from fraud and aggressive sales tactics.
- TCPA Compliance: The Telephone Consumer Protection Act regulates how and when agents can call. Since AARP telesales relies heavily on inbound calls or "consent-to-call" leads, maintaining strict records of consent is paramount.
- HIPAA and Privacy: Agents handle sensitive health information over the phone. Telesales systems in 2026 use end-to-end encryption and strict access controls to ensure that a member’s medical history is never compromised.
- State-Specific Variations: Life insurance is regulated at the state level. An agent selling to a member in New York must follow different disclosure rules than when selling to a member in Texas. The telesales software automatically adjusts the script based on the caller's area code and address.
Common Challenges in Telesales
While the system is efficient, it is not without challenges. From the consumer side, the "no-exam" nature of the products often means that premiums are slightly higher than a fully underwritten policy from another carrier. This is because the insurance company is taking on more risk by not seeing a full medical profile.
From the agent side, "call reluctance" isn't the issue; rather, it is "script fatigue." Maintaining a high level of empathy and energy while repeating the same disclosures and product explanations 40 to 50 times a day requires significant mental resilience. Additionally, the shift toward digital-first seniors in 2026 means that telesales agents must be tech-savvy enough to walk a member through an email confirmation or a mobile app while staying on the phone.
Frequently Asked Questions
Can I get AARP Life Insurance over the phone if I have a pre-existing condition?
Yes. Depending on the severity of the condition, you may qualify for the Term or Whole Life products through simplified underwriting. If those are not an option, the AARP Guaranteed Acceptance Life Insurance is specifically designed for those with serious health issues, as it requires no health questions at all.
Is the price higher if I buy through a telesales agent instead of online?
Generally, no. The premium rates for AARP Life Insurance are standardized based on your age, gender (in most states), and the amount of coverage you select. Whether you complete the application yourself online or work with a telesales agent, the cost for the same policy should be identical.
How do I know the person on the phone is a legitimate AARP/New York Life representative?
Legitimate agents will never ask for your Social Security number or bank details before providing a quote and explaining the policy. You can verify a representative by asking for their National Producer Number (NPN) and checking it against the NIPR database. Additionally, you should only call the official numbers found on the AARP or New York Life websites.
Does AARP Life Insurance require a medical exam if I buy it over the phone?
One of the primary advantages of the AARP telesales program is that none of the core life insurance products—Term, Whole Life, or Guaranteed Acceptance—require a physical medical exam or blood work. Eligibility is determined through health questions and database searches conducted during the call.
What happens after the telesales call ends?
Once the call is finished and the voice signature is recorded, the application is submitted for final review. Most applicants receive a confirmation via email within minutes. If approved, the policy becomes "in force" as soon as the first premium is processed. You will typically receive a physical policy packet in the mail within 7 to 10 business days.
Final Recommendation
For AARP members seeking life insurance in 2026, the telesales channel offers a balanced mix of convenience and professional guidance. It is best suited for individuals who want to secure coverage quickly without the hassle of a medical exam and who value the opportunity to ask a licensed professional specific questions about their policy.
If you choose this route, prepare by having a list of your current medications and your desired coverage amount ready. For those interested in a career, AARP Life Insurance telesales remains a stable and rewarding path for licensed agents who excel in a structured, high-volume, and empathetic sales environment. Always ensure you are speaking with an authorized New York Life representative and carefully review the "graded benefit" limitations if you are applying for a guaranteed acceptance policy.