The assets-to-net-worth ratio is a financial metric used to evaluate an individual's financial leverage and stability by dividing total assets by total net worth. A lower ratio indicates greater financial independence and lower reliance on debt, whereas a higher ratio reveals that a significant portion of an individual's wealth is financed through liabilities.
Introduction to Financial Metrics and Net Worth
Evaluating personal financial health requires moving beyond simple income tracking to examine the underlying structure of one's wealth. While income dictates cash flow, assets, liabilities, and net worth determine long-term stability and resilience against economic shocks. Within personal finance and wealth management, several foundational metrics help quantify financial standing, ranging from the debt-to-income ratio to the savings rate. However, evaluating the composition of your wealth requires specialized tools that look closely at what you own versus what you owe.
The assets-to-net-worth ratio is a critical diagnostic instrument borrowed from corporate finance and applied to personal balance sheets. It measures the degree of financial leverage an individual employs. By understanding how this ratio functions, you can assess whether your financial foundation is built on solid equity or inflated by excessive borrowing. This comprehensive guide explores the mechanics of the assets-to-net-worth ratio formula, how to calculate it accurately, what the resulting numbers signify, and how to use this insight to optimize your financial strategy.
Defining the Core Components: Assets, Liabilities, and Net Worth
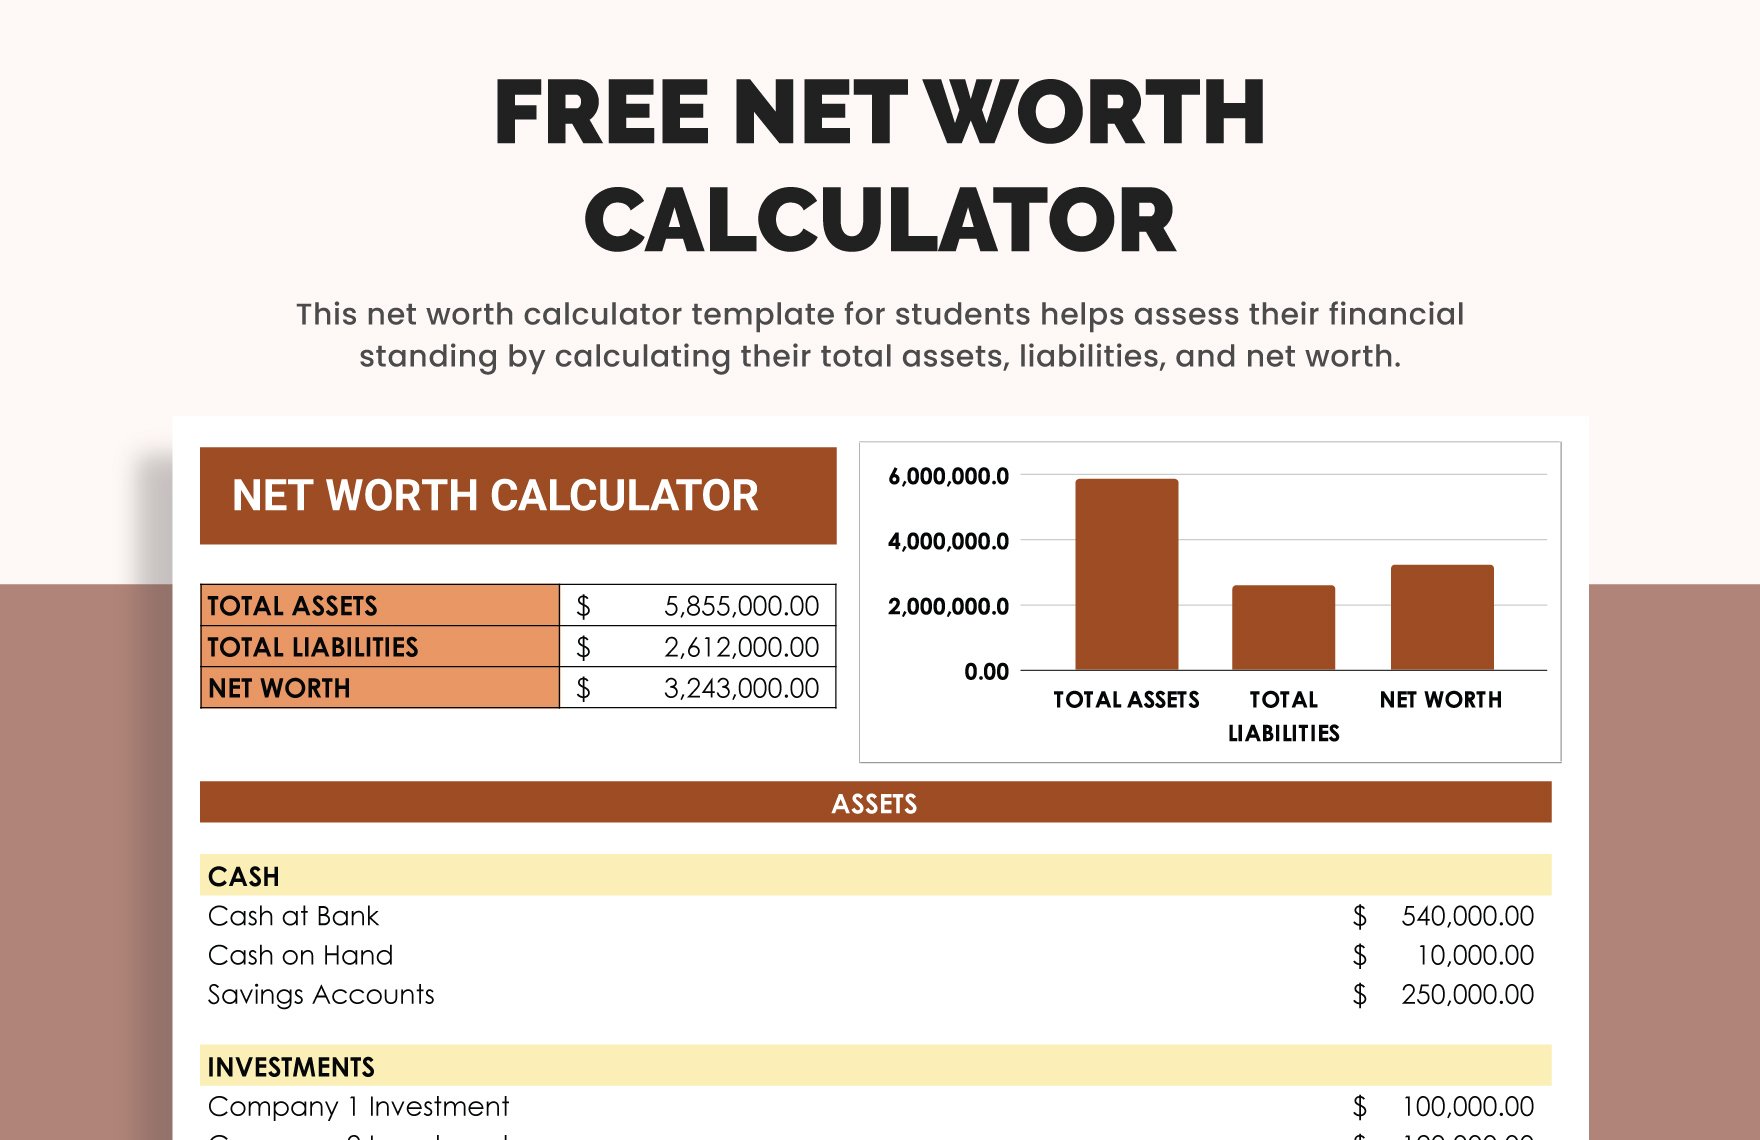
Before applying any formula, you must establish a precise inventory of your financial life through a personal balance sheet. The assets-to-net-worth ratio relies on two primary variables: total assets and net worth. Net worth itself is derived from subtracting total liabilities from total assets. Understanding the precise boundaries of these categories ensures the mathematical accuracy of your calculations.
Total Assets
Total assets encompass everything of economic value that you own. In personal finance, assets are typically divided into liquid, investment, and tangible categories:
- Liquid Assets: Cash, checking accounts, savings accounts, money market funds, and certificates of deposit that can be converted to cash immediately without loss of value.
- Investment Assets: Stocks, bonds, mutual funds, exchange-traded funds (ETFs), retirement accounts (such as 401(k) or IRA accounts), and the cash value of life insurance policies.
- Tangible (Fixed) Assets: Physical property including primary residences, real estate investments, vehicles, boats, valuable jewelry, art, and collectibles.
Total Liabilities
Liabilities represent all outstanding debts and financial obligations owed to external parties. These include short-term debts like credit card balances and personal loans, as well as long-term obligations such as mortgages, auto loans, and student loans.
Net Worth
Net worth is the residual amount remaining when you subtract total liabilities from total assets. It represents your true economic worth at a specific point in time. $$\text{Net Worth} = \text{Total Assets} - \text{Total Liabilities}$$
The Assets to Net Worth Ratio Formula
The mathematical expression for this metric is straightforward, yet its interpretation requires deep financial context. The formula is written as:
$$\text{Assets-to-Net-Worth Ratio} = \frac{\text{Total Assets}}{\text{Net Worth}}$$
Alternatively, because Net Worth equals Total Assets minus Total Liabilities, the formula can be expressed relative to liabilities:
$$\text{Assets-to-Net-Worth Ratio} = \frac{\text{Total Assets}}{\text{Total Assets} - \text{Total Liabilities}}$$
Because total assets are always equal to or greater than net worth for any individual with zero or positive debt, the absolute minimum value for this ratio is $1.0$ (or $100%$). A ratio of $1.0$ signifies that an individual has zero liabilities; every single dollar of assets is owned outright with no debt encumbering it.
Step-by-Step Calculation Example
To illustrate how the formula operates in practice, consider a hypothetical individual, Jane, whose financial profile is detailed below:
- Checking and Savings Accounts: $25,000
- Retirement Accounts (401(k), IRA): $175,000
- Primary Residence Market Value: $400,000
- Vehicle Market Value: $25,000
- Total Assets: $25,000 + $175,000 + $400,000 + $25,000 = \mathbf{$625,000}$
- Mortgage Balance: $300,000
- Auto Loan Balance: $10,000
- Credit Card Debt: $5,000
- Total Liabilities: $300,000 + $10,000 + $5,000 = \mathbf{$315,000}$
- Net Worth: $$625,000 - $315,000 = \mathbf{$310,000}$
Now, apply the assets-to-net-worth ratio formula:
$$\text{Ratio} = \frac{$625,000}{$310,000} = 2.016$$
Jane’s assets-to-net-worth ratio is approximately $2.02$. This means that for every dollar of actual net worth she possesses, she holds approximately two dollars in total assets, with the difference financed by debt.
Interpreting the Results: What Your Ratio Reveals
Evaluating the resulting number requires understanding how financial leverage impacts risk and return. A high ratio indicates that a large portion of assets is supported by borrowed money, amplifying both potential gains and potential financial distress. A low ratio indicates conservative financial management with high structural stability.
The Spectrum of Financial Leverage
| Ratio Range | Financial Interpretation | Risk Profile | Typical Scenario |
|---|---|---|---|
| 1.0 | Absolute debt-free ownership | Zero financial leverage | Complete financial independence; all assets owned outright. |
| 1.1 to 1.5 | Low leverage, high equity | Minimal risk | Established homeowners with nearly paid-off mortgages or conservative investors. |
| 1.6 to 2.5 | Moderate leverage | Balanced risk | Typical middle-age households with standard mortgages and healthy investment portfolios. |
| 2.6 to 4.0 | High leverage | Elevated risk | Recent homebuyers with large mortgages or individuals utilizing significant investment margin. |
| Above 4.0 | Distressed or over-leveraged | Severe risk | Heavy debt relative to assets; vulnerable to income loss or asset depreciation. |
When the ratio climbs significantly above $2.0$, it typically reflects a major capital-intensive purchase, such as a recently acquired real estate property with a high loan-to-value mortgage. While utilizing leverage to buy real estate is a standard wealth-building strategy, monitoring the ratio ensures that the debt remains manageable relative to total economic holdings.
Why the Assets to Net Worth Ratio Matters
While many financial calculators focus exclusively on monthly cash flow or retirement milestones, the assets-to-net-worth ratio provides structural insight into your balance sheet. Understanding this metric offers several distinct advantages for personal financial planning:
Assessing Solvency and Risk Exposure
Solvency is the ability to cover all long-term debts and financial obligations if all assets were liquidated. A high assets-to-net-worth ratio warns that a sudden drop in asset values—such as a real estate market correction or a stock market downturn—could wipe out your net worth entirely, plunging you into technical insolvency where liabilities exceed assets.
Tracking Long-Term Financial Evolution
Over the course of a lifetime, an individual's assets-to-net-worth ratio naturally shifts. In early adulthood, individuals often exhibit high ratios due to student loans and first-time home mortgages relative to a small initial asset base. As careers progress and debts are amortized while investments compound, the ratio should steadily decline toward $1.0$. Monitoring this trajectory ensures your financial life is moving in the right direction.
Enhancing Loan and Credit Eligibility
Lenders evaluate personal balance sheets when underwriting major commercial loans, business lines of credit, or jumbo mortgages. A balanced assets-to-net-worth ratio signals to financial institutions that you manage leverage responsibly, making you a more attractive candidate for favorable interest rates.
Common Pitfalls in Calculating Assets and Net Worth
Inaccurate calculations distort the assets-to-net-worth ratio, leading to false confidence or unnecessary alarm. Avoiding common accounting errors ensures your financial diagnostics remain reliable.
Overestimating Asset Values
A frequent mistake is assigning emotional or inflated values to tangible assets. Personal property, used vehicles, and specialty collectibles rarely appreciate at market rates. Using original purchase prices rather than current liquidation or fair market value artificially inflates total assets, throwing off the ratio. When valuing real estate, rely on recent comparable sales or professional appraisals rather than optimistic personal estimates.
Omitting Hidden Liabilities
Failing to account for all liabilities results in an inaccurate net worth figure, which in turn skews the ratio. Ensure you include deferred obligations, such as taxes owed on traditional retirement account withdrawals, capital gains taxes on taxable brokerage accounts, and personal loans from family members.
Misinterpreting Liquid versus Illiquid Assets
Even if a ratio appears healthy, the composition of the underlying assets matters. An individual may have a low ratio of $1.3$, but if $95%$ of those assets are tied up in an illiquid primary residence and locked retirement accounts, cash flow crises can still occur during an emergency. Always analyze asset liquidity alongside the primary ratio.
Strategies to Improve an Unfavorable Ratio
If your calculations reveal an elevated assets-to-net-worth ratio—indicating heavy reliance on debt—you can take systematic steps to strengthen your balance sheet over time.
Accelerating Liability Paydown
The most direct way to lower the ratio is to reduce total liabilities while keeping asset values stable or growing. Prioritize high-interest consumer debt, such as credit cards and personal loans, before tackling low-interest amortized debt like mortgages. Every dollar paid toward principal reduces total liabilities dollar-for-dollar while increasing net worth by the exact same amount.
Strategic Asset Accumulation
Simultaneously building high-quality, cash-producing or appreciating assets shifts the numerator and denominator in your favor. Focus on accumulating liquid emergency reserves and diversified investment vehicles that outpace inflation.
Refined Budgeting and Cash Flow Management
Implementing disciplined budgeting frameworks ensures that discretionary income is systematically funneled into debt reduction and asset acquisition rather than lifestyle inflation. Reviewing your personal balance sheet on a semi-annual or annual basis helps maintain alignment with your long-term financial targets.
Frequently Asked Questions
What is the ideal assets to net worth ratio?
There is no single universal ideal, as the optimal ratio depends on your life stage. However, a ratio between $1.0$ and $2.0$ is generally considered healthy for established adults, reflecting prudent use of mortgages or loans balanced by substantial equity. Younger individuals early in their careers often maintain higher ratios due to student loans and initial mortgages.
How does a mortgage affect the assets to net worth ratio?
A mortgage increases both total assets (via the property's market value) and total liabilities (via the loan balance). Because the asset value is typically larger than the initial loan balance, taking out a mortgage actually increases the assets-to-net-worth ratio, introducing financial leverage into your balance sheet.
How often should I calculate my assets to net worth ratio?
Calculating this ratio annually or semi-annually is sufficient for most individuals. Frequent monthly tracking is generally unnecessary because tangible asset values, such as real estate, do not fluctuate daily like liquid stock portfolios.
Does a low assets to net worth ratio always mean financial success?
While a low ratio indicates minimal debt, context is vital. An unemployed individual with zero assets and zero liabilities has a ratio of $1.0$ or an undefined balance, yet lacks financial security. The ratio must be evaluated alongside absolute net worth and cash flow generation.
Conclusion
The assets-to-net-worth ratio formula serves as an indispensable diagnostic tool for evaluating personal financial leverage, structural stability, and risk exposure. By dividing total assets by total net worth, you gain a clear, mathematical picture of how heavily your wealth is dependent on borrowed capital. While moderate leverage can accelerate wealth accumulation through strategic real estate or business investments, excessive leverage leaves a household vulnerable to economic downturns. Regularly auditing your balance sheet, maintaining realistic asset valuations, and systematically reducing liabilities will keep your ratio at a healthy level, supporting long-term financial independence.