To obtain ALPA term life insurance quotes in 2026, members should access the ALPA Member Insurance Program portal, typically underwritten by New York Life Insurance Company. Rates are based on your age, tobacco status, and desired coverage amount. Members can choose between Group Term Life, which offers flexible annual increases, and Level Term Life, which locks in premiums for 10 or 20 years.
The Air Line Pilots Association, International (ALPA) provides a specialized suite of insurance products designed specifically for the professional pilot. Because commercial aviation involves unique risks and stringent medical requirements, standard retail life insurance policies can sometimes be difficult to navigate or may include restrictive clauses. ALPA-sponsored plans are negotiated collectively to provide competitive rates and coverage terms that reflect the professional standards of the industry.
Understanding the ALPA Member Insurance Program
As of 2026, ALPA continues to leverage the collective bargaining power of over 70,000 pilots to offer insurance products that are often more accessible than individual retail policies. The core of their life insurance offering is divided into two primary categories: Group Term Life and Level Term Life.
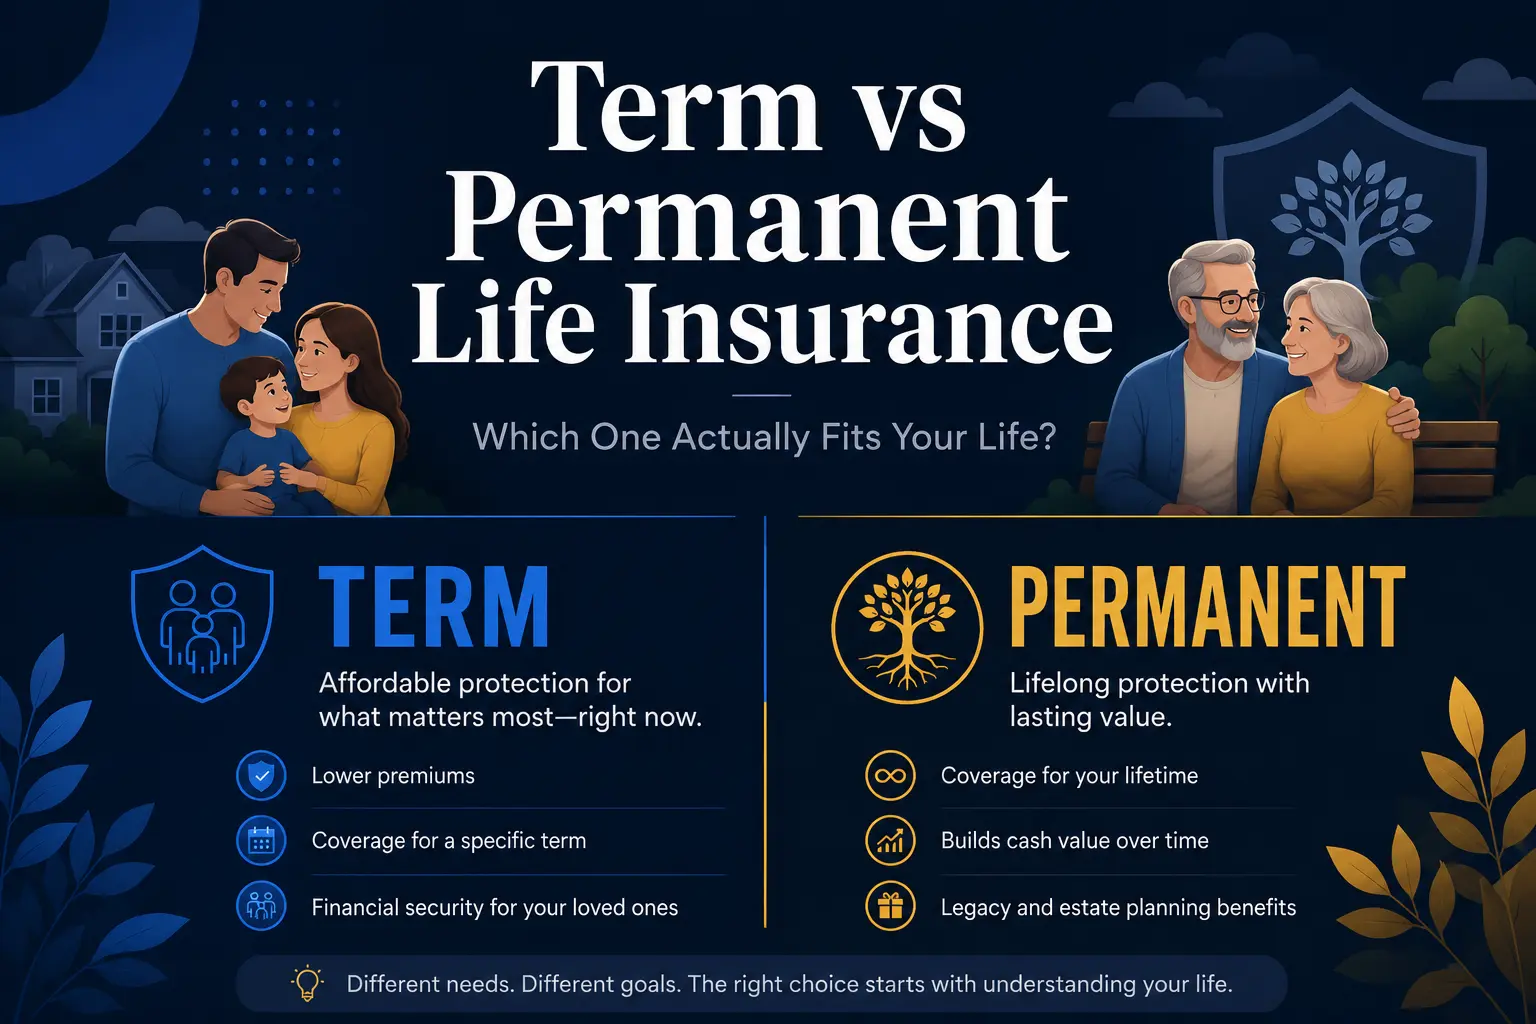
The Group Term Life Insurance plan is designed for maximum flexibility. It allows members to adjust their coverage levels as their career progresses and their family needs change. Premiums for this plan are typically "age-banded," meaning the cost increases as the pilot enters new five-year age brackets (e.g., 30–34, 35–39). This is often the most affordable way to secure high levels of coverage early in a career.
The Level Term Life Insurance plan (available in 10-year and 20-year increments) is preferred by pilots who want long-term financial predictability. Once approved, the premium remains the same for the duration of the term. This protects the member against price hikes as they age or if their health status changes during the term.
Eligibility and Membership Requirements
Before requesting a quote, it is essential to verify eligibility. ALPA insurance is not a public product; it is a benefit of membership.
- Active Membership: You must be an active member in good standing with ALPA. This includes pilots at various major, national, and regional carriers represented by the union.
- Apprentice Members: Many plans are also open to apprentice members who have recently joined an ALPA-represented airline.
- Spousal Coverage: ALPA typically allows members to request quotes for their spouses or domestic partners. The rates for spouses are often similar to the member rates, though they are subject to separate underwriting.
- Geographic Limits: While ALPA is international, the insurance programs are often specific to members residing in the United States and Canada. Members based in other jurisdictions should verify specific policy availability through the ALPA Member Insurance website.
How to Obtain and Evaluate ALPA Term Life Quotes
In 2026, the process for obtaining a quote is primarily digital, though paper applications remain available for specific administrative needs.
Step 1: Access the Online Portal
Members should log in to the ALPA secure portal using their member ID. The insurance section provides a "Quick Quote" calculator. This tool allows you to input your age, tobacco usage, and the desired face amount (the total payout) to see an estimated monthly or semi-annual premium.
Step 2: Choose Your Coverage Amount
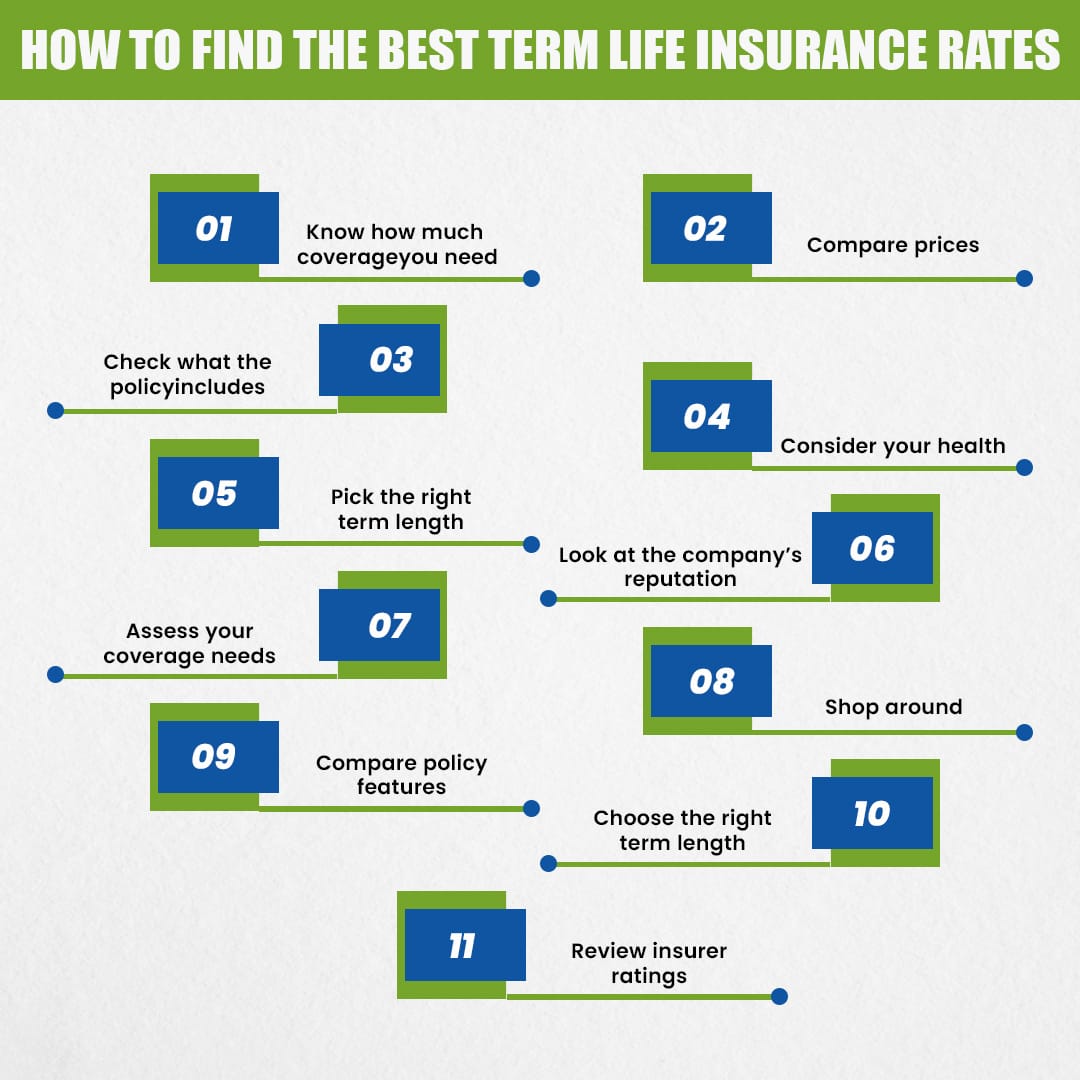
ALPA plans frequently offer coverage in increments of $10,000, with maximum limits often reaching $1,000,000 or more, depending on the specific carrier agreement for 2026. When evaluating quotes, consider your total debt (mortgages, car loans), future education costs for children, and income replacement needs for your survivors.
Step 3: Determine the Term Length
If you opt for Level Term, you must decide between a 10-year or 20-year period. A 20-year term will have a higher monthly quote than a 10-year term, but it provides longer protection against rising insurance costs. If you are a senior captain nearing retirement, a 10-year term or the standard Group Term plan may be more cost-effective.
Step 4: Review Underwriting Requirements
Quotes provided by the calculator are "tentative." The final price is determined after underwriting. For lower coverage amounts, ALPA often offers Simplified Issue underwriting, which may only require a health questionnaire. For higher amounts (typically over $250,000 or $500,000), a full medical exam—including blood work and a physical—may be required.
Factors Influencing Quote Pricing
Several variables dictate the final cost of an ALPA term life insurance policy. Understanding these helps in comparing ALPA quotes against other market options.
- Attained Age: Life insurance is fundamentally a math problem based on mortality tables. The older you are at the time of application, the higher the quote.
- Tobacco Status: This is a significant differentiator. Smoker rates are substantially higher than non-smoker rates. ALPA definitions of tobacco use usually include cigarettes, cigars, and sometimes nicotine replacement therapies.
- Health Classification: During underwriting, you will be assigned a risk class (e.g., Preferred, Standard). Pilots with pristine medical records and first-class medical certificates often qualify for the most favorable rates.
- Aviation Specifics: While being a commercial pilot is generally covered under standard rates in ALPA plans, certain types of high-risk flying (like experimental testing or air racing) might require specific disclosures that could impact a quote.
Comparison of ALPA Term Life Options (2026)
| Feature | Group Term Life | 10-Year Level Term | 20-Year Level Term |
|---|---|---|---|
| Premium Structure | Increases every 5 years | Fixed for 10 years | Fixed for 20 years |
| Max Coverage | Up to $1M+ | Up to $1M+ | Up to $1M+ |
| Portability | Continues if you leave ALPA* | Continues if you leave ALPA* | Continues if you leave ALPA* |
| Medical Exam | Often waived for low amounts | Usually required | Usually required |
| Best For | Flexibility and low initial cost | Mid-career stability | Long-term family protection |
| Renewal | Annual | Renewable at higher rates | Renewable at higher rates |
*Subject to policy terms regarding "portability" or "conversion" to individual policies.
The Role of Medical Underwriting for Pilots
One of the most common questions regarding ALPA term life quotes involves the relationship between the insurance medical exam and the FAA Medical Certificate (First, Second, or Third Class).
It is a common misconception that holding a valid FAA First Class Medical automatically qualifies a pilot for "Preferred" insurance rates. While the FAA is concerned with your fitness to fly right now, life insurance underwriters are concerned with your long-term mortality risk. Conditions that are "waivable" by the FAA via a Special Issuance (such as well-controlled hypertension or certain sleep apnea cases) might still result in a "Standard" rather than "Preferred" rating for life insurance quotes.
When you apply for an ALPA policy, you must be transparent about your medical history. The underwriter, typically New York Life, will review your MIB (Medical Information Bureau) report and may request records from your Aviation Medical Examiner (AME).
Limitations and Exclusions
While ALPA term life insurance is robust, it is not without limitations. Pilots should carefully review the "fine print" in their quotes:
- Suicide Clause: Most policies have a two-year suicide exclusion period from the date the policy becomes effective.
- War/Terrorism Exclusions: Some group policies may have specific language regarding active military duty or acts of war, though commercial flight operations are typically fully covered.
- Age Limits: Many term life policies have an expiration age (often 70, 75, or 80). After this age, the policy may terminate or convert to a much more expensive whole-life option.
- Disability Waivers: Some quotes include a "Waiver of Premium" rider. This means if you become totally disabled and cannot work as a pilot, the insurance company will pay your premiums for you. This is a highly recommended add-on for professional pilots.
Supplemental Coverages to Consider
When requesting life insurance quotes, ALPA members are often presented with additional options that complement term life coverage:
Accidental Death & Dismemberment (AD&D)
AD&D provides an additional payout if your death is the result of an accident. It also provides "living benefits" if you lose a limb, your sight, or your hearing. For pilots, AD&D is often very affordable because it does not cover deaths from natural causes (illness), which are the primary risks for insurance companies.
Critical Illness Insurance
This provides a lump-sum payment if you are diagnosed with a specific covered condition, such as cancer, heart attack, or stroke. This money can be used for anything—medical bills, mortgage payments, or lifestyle adjustments—and is independent of your life insurance payout.
Loss of License Insurance
While not life insurance, this is often managed through the same ALPA Member Insurance portal. For many pilots, the risk of losing their medical certificate is a more immediate financial threat than death. Integrating your life insurance strategy with your disability/loss-of-license strategy is critical for comprehensive financial planning in 2026.
Common Mistakes When Seeking ALPA Quotes
- Underestimating Coverage Needs: Many pilots rely solely on the "basic" life insurance provided by their airline. This is often only 1x or 2x their annual salary, which is rarely enough for a family.
- Waiting Too Long: Rates for the 20-year level term are significantly cheaper at age 30 than at age 45. Locking in a level rate early can save tens of thousands of dollars over the life of the policy.
- Misrepresenting Health Status: Failing to disclose a medical condition can lead to a denial of claims later. If you are unsure if a condition matters, disclose it and let the underwriters decide.
- Ignoring the "Double-Up" Opportunity: ALPA often has "open enrollment" periods where members can increase their coverage by a certain amount without a medical exam. Missing these windows can make it harder to get more coverage later if your health declines.
Frequently Asked Questions
Can I keep my ALPA life insurance if I leave my airline?
Yes, in most cases. ALPA term life insurance is generally "portable," meaning you can keep the coverage even if you change airlines, provided you remain an ALPA member or meet the conversion requirements defined in the policy. If you leave the union entirely, you may have a specific window of time to convert the group coverage into an individual policy without a medical exam.
How do ALPA quotes compare to "Big Box" insurance companies?
ALPA quotes are often lower for pilots because the "risk pool" consists entirely of professional pilots. Retail insurers sometimes "rate" pilots (charge them more) because they don't distinguish between a highly trained airline captain and a low-hour private pilot. ALPA’s underwriter understands the safety record of commercial aviation.
Does ALPA term life insurance cover me while I'm flying?
Yes. Unlike some low-cost retail policies that may have "aviation exclusions," ALPA-sponsored life insurance is specifically designed to cover pilots while they are performing their professional duties. It covers you during commercial flights, deadheading, and usually during general aviation flying as well.
Is the quote I see online the final price?
Not necessarily. The online quote is a "Standard" rate estimate. If you are in exceptional health, your final premium might be lower (Preferred). If you have underlying health issues or a history of tobacco use, your final premium could be higher. The formal quote is only issued after the underwriting process is complete.
How often should I review my ALPA insurance quote?
It is wise to review your coverage every three to five years or whenever a major life event occurs (marriage, birth of a child, purchase of a home). As your salary increases with seniority, your "human capital" value increases, and your life insurance should reflect that.
Practical Recommendation
If you are an ALPA member in 2026, your first action should be to log in to the ALPA Member Insurance Research site and run a "Quick Quote" for both the Group Term and 20-Year Level Term options. Compare these against any employer-provided coverage you currently have.
For most pilots under age 45, securing a 20-Year Level Term policy for at least $500,000 to $1,000,000 is the most effective way to provide long-term family security. This protects you against the "age-band" price jumps inherent in the standard group plan and ensures that your family is protected even if you develop a medical condition later that makes you uninsurable on the open market.