As of 2026, converting 8,900 Euros is approximately equal to 9,790 US Dollars, assuming a mid-market exchange rate of 1.10. This specific value is subject to constant change due to the high volatility of the foreign exchange (Forex) market. The final amount you receive will depend heavily on the service provider's margin, transaction fees, and the specific time of the trade.
The EUR/USD currency pair represents the two largest economies in the world and remains the most liquid and heavily traded pair in the global financial system. When you are looking to convert a significant sum like 8,900 Euros, understanding the mechanics of the exchange, the hidden costs involved, and the regulatory environment of 2026 is essential for maximizing your value. This guide provides a comprehensive breakdown of the factors influencing this conversion, the best methods for execution, and the legal considerations for moving these funds across borders.
Understanding the Mid-Market Rate vs. Retail Rates
When you search for "8900 euros to dollars" on a search engine, the result you see is typically the mid-market rate. Also known as the interbank rate, this is the midpoint between the "buy" and "sell" prices of the currencies on the global market. It is the rate that banks and large financial institutions use when trading with each other in massive volumes.
However, as an individual or a small business, you rarely have access to this exact rate. Retail providers—including high-street banks, airport kiosks, and online money transfer services—apply a "spread" or a markup to the mid-market rate. For example, if the mid-market rate is 1.10, a bank might offer you a rate of 1.06. This difference of 0.04 represents their profit margin. On a sum of 8,900 Euros, a 4% spread translates to a loss of approximately 356 Euros ($391 USD) compared to the mid-market rate.
In 2026, the gap between traditional banking rates and fintech solutions continues to widen. Digital-first platforms often provide rates within 0.5% of the mid-market, while traditional institutions may still charge upwards of 3% to 5% in hidden margins.
Factors Influencing the EUR/USD Exchange Rate in 2026
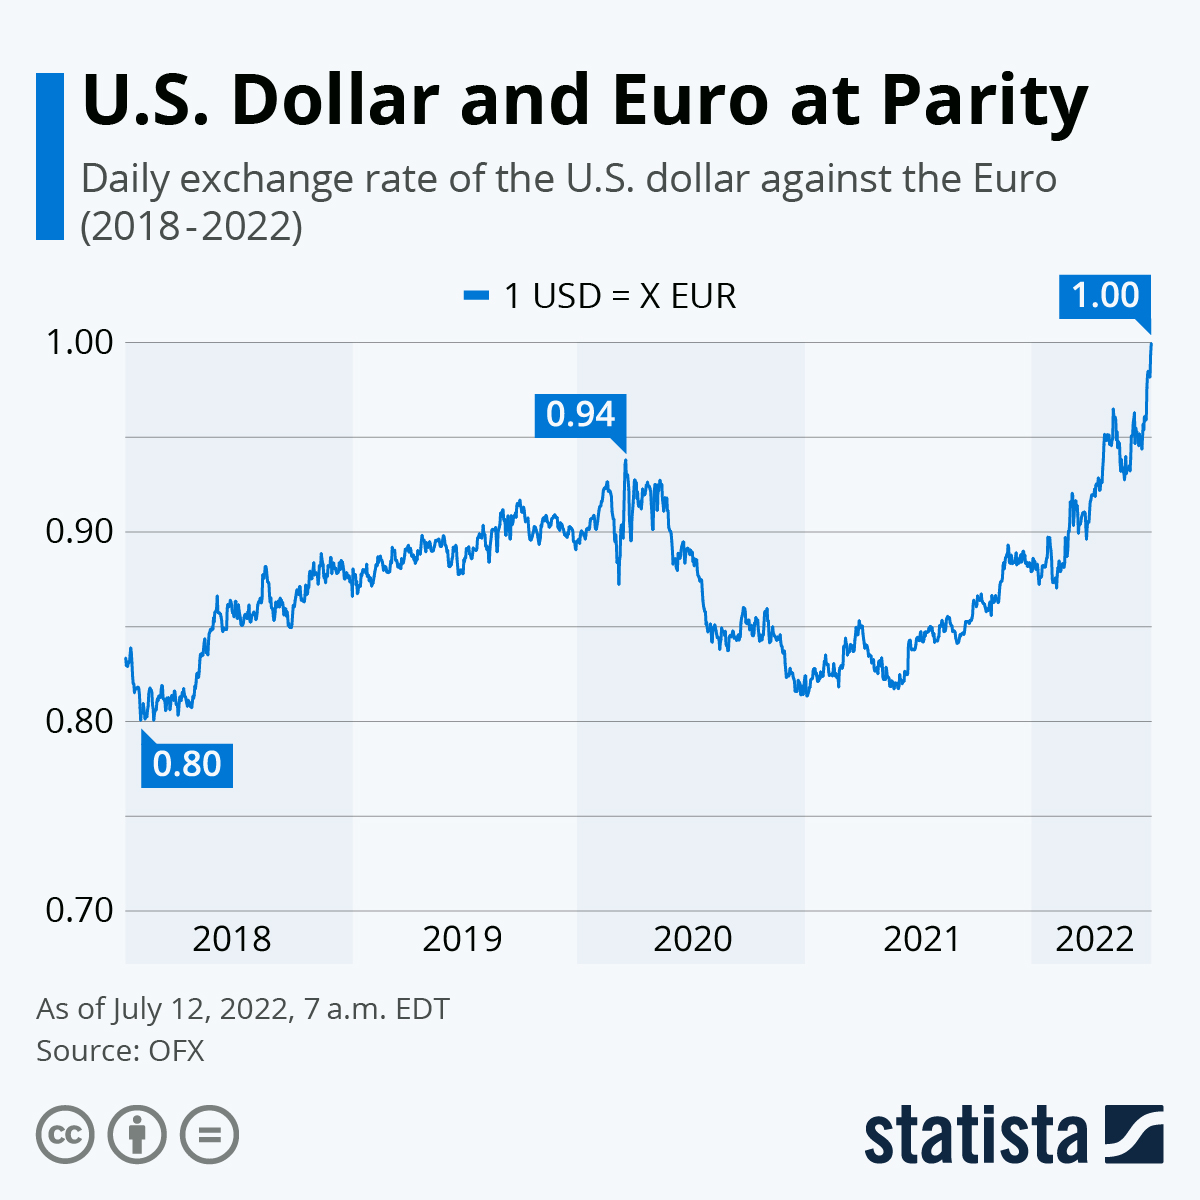
The value of 8,900 Euros in US Dollars is not static; it is influenced by a complex web of macroeconomic indicators and geopolitical events. In the current 2026 landscape, three primary drivers dictate the strength of the Euro against the Greenback.
1. Central Bank Monetary Policy
The relationship between the European Central Bank (ECB) and the Federal Reserve (Fed) is the most significant factor. If the Fed maintains higher interest rates than the ECB, the US Dollar typically strengthens as investors seek higher yields on dollar-denominated assets. Conversely, if the ECB raises rates to combat inflation within the Eurozone while the Fed remains dovish, the Euro will appreciate, making your 8,900 Euros worth more in Dollars. You can monitor the latest policy decisions on the official European Central Bank website.
2. Inflation Differentials
Inflation erodes purchasing power. In 2026, markets closely watch the Harmonized Index of Consumer Prices (HICP) in Europe versus the Consumer Price Index (CPI) in the United States. A higher inflation rate in the Eurozone relative to the U.S. generally leads to a depreciation of the Euro. Currency traders use these metrics to hedge against future volatility, which can cause sudden shifts in the 8,900 EUR to USD conversion rate within a single trading day.
3. Geopolitical Stability and Trade Balances
The Eurozone’s heavy reliance on energy imports and its export-oriented economy (led by Germany) means that global trade tensions or energy price shocks directly impact the Euro. In 2026, the continued transition to green energy and trade agreements between the EU and the US play a pivotal role. A surplus in the Eurozone's current account balance—meaning they export more than they import—usually provides a tailwind for the Euro.
Comparison of Conversion Methods for 8,900 EUR
Choosing the right platform for a mid-sized transfer like 8,900 Euros can save you hundreds of dollars. Below is a comparison of common methods available in 2026.
| Method | Estimated Rate Margin | Fixed Fees | Pros | Cons |
|---|---|---|---|---|
| Traditional Banks | 3.0% – 5.0% | $25 – $50 | Highly secure, familiar | High costs, slow (3-5 days) |
| Fintech/Neo-banks | 0.3% – 0.7% | Low to None | Real-time, transparent | Digital only, limited physical support |
| Specialist Brokers | 0.5% – 1.0% | Usually None | Personal service, hedging | Better for larger sums (>$10k) |
| Airport Kiosks | 7.0% – 15.0% | Often hidden | Immediate physical cash | Extremely poor value |
| P2P Platforms | 0.2% – 0.5% | Variable | Excellent rates | Can have lower liquidity for fast trades |
Why Fees Matter on 8,900 Euros
If you are converting 8,900 Euros for a one-time purchase, such as a used vehicle or a down payment on a rental in the U.S., a 5% loss at a bank is not just a "convenience fee." It is a substantial amount of money ($450+) that could have been used for shipping, insurance, or taxes. Always demand to see the "effective exchange rate," which is the total amount you pay divided by the total amount you receive, including all hidden costs.
Legal and Regulatory Requirements for 2026
When dealing with a conversion of 8,900 Euros, you are approaching the threshold for mandatory financial reporting in many jurisdictions.
The $10,000 Rule (FinCEN)
In the United States, the Financial Crimes Enforcement Network (FinCEN) requires that any physical transportation of currency or monetary instruments exceeding $10,000 must be reported using FinCEN Form 105. Depending on the current 2026 exchange rate, 8,900 Euros may fluctuate just above or below this $10,000 mark.
- If 1 EUR = 1.13 USD: 8,900 EUR = $10,057. You must declare this if carrying physical cash.
- If 1 EUR = 1.05 USD: 8,900 EUR = $9,345. No declaration is required for physical transport, though digital transfers are still monitored.
It is important to note that digital transfers via SWIFT or SEPA are automatically reported by the banking institutions involved to comply with Anti-Money Laundering (AML) and Know Your Customer (KYC) regulations. For more information on reporting requirements, visit the official FinCEN website.
Tax Implications
Exchanging 8,900 Euros for Dollars is generally not a taxable event itself for personal use. However, if the Euros were held as an investment and you are realizing a "capital gain" because the Euro strengthened significantly since you acquired it, you may owe taxes on that gain in certain jurisdictions. In 2026, tax authorities have become increasingly proficient at tracking digital currency movements to ensure compliance.
Practical Steps to Convert 8,900 Euros
To ensure you get the best deal and stay compliant with 2026 regulations, follow these steps:
- Monitor the Rate: Use a reputable financial news source or a real-time converter to track the EUR/USD pair for a few days. Look for a "local peak" in the Euro's value.
- Verify the Provider: Ensure the platform you use is regulated by relevant authorities, such as the FCA in the UK, BaFin in Germany, or the Consumer Financial Protection Bureau (CFPB) in the US.
- Check for "Limit Orders": Some 2026 fintech platforms allow you to set a target rate. If you want to convert 8,900 Euros only when it hits 1.12 USD, the system will execute the trade automatically for you.
- Consider the Timing: Avoid converting on weekends. The Forex market closes on Friday evening and opens on Sunday evening (EST). During the weekend, providers often increase their spreads to protect themselves against "gap risk" when the market reopens, resulting in a worse rate for you.
- Secure Your Documentation: Keep receipts and transfer confirmations. If you are moving these funds into a US bank account to buy property or pay for education, the receiving bank will likely ask for "Proof of Funds" to satisfy AML requirements.
Common Mistakes to Avoid
- Using Your Home Bank by Default: Most people assume their primary bank will give them a "loyalty rate." This is rarely the case. Banks typically offer their worst rates to captive retail customers.
- Ignoring the "Fixed Fee": On a smaller sum, a $5 fee is fine. On 8,900 Euros, a percentage-based fee is usually more impactful. However, some providers offer a "great rate" but then add a $100 "international wire fee." Always look at the final "net" amount.
- Dynamic Currency Conversion (DCC): If you are using a European debit card in the US to pay a $9,790 bill, the terminal might ask if you want to pay in Euros. Always choose the local currency (USD). If you choose Euros at the point of sale, the merchant's bank chooses the exchange rate, which is almost always significantly worse than your own bank's rate.
Frequently Asked Questions
What is the mid-market rate for 8900 Euros to Dollars right now?
The mid-market rate is the real-time fluctuating price at which banks trade. In 2026, you can find this on sites like Bloomberg, Reuters, or Google Finance. Note that this is not the rate you will receive at a bank, as they add a profit margin (spread) on top of this.
Is it better to exchange 8,900 Euros in Europe or the United States?
Generally, it is better to use a digital international transfer service that operates in both regions. If you must use physical cash, exchanging Euros for Dollars is often slightly more competitive in Europe due to the higher volume of Euro-holding banks, but the difference is marginal compared to the savings offered by online platforms.
How long does it take to transfer 8,900 EUR to a USD bank account?
In 2026, many transfers are near-instant if using the SEPA Instant Credit Transfer scheme (for the European side) or modern fintech rails. However, traditional SWIFT transfers can still take 3 to 5 business days as the money moves through intermediary "correspondent" banks.
Will I be taxed on the conversion of 8,900 Euros?
Conversion for personal travel or spending is not typically taxed. However, if you are a business or an investor, the "forex gain" (the profit made from currency fluctuation) may be subject to capital gains tax. You should consult a tax professional regarding your specific residency and financial situation.
Can I use 8,900 Euros to buy Bitcoin or other digital assets in 2026?
Yes, most major cryptocurrency exchanges allow you to deposit Euros via SEPA and then trade for USD-pegged stablecoins or other assets. However, be aware of the volatility and additional trading fees, which may exceed the cost of a standard currency exchange.
Final Recommendation
For a sum of 8,900 Euros, the most efficient path in 2026 is to utilize a regulated digital money transfer service rather than a traditional bank. By doing so, you can expect to save between $200 and $400 in conversion costs. Ensure that you have your identification ready for KYC verification, and if you are carrying the funds physically, check the current exchange rate to determine if you have crossed the $10,000 threshold requiring a FinCEN declaration. Always prioritize transparency in the exchange rate over "zero fee" marketing, as the rate margin is where the true cost usually hides.