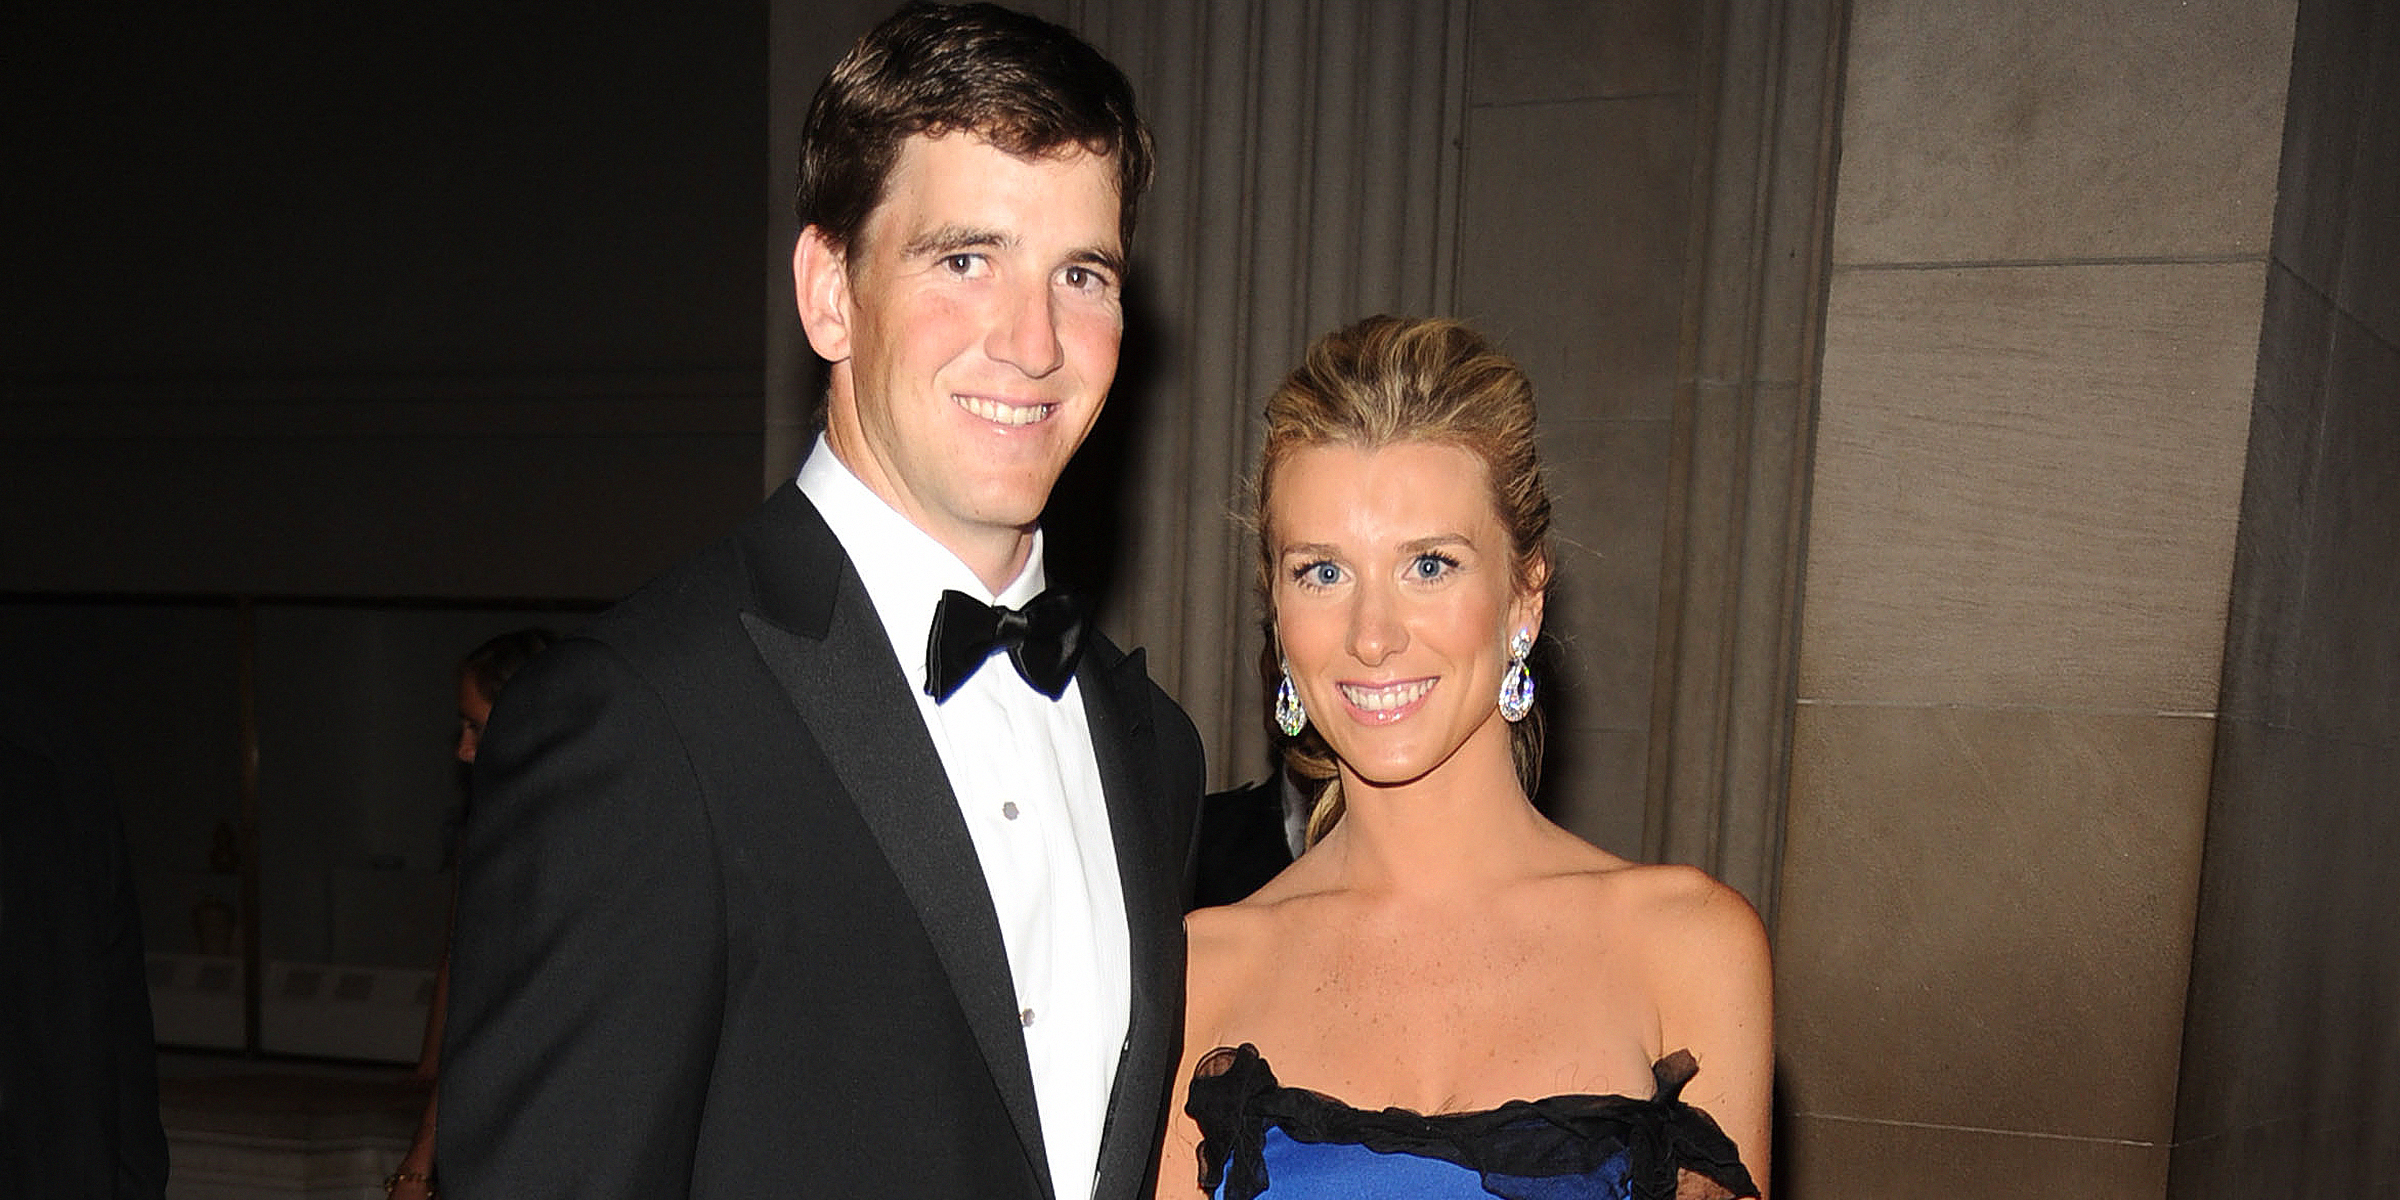
Public government records in the United States do not publish personal net worth figures for private citizens. However, public land deeds, municipal tax filings, and non-profit disclosures show that Abby McGrew and her husband, retired NFL quarterback Eli Manning, hold tens of millions of dollars in real estate, backed by Manning's $252 million career playing salary.
Public Records vs. Estimated Net Worth: Understanding the Distinction
When researchers search for the net worth of Abby McGrew (Abby McGrew Manning) in the public record, they encounter a fundamental distinction between legal public documentation and commercial financial estimation. In the United States, municipal, state, and federal public records do not aggregate or publish an individual’s total liquid wealth, investment portfolio, or net balance sheet. Unless a private individual is an executive or major shareholder of a publicly traded corporation required to file financial reports with the U.S. Securities and Exchange Commission (SEC), personal financial holdings remain private.
Consequently, figures frequently cited online—such as a combined net worth of $150 million to $160 million for Abby McGrew and Eli Manning—are analytical estimates rather than official public records. These estimates are compiled by financial journalists, sports economists, and media outlets using verified public datapoints. The primary verified components supporting these calculations include:
- Documented Athletic Earnings: Contract figures, signing bonuses, and career salary data verified through the National Football League Players Association (NFLPA) and public team press releases.
- County Real Property Registries: Land deeds, mortgage filings, and tax assessments recorded at the county level in New Jersey, New York, and Mississippi.
- Corporate and Business Registrations: Filings maintained by state Secretaries of State regarding registered limited liability companies (LLCs) or commercial partnerships.
- IRS Non-Profit Disclosures: Tax-exempt organizational filings (Form 990) that detail charitable contributions, board participation, and institutional foundation holdings.
Understanding what is—and what is not—part of the public record prevents common misunderstandings when evaluating the financial standing of high-net-worth individuals who do not serve as public corporate officers.
Verifiable Real Estate Transactions in Public Land Records
While bank account statements and stock holdings are confidential, real property ownership is explicitly a matter of public record in every U.S. county. Municipal tax assessors, registers of deeds, and county clerks maintain searchable archives of real estate transfers, purchase prices, and property tax liabilities. Public land records in multiple jurisdictions document significant real estate acquisitions by Abby McGrew and Eli Manning.
Summit, New Jersey Primary Residence
During Eli Manning’s 16-season tenure with the New York Giants, the couple established their primary residence in Summit, New Jersey, located in Union County. County property records reveal that the couple acquired a historic multi-acre property in 2014 for an initial purchase price reported in land records near $4.7 million.
Subsequent municipal planning board records and building permit applications detail extensive renovations undertaken on the property. Publicly available tax assessment data indicates that the property underwent substantial capital improvements, including a complete structural overhaul, expansion of living spaces, and addition of security infrastructure. As of municipal tax revaluations, property tax assessments reflect an asset valuation substantially higher than the original purchase price, making it one of the premier residential parcels in Union County.
Quogue, New York (The Hamptons) Oceanfront Estate
In 2017, public real estate transfers in Suffolk County, New York, recorded the purchase of a major oceanfront estate in the town of Quogue, located on the East End of Long Island. According to Suffolk County clerk entries and local property transfer lists:
- Purchase Price: The oceanfront property was acquired for approximately $8.5 million.
- Property Footprint: Public tax maps delineate a multi-story home spanning over 7,000 square feet, situated on a 1.2-acre oceanfront parcel with direct beach access and custom amenities.
- Zoning and Environmental Permits: Coastal management filings with local municipal boards detail approved structural enhancements designed to meet modern shoreline conservation and hurricane resilience guidelines.
Real estate registries show that high-value properties in the Hamptons market have appreciated significantly over the past decade. Public tax records confirm that annual municipal and school district property taxes for this holding alone run into six-figure sums, reflecting its multi-million-dollar valuation.
Oxford, Mississippi Real Estate Holdings
Abby McGrew and Eli Manning both attended the University of Mississippi (Ole Miss), where they met as undergraduate students. Public land registries in Lafayette County, Mississippi, document additional real estate transactions tied to the family. These holdings include residential property acquired in Oxford, Mississippi, serving as a secondary residence for university events and family visits. Public tax records show consistent maintenance of municipal property tax obligations across these assets.
Title Ownership Structures and Privacy Protections
A detailed search of public property records reveals that high-net-worth public figures frequently record deeds using specific legal structures:
- Joint Tenancy / Tenancy by the Entirety: Standard spousal titling recorded directly under personal names on county grant deeds.
- Revocable Family Trusts: Transfers of real property titles into living trusts designed to manage estate planning, probate avoidance, and operational privacy.
- Limited Liability Companies (LLCs): Real estate acquisitions made via legal entities registered with state business bureaus. While the underlying beneficial owners of an LLC were historically shielded in land records, property tax bills and municipal service registrations frequently maintain public links to the managing parties or primary residential addresses.
Income Sources and Financial History Supporting Public Records
To put public asset records into context, researchers evaluate the primary income streams that created the couple's asset base. Because Abby McGrew and Eli Manning maintain joint marital assets, her financial profile is directly connected to the verified historical earnings of the household.
- Verified Family Income Sources
- NFL Contracts ($252.8M Total)
- Commercial Deals & Media (Omaha)
- Publicly Recorded Capital Deployment
- Premium Real Estate (NJ, NY, MS Deeds)
- Philanthropy (IRS 990 Filings)
NFL Career Compensation
Eli Manning’s player contracts are documented through historic NFL salary registries and team reports. Over his 16-year career with the New York Giants (2004–2019), Manning signed multiple milestone contract extensions:
- 2004 Rookie Contract: Six-year deal valued at up to $54 million with performance incentives.
- 2009 Extension: Six-year extension valued at $97.5 million, making him one of the highest-paid players in the league at the time.
- 2015 Extension: Four-year extension valued at $84 million with $65 million in total guarantees.
Public career totals confirm gross playing earnings of $252.8 million. This figure places Manning among the top grossing players in NFL history, providing a verified base of liquid capital before accounting for investment returns, taxes, and agent commissions.
Corporate Endorsements and Media Enterprises
Beyond playing salary, public business records and corporate press releases confirm long-standing endorsement partnerships. Major corporate entities—including Toyota, Hublot, Dunkin', Kraft Heinz, and DirecTV—maintained multi-year sponsorship agreements with Manning.
Following Eli Manning's retirement from active football, the couple expanded their commercial footprint through media partnerships, including participation in Omaha Productions (co-hosting the ManningCast alongside Peyton Manning). These corporate engagements generate ongoing operational revenue for the family business entity.
Abby McGrew's Professional Background
Abby McGrew earned a degree in Fashion Merchandising from Southern Methodist University (SMU) in Dallas, Texas. Prior to her marriage to Eli Manning in April 2008, she worked in New York City as an account executive and fashion designer for the designer apparel brand Pamella Roland.
Following her marriage, McGrew transitioned her primary focus toward overseeing family philanthropic operations, real estate management, and charitable foundation oversight, as documented in non-profit regulatory filings.
Philanthropic Disclosures and Tax Exemption Records (Form 990)
Public records regarding high-net-worth wealth extend into the non-profit sector. Under federal tax laws enforced by the Internal Revenue Service (IRS), tax-exempt 501(c)(3) charitable organizations must file annual financial reports on IRS Form 990. These documents are open to public inspection and detail charitable contributions, foundation capital, and officer governance.
University of Mississippi Medical Center Campaigns
Public university statements and non-profit disclosure filings highlight major philanthropic commitments by Eli and Abby Manning. The couple spearheaded a multi-million-dollar capital campaign for the Blair E. Batson Hospital for Children at the University of Mississippi Medical Center (UMMC) in Jackson, Mississippi.
- Initial Campaign: The couple committed $2.5 million to establish the Eli and Abby Manning Children's Clinics, expand pediatric emergency care facilities, and fund specialized surgical suites.
- Expansion Initiatives: Subsequent public announcements and fundraising drive reports show continued multi-million-dollar fundraising pledges supporting the Children's of Mississippi capital expansion project.
St. Jude Children's Research Hospital and Local Community Initiatives
In addition to pediatric medical programs in Mississippi, public charity records show Abby McGrew's sustained involvement with St. Jude Children's Research Hospital. McGrew has chaired and co-hosted major fundraising galas in New York and New Jersey, raising millions of dollars for pediatric cancer research and treatment.
Because public non-profit filings mandate reporting of major financial transactions and foundation assets, these records provide objective documentation of the scale of the family's charitable giving.
Breakdown of Available Public Record Types for Financial Verification
The following table summarizes the primary public record categories, the precise information they contain regarding personal net worth, and their legal availability under U.S. law:
| Record Category | Specific Document Type | Financial Data Disclosed | Legal Limitations & Privacy Restrictions |
|---|---|---|---|
| Real Property Records | County Grant Deeds, Mortgages, Tax Assessments | Purchase prices, parcel dimensions, property tax dues, tax-assessed values | Does not reveal mortgage balances or unrecorded private equity agreements. |
| Corporate Registrations | State Secretary of State LLC & Inc. Filings | Registered agents, entity status, principal office business addresses | Does not mandate disclosure of net income, bank balances, or private member distributions. |
| Non-Profit Disclosures | IRS Form 990, Charitable Trust Filings | Foundation donations, institutional assets, board officer compensation | Limited strictly to non-profit entities; does not display personal tax returns or private income. |
| Public Corporate Filings | SEC Form 3, 4, 5 & 10-K Reports | Stock ownership, executive compensation in public companies | Applies only to corporate officers and directors of publicly traded corporations. |
| Court & Probate Records | Civil Litigation, Marriage Dissolution, Probate Filings | Civil judgments, estate inventories, structured settlements | Many filings can be sealed or redacted by court order to protect personal safety and financial privacy. |
Privacy Protections, LLC Rules, and Public Financial Transparency
A common point of confusion for researchers is why personal liquid assets—such as private bank balances, mutual fund holdings, investment accounts, and personal property like artwork or vehicles—are not accessible through public records.
The Federal and State Legal Framework
Under U.S. privacy laws, financial institutions are strictly prohibited from releasing personal customer data to the public without a court order, subpoena, or explicit owner consent. Government agencies collect personal income tax data via the IRS and state departments of taxation, but these tax returns are strictly confidential under Title 26 of the United States Code (Section 6103).
Corporate Transparency Act Implications
The legal landscape surrounding business entity disclosures underwent shifts with the implementation of the Corporate Transparency Act (CTA), administered by the Financial Crimes Enforcement Network (FinCEN). While the CTA requires many LLCs and private entities to report Beneficial Ownership Information (BOI) to federal regulators:
- Non-Public Database: The federal BOI database is non-public and strictly restricted to law enforcement, intelligence agencies, and financial institutions performing customer due diligence.
- State LLC Privacy: States like Delaware, Wyoming, and Nevada continue to offer varying degrees of anonymity on public Secretary of State search portals regarding entity ownership.
As a result, high-net-worth individuals like Abby McGrew utilize legitimate legal structures to maintain personal privacy while fully complying with state and federal reporting mandates.
Legal and Financial Research Guidelines for High-Net-Worth Individuals
Researchers, journalists, and legal professionals evaluating public asset records for private individuals should follow established verification standards to distinguish confirmed public record facts from unverified digital reporting.
Step 1: Verify Land Registry Records Directly at the County Level
Do not rely on commercial real estate listing aggregators for ownership verification. Request official copies of recorded deeds and tax assessment cards directly from the relevant County Clerk or Tax Assessor portal (e.g., Suffolk County Clerk in NY or Union County Clerk in NJ). Check for:
- Grantor/Grantee indexes showing legal title transfers.
- Recorded deeds of trust or mortgages establishing encumbrances against real property.
- Parcel identifier numbers matching municipal tax maps.
Step 2: Cross-Reference Non-Profit Filings via Official Repositories
To verify charitable giving and non-profit involvement, access official IRS Form 990 filings through the IRS Tax Exempt Organization Search tool or established non-profit databases like Candid (formerly GuideStar). Confirm:
- The exact tax-exempt legal name of the foundation.
- Total revenue, end-of-year net assets, and specific grants paid.
- Listed officers, directors, and key employees receiving reported compensation.
Step 3: Differentiate Between Gross Income and Net Worth
Gross earnings, such as Eli Manning's $252.8 million NFL playing salary, do not equal current net worth. A proper financial accounting must factor in structural deductions:
- Federal, State, and Local Taxes: High earners in states like New York and New Jersey historically face top-bracket combined marginal tax rates exceeding 45% to 50%.
- Professional Fees: Standard agent commissions (typically 1.5% to 3% in the NFL), legal representation, wealth management fees, and public relations retainers.
- Lifestyle and Property Maintenance Expenses: Property taxes, structural insurance, security details, and asset maintenance across multiple estates.
- Investment Returns and Asset Growth: Equity appreciation, real estate market growth, and private venture returns that reinvest tax-paid capital over decades.
Frequently Asked Questions
Is Abby McGrew's exact personal net worth available in public government records?
No. Government records in the United States do not record or publish overall personal net worth figures for private citizens. Public records only display specific asset categories, such as real estate deeds, property tax assessments, and tax-exempt charitable foundation filings.
How much did Eli Manning and Abby McGrew pay for their Hamptons home according to public records?
Public property records in Suffolk County, New York, record the purchase price of the oceanfront estate in Quogue (The Hamptons) at approximately $8.5 million in 2017. Current market values for similar oceanfront properties in that municipality are substantially higher based on municipal tax reassessments.
Are bank account balances and stock portfolios part of the public record for private citizens?
No. Private banking records, personal liquid account balances, individual retirement accounts, and personal brokerage holdings are confidential under federal privacy laws. They only become public if entered into court records during legal proceedings or probate administration.
How do non-profit disclosures (IRS Form 990) reflect the Manning family's financial activities?
IRS Form 990 disclosures provide public documentation of the family's charitable giving. These filings detail donations made to medical institutions like the Blair E. Batson Hospital for Children at UMMC, foundation asset reserves, and non-profit governance structures managed by the family.
What role does Abby McGrew play in managing joint family assets and charitable foundations?
Public philanthropic filings and corporate records show that Abby McGrew co-manages the family's major charitable initiatives, co-chairs fundraising galas, and oversees structural investments in primary residences in New Jersey and New York.
Professional Research Summary and Recommended Action
When analyzing high-net-worth profiles like Abby McGrew's, researchers should separate public land registry entries and tax filings from unverified commercial estimates. To build an accurate, legally sound asset profile:
- Consult Official Archives: Source primary real property data directly from county record offices rather than third-party real estate blogs.
- Evaluate Total Household Capital: Recognized financial figures for Abby McGrew reflect joint spousal assets built primarily on Eli Manning’s $252.8 million gross NFL salary, endorsement portfolio, and long-term real estate investments.
- Acknowledge Statutory Privacy Boundaries: Recognize that liquid net worth, investment portfolios, and cash reserves remain private under state and federal law.
Disclaimer: This article is intended for educational and research purposes only and does not constitute formal legal, financial, or tax advice. Personal asset structures, real property tax rates, and regulatory filing requirements vary by jurisdiction and are subject to legislative changes.
EDITORIAL CATEGORY METADATA: