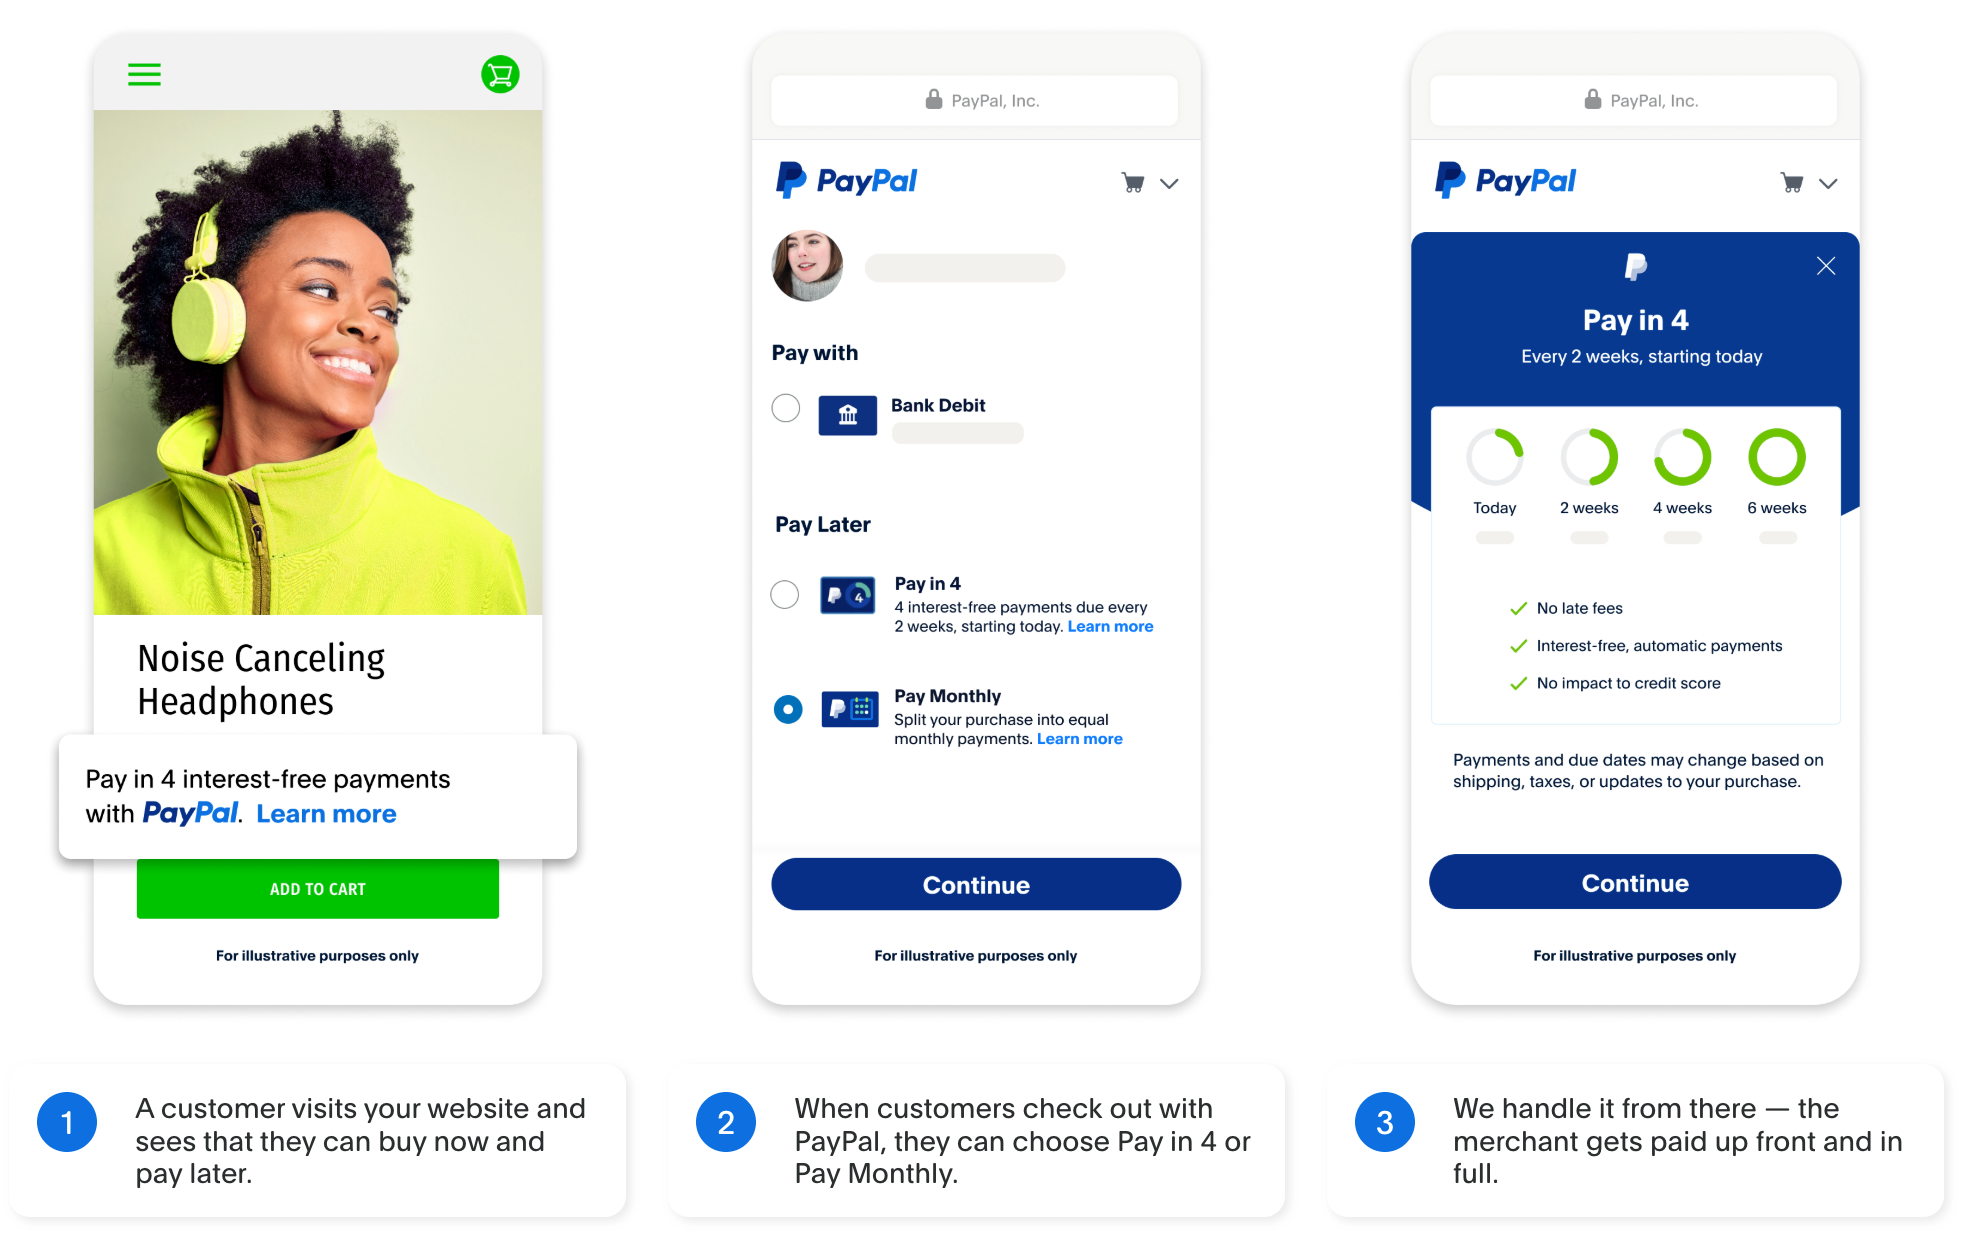
PayPal Pay in 4 splits eligible purchases into four equal installments, with the first payment due at checkout and the remaining three billed every two weeks. To qualify, users must have a valid U.S. PayPal account in good standing, be at least 18 years old, and pass a soft credit check that does not impact their credit score.
Navigating modern digital finance often requires a clear understanding of how alternative lending products function at checkout. Buy Now, Pay Later (BNPL) services have transformed e-commerce by offering structured installment plans without traditional revolving credit card interest rates. Among these services, PayPal Pay in 4 stands out as a widely integrated feature across thousands of online merchants. However, securing approval for an installment plan is not automatic. Users must satisfy a specific set of eligibility criteria, financial prerequisites, and account requirements before the option becomes available in their digital wallet.
Understanding PayPal Pay in 4 and Its Purpose
PayPal Pay in 4 is a short-term installment loan product that allows consumers to divide the cost of eligible purchases into four equal payments. The first payment is processed at the time of purchase, while the subsequent three payments are automatically charged to a linked debit card, credit card, or bank account every 14 days.
The primary purpose of this financial tool is to provide liquidity and budgeting flexibility for online shoppers without charging traditional interest. Unlike revolving credit lines that accrue compound interest if balances remain unpaid, Pay in 4 is a fixed-term loan with zero interest and no hidden signup fees. If a payment fails, however, late fees may apply depending on the user's state of residence.
For merchants, integrating this payment method helps reduce shopping cart abandonment by lowering the immediate financial barrier to purchase. For consumers, it serves as a predictable mechanism to manage cash flow for medium-sized purchases, typically ranging from $30 to $1,500. Understanding the precise rules governing this service ensures that applicants can successfully utilize the feature without encountering unexpected denials or account restrictions.
Core Eligibility Requirements for Applicants
Before a user can select Pay in 4 at checkout, PayPal evaluates several foundational criteria. These requirements are designed to verify the applicant's identity, age, residency, and baseline financial capability.
Age and Legal Residency
Applicants must be of legal age of majority in their respective jurisdiction. For U.S. residents, this generally means being at least 18 years of age. Additionally, users must possess a valid, active U.S. PayPal account registered with verified personal information, including a confirmed residential address and telephone number.
Account Status and History
A history of positive account management is critical. Accounts that are newly created, unverified, or flagged for suspicious activity frequently experience checkout restrictions. PayPal reviews the user's past transaction history within the ecosystem. Users who maintain linked, verified funding sources—such as a confirmed bank account, debit card, or credit card—demonstrate higher financial reliability, which directly supports eligibility.
Purchase Amount Boundaries
Pay in 4 is not available for every transaction size. The service applies to eligible purchases generally ranging between $30 and $1,500 USD. Transactions falling below the minimum threshold or exceeding the maximum cap will not display Pay in 4 as an available payment method during the checkout sequence.
The Credit Evaluation Process: Soft Checks Explained
A common concern among consumers exploring installment plans is how the application process affects their credit scores. PayPal evaluates creditworthiness for Pay in 4 through a specialized assessment process.
Soft Credit Inquiries vs. Hard Credit Inquiries
When a user requests a Pay in 4 plan, PayPal conducts a soft credit check with one or more major credit bureaus. A soft inquiry verifies the applicant's identity and reviews their credit history, but it is entirely invisible to other lenders and has zero impact on the applicant's credit score. This is fundamentally different from a hard credit inquiry, which typically occurs when applying for traditional auto loans, mortgages, or standard credit cards.
Factors Evaluated During the Assessment
While the soft check protects credit scores, PayPal still analyzes specific internal and external financial signals. These include:
- Credit History: Past performance on revolving credit, installment loans, and other financial obligations.
- PayPal Account Activity: Frequency of use, history of chargebacks, and successful past repayments within the PayPal ecosystem.
- Debt-to-Income Indicators: While detailed financial statements are not uploaded manually, algorithmic risk models assess affordability based on connected funding sources.
Step-by-Step Application and Checkout Workflow
Accessing Pay in 4 does not require a separate, lengthy loan application outside of the shopping experience. The evaluation occurs dynamically during the online checkout flow.
Start Checkout
- Select PayPal
- Choose Pay in 4 Option
- Real-Time Soft Credit Check
- Denied / Alternative Payment Requested
- Approved
- Pay 25% Down Payment
- Order Confirmed / Remaining 3 Payments Scheduled
- Pay 25% Down Payment
- Real-Time Soft Credit Check
- Choose Pay in 4 Option
- Select PayPal
Select PayPal at Checkout: Add eligible items to the merchant cart and proceed to checkout, selecting PayPal as the payment provider.
Choose Pay in 4: Log into the PayPal account within the checkout window and look for the Pay in 4 option listed among available payment methods.
Review Terms and Agreement: Read the loan terms, repayment schedule, and disclosures carefully. The agreement outlines the exact dates for all four installments.
Complete the Down Payment: Authorize the transaction. The system processes the initial 25% down payment immediately using the user's preferred primary funding source.
Receive Confirmation: The merchant processes the order as a fully paid transaction, while PayPal structures the remaining three payments on an automated bi-weekly schedule.
Comparison of PayPal Pay in 4 vs. Traditional Financing
To contextualize the utility of Pay in 4, it is helpful to compare its structural requirements and costs against other common consumer credit products.
| Feature | PayPal Pay in 4 | Traditional Credit Card | Personal Installment Loan |
|---|---|---|---|
| Interest Rate (APR) | 0% | Variable (often 15%–29%+) | Fixed (varies by lender and credit) |
| Credit Impact of Application | Soft check (No score impact) | Hard check (Temporary score dip) | Hard check (Temporary score dip) |
| Repayment Term | 6 weeks (4 installments) | Revolving (Minimum monthly payments) | 12 to 60 months |
| Approval Speed | Instant at checkout | Minutes to days | Days to weeks |
| Late Fees | Possible (state-dependent) | Standard late fees and penalty APR | Origination fees and late fees |
| Purchase Limits | $30 to $1,500 | Tied to total credit limit | Higher minimums (often $1,000+) |
Common Reasons for Denial and Troubleshooting
Even if a user meets the basic age and residency requirements, a Pay in 4 application can occasionally be declined. Understanding these failure points helps users resolve issues proactively.
Insufficient Funding Sources
PayPal requires a reliable backup funding source linked to the account. If the connected debit card, credit card, or bank account has expired, lacks sufficient funds for the initial 25% down payment, or fails verification, the installment option will be denied.
Internal Risk Assessment and Account Standing
Algorithms analyze transaction risk in real time. Factors such as recent account disputes, chargebacks, inconsistent IP locations, or a lack of established history within the PayPal platform can trigger an automated decline. Ensuring all account information is accurate and verified minimizes this risk.
Exceeding Maximum Limit or Merchant Exclusions
Attempting to use the service on a purchase total exceeding $1,500 or purchasing restricted items (such as digital currency, firearms, or adult services) will prevent the option from appearing. Additionally, certain merchants do not support BNPL integrations within their specific checkout portals.
Best Practices for Managing Installments Responsibly
Utilizing short-term financing products requires careful personal financial management to avoid unintended fees or account suspensions.
- Track Bi-Weekly Schedules: Note the exact dates when the remaining three payments will be automatically deducted. Ensure sufficient funds are available in the linked bank account or card on those dates to prevent overdraft fees from your financial institution.
- Understand Repayment Penalties: While Pay in 4 carries no interest, late or missed payments may incur late fees depending on regional regulations. Consistent missed payments can also result in the suspension of the PayPal account's installment features.
- Monitor Return Policies: If an item purchased via Pay in 4 is returned, the merchant's refund policy dictates how funds are returned. PayPal will apply the refund to the loan balance, canceling remaining payments or issuing a credit to the original payment method as appropriate.
Frequently Asked Questions
Does checking eligibility for PayPal Pay in 4 hurt my credit score?
No. Checking eligibility involves a soft credit inquiry, which reviews your credit profile without registering a hard inquiry. This process has zero impact on your credit score and is not visible to other financial institutions.
Can I pay off my Pay in 4 installments early?
Yes. You can log into your PayPal account at any time, navigate to your Pay in 4 plans, and make early manual payments without incurring any prepayment penalties or extra fees.
What happens if a scheduled payment fails?
If an automated payment fails due to insufficient funds, PayPal will typically attempt to re-initiate the charge a few days later. Continued payment failures may result in late fees and can restrict your ability to use Pay in 4 or other PayPal credit services in the future.
Are all merchants compatible with PayPal Pay in 4?
No. While thousands of online retailers support the feature, participation depends on the merchant's payment gateway integration. If a merchant does not support the option, Pay in 4 will not appear during the checkout screen even if your account is fully eligible.
What is the maximum purchase amount allowed?
The purchase amount must generally fall between $30 and $1,500 USD. Orders outside this specific range are automatically excluded from the installment program.
To ensure a seamless checkout experience with PayPal Pay in 4, verify that your account details are fully updated, link a reliable debit card or bank account, and confirm that your purchase falls within the $30 to $1,500 threshold before finalizing your transaction.