For business owners and self-employed individuals, credit card processing fees are almost always 100% tax-deductible. The Internal Revenue Service (IRS) classifies these costs as an "ordinary and necessary" business expense. Whether you pay flat-rate fees, interchange-plus percentages, or monthly gateway subscriptions, these costs can be subtracted from your gross income to reduce your total taxable liability.
Navigating the intersection of merchant services and tax law is a critical component of financial management for any modern enterprise. As of 2026, the transition toward a cashless economy has made credit card processing fees one of the most consistent overhead costs for small and medium-sized businesses. Understanding how to correctly categorize, track, and report these fees is not just a matter of compliance—it is a primary strategy for protecting your profit margins.
The Legal Basis for Deducting Merchant Fees
The primary authority for deducting credit card processing fees lies within the Internal Revenue Code (IRC) Section 162. This section allows for the deduction of all "ordinary and necessary" expenses paid or incurred during the taxable year in carrying on any trade or business.
An ordinary expense is one that is common and accepted in your trade or business. Since the vast majority of retail, service, and B2B industries must accept digital payments to remain competitive, these fees clearly meet the "ordinary" criteria. A necessary expense is one that is helpful and appropriate for your trade or business. An expense does not have to be indispensable to be considered necessary; it simply needs to support the generation of income.
In the 2026 tax environment, credit card processing is no longer an optional luxury but a fundamental utility, similar to electricity or internet service. Therefore, the fees charged by processors like Stripe, Square, PayPal, or traditional merchant banks are treated as costs of doing business. These are subtracted from your total revenue, effectively ensuring you are only taxed on the money you actually kept, rather than the gross amount the customer paid before the processor took their cut.
Identifying Every Deductible Processing Cost
To maximize your deduction, you must identify all the different ways merchant service providers levy charges. Many business owners overlook secondary fees, focusing only on the primary percentage-based transaction fee. However, nearly every cost associated with accepting credit cards is deductible.
Transaction-Based Fees
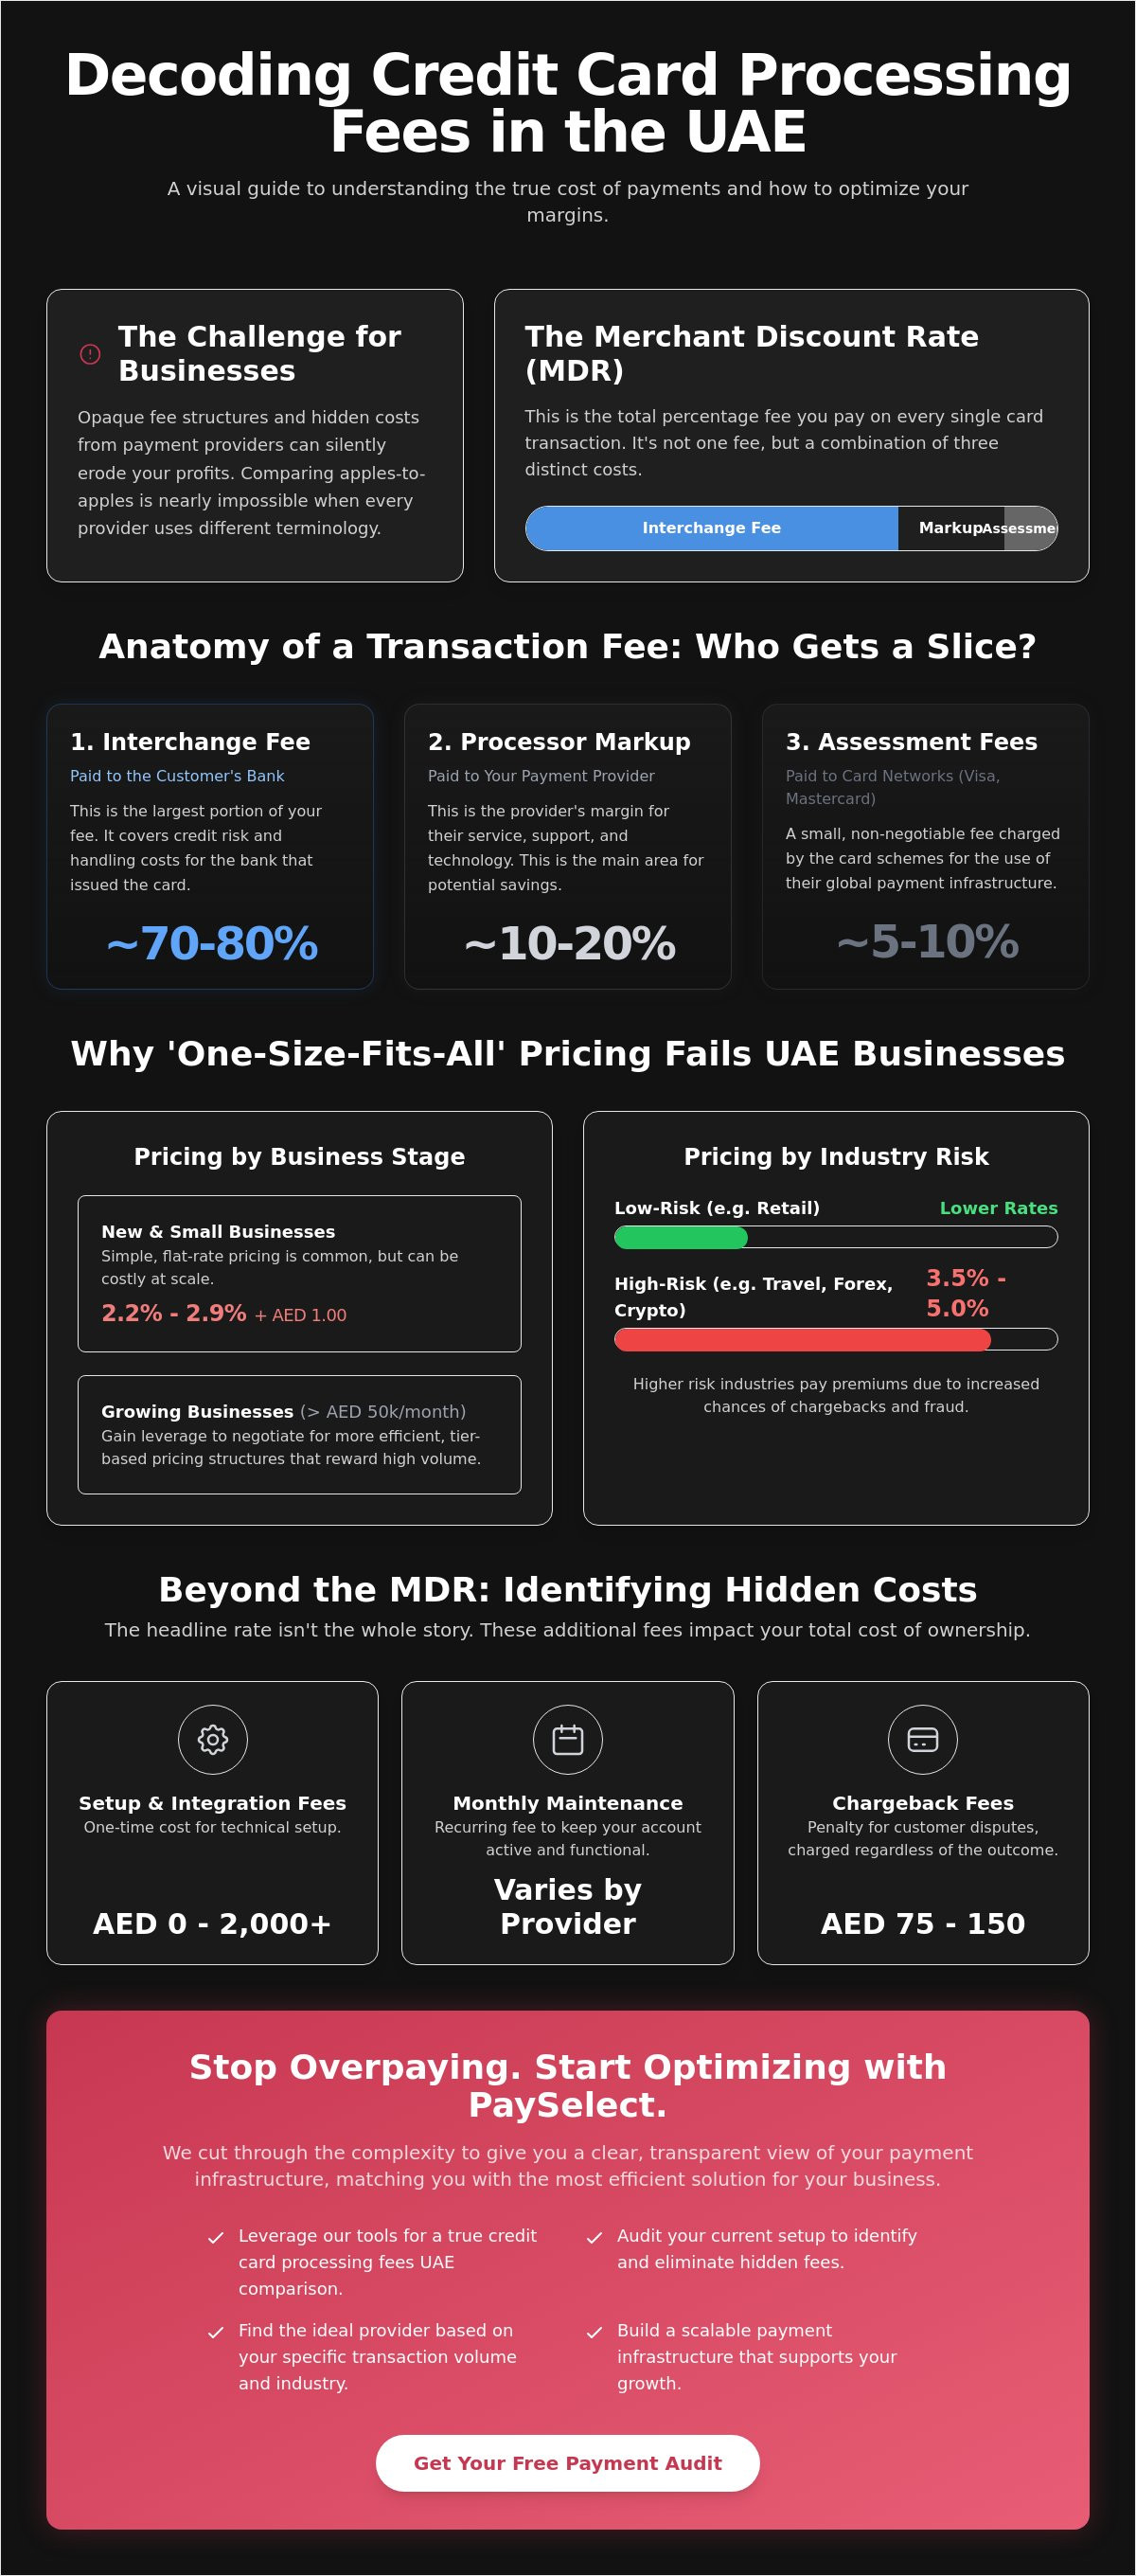
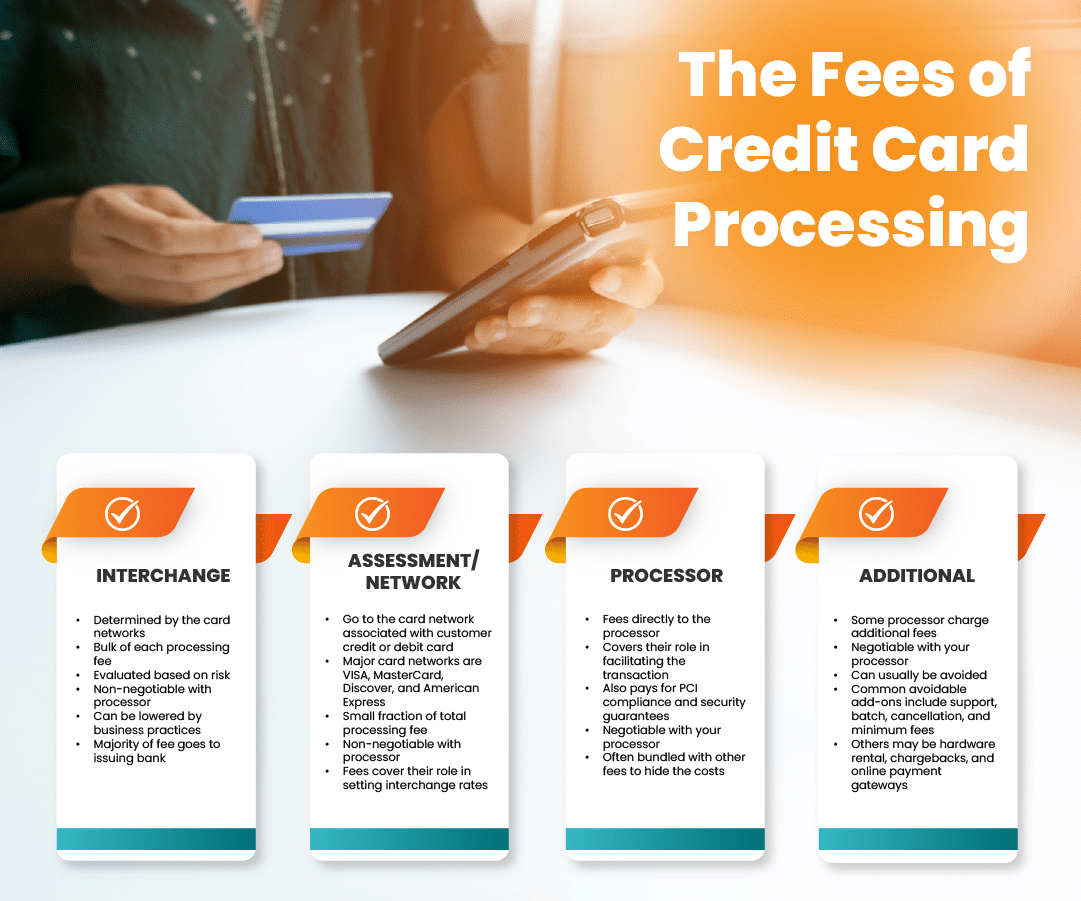
These are the most visible costs. They include the interchange fee (set by card networks like Visa and Mastercard), the assessment fee (charged by the card brands), and the processor’s markup. Whether these are billed as a flat 2.9% + $0.30 or through a complex interchange-plus model, the entire amount is deductible.
Recurring Monthly and Annual Fees
Many merchant accounts carry fixed costs regardless of transaction volume. These may include:
- Monthly Service Fees: Fixed charges for maintaining the account.
- Gateway Fees: Costs for using the software that transmits transaction data.
- PCI Compliance Fees: Charges related to ensuring your business meets Payment Card Industry Data Security Standards.
- Statement Fees: Charges for the delivery of monthly paper or digital accounting summaries.
Hardware and Equipment Costs
If you purchase or lease point-of-sale (POS) systems, card readers, or terminals, these costs are also deductible. Under Section 179 of the tax code, businesses can often deduct the full purchase price of qualifying equipment in the year it was placed in service, rather than depreciating it over several years. This is particularly relevant in 2026 as hardware becomes more integrated with sophisticated AI-driven inventory and customer management systems.
Incidental and Penalty Fees
Even the less pleasant aspects of credit card processing are deductible. Chargeback fees—the penalties applied when a customer disputes a charge—and NSF (non-sufficient funds) fees are considered business losses or operational expenses. Similarly, if you pay a fee for "instant deposits" to move your funds from the processor to your bank account faster, that convenience fee is a deductible expense.
Reporting Requirements by Business Entity
The method for claiming these deductions varies depending on how your business is legally structured. While the deductibility of the fee remains constant, the specific form you use changes.
Sole Proprietorships and Single-Member LLCs
If you are a freelancer or a solo business owner, you will typically report these fees on Schedule C (Form 1040). Processing fees are usually categorized under "Part II: Expenses" on Line 25 (Utilities) or, more accurately, Line 10 (Commissions and fees) or Line 27 (Other expenses). Consistency is key; the IRS prefers that you categorize the expense the same way every year.
Partnerships and Multi-Member LLCs
Partnerships report their business expenses on Form 1065. The credit card processing fees are subtracted from the gross receipts or sales on the first page of the return. The resulting net income is then distributed to partners via Schedule K-1.
Corporations (C-Corps and S-Corps)
Corporations use Form 1120 (C-Corps) or Form 1120-S (S-Corps). Merchant fees are typically listed under "Other Deductions." It is advisable to maintain a detailed ledger that separates "Bank Service Charges" from "Merchant Processing Fees" to provide a clear audit trail.
Rental Property Owners
If you use a credit card processor to collect rent for a property you own, you would report the processing fees on Schedule E. These fees reduce the total rental income subject to tax, which is vital for maintaining the profitability of real estate investments in the 2026 market.
Comparison of Common Processing Fee Structures and Their Tax Impact
| Fee Structure | Typical Components | Deduction Method | Best For |
|---|---|---|---|
| Flat-Rate | Single % + fixed cent fee (e.g., 2.6% + $0.10) | Total annual fees deducted as a single line item. | Small businesses with low volume. |
| Interchange-Plus | Wholesale cost + processor markup (e.g., 0.20% + $0.10) | Requires detailed reconciliation of monthly statements. | High-volume businesses seeking transparency. |
| Subscription-Based | 0% markup + high monthly membership fee. | Monthly fee and per-transaction "direct costs" are both deductible. | Large enterprises with high average tickets. |
| Tiered Pricing | Qualified, Mid-Qualified, and Non-Qualified rates. | Often more expensive; full cost is deductible but harder to audit. | Not recommended for most modern businesses. |
The Critical Distinction: Personal vs. Business Expenses
One of the most common mistakes taxpayers make is attempting to deduct fees associated with personal credit card use. Following the Tax Cuts and Jobs Act (TCJA), which remains a foundational element of tax law in 2026, the deduction for "unreimbursed employee expenses" and most personal miscellaneous deductions was eliminated for individual filers.
If you are an individual using a personal credit card for daily living expenses, you cannot deduct the annual fee, late fees, or interest charges. However, if you are a business owner using a dedicated business credit card, the interest on that card is deductible as a business expense, and the annual fee is also deductible.
The "Co-Mingling" Trap: If you use a single card for both business and personal expenses, you may only deduct the portion of the fees and interest directly attributable to business purchases. This requires meticulous record-keeping and is a frequent target during audits. The most effective way to ensure your deductions are safe is to maintain entirely separate accounts and cards for business operations.
Reconciling the 1099-K Form
As a business owner accepting credit cards, you will likely receive a Form 1099-K from your processor if you meet the federal or state reporting thresholds. In 2026, the IRS continues to use this form to cross-reference the gross receipts reported by merchants against the data provided by payment settlement entities.
It is important to remember that the amount reported on Form 1099-K is the gross amount of all reportable payment transactions. This means the number on the form does not account for:
- Credit card processing fees.
- Refunds or credits.
- Chargebacks.
When you file your taxes, you report the gross amount from the 1099-K as your income, and then you list the processing fees as a deduction. You do not simply "net out" the fees before reporting the income. Doing so will result in a discrepancy between your tax return and the 1099-K the IRS has on file, which can trigger an automated notice or audit.
Navigating Surcharges and Cash Discounts
In recent years, many businesses have begun implementing surcharges (adding a fee to credit card transactions) or cash discounts (offering a lower price for cash) to offset the cost of processing. This has significant tax implications.
If you charge a customer a 3% surcharge to cover the processing fee, that 3% is considered gross income. You must report it as part of your total sales. However, you then deduct the 3% (or whatever amount the processor actually charges you) as an expense. While the net effect on your bank account might be zero, the accounting must reflect both the income and the expense.
For example, if you sell an item for $100 and add a $3 surcharge, your gross income is $103. If the processor takes $2.90 in fees, you deduct that $2.90. Your taxable profit is $100.10. Failing to report the surcharge as income while still deducting the fee is a violation of tax reporting standards.
Record-Keeping Best Practices for 2026
The burden of proof for any deduction rests with the taxpayer. Given the digital nature of 2026 commerce, "shoeboxes of receipts" have been replaced by digital archives. To survive an IRS inquiry regarding your merchant fees, you should maintain:
- Monthly Processing Statements: These are the gold standard for evidence. They break down transaction volume, interchange fees, and administrative charges.
- Merchant Agreements: Keep a copy of your contract with the processor to prove the legitimacy of the fee structure.
- Bank Statements: Use these to verify that the net deposits align with the gross sales minus the fees reported on your statements.
- Software Integrations: If your POS system (like Shopify or Clover) syncs with accounting software (like QuickBooks or Xero), ensure the "mapping" of fees is correct so they are automatically funneled into the correct deduction category.
The IRS generally recommends keeping these records for at least three years from the date you filed your original return or two years from the date you paid the tax, whichever is later. For businesses with higher complexities, a seven-year retention policy is often safer.
Frequently Asked Questions
Are annual fees on business credit cards deductible?
Yes. If the credit card is used exclusively for business purposes, the annual fee is considered a necessary expense for maintaining the line of credit required to operate the business. This is reported under "Other Expenses" or "Bank Service Charges" on your tax return.
Can I deduct the interest on my business credit card?
Yes, but only the interest on purchases made for the business. If you carry a balance on a business card for a piece of equipment or inventory, the interest accrued is a deductible business interest expense. However, if the card is used for personal expenses, that portion of the interest is not deductible.
What if my processor takes the fee before I get the money?
This is known as "net settling." Even if the money never hits your bank account because the processor deducted it at the source, it is still a deductible expense. You must report the full amount the customer paid as income and then deduct the amount the processor kept as a fee.
Are fees for international "cross-border" transactions deductible?
Yes. When you accept a payment from a customer using a non-domestic card, processors often charge an additional 1% to 1.5% cross-border fee. Because this is a cost of doing business in a global economy, it is fully deductible under the same "ordinary and necessary" rules as standard domestic fees.
Is the cost of PCI compliance certification deductible?
Yes. Whether you pay a monthly fee to your processor for PCI compliance or you hire a third-party security firm to audit your systems, these costs are deductible. In 2026, maintaining data security is considered a standard operational requirement for any business handling sensitive customer information.
Final Recommendation
To ensure you are capturing every dollar of potential deductions, review your merchant statements at the end of each quarter. It is common for processors to introduce new "ancillary" fees—such as network integrity fees or digital enablement fees—that may be buried in the fine print. By categorizing these costs correctly as business expenses, you significantly lower your effective tax rate. If you are unsure about the categorization of a specific charge, consult with a certified tax professional who can ensure your filings comply with the latest 2026 IRS regulations.