Agent onboarding software for life insurance is a specialized digital ecosystem designed to automate the recruitment, licensing, contracting, and appointment of insurance producers. By integrating with national databases like NIPR, these platforms verify credentials in real-time, eliminate manual paperwork, and ensure agents are legally compliant to sell products across multiple jurisdictions.
In the competitive landscape of 2026, the speed at which a life insurance carrier or Independent Marketing Organization (IMO) can move an agent from "interested candidate" to "ready-to-sell" is a primary driver of revenue growth. Traditional manual onboarding processes—rife with paper forms, wet signatures, and fragmented communication—often take weeks, leading to high "drop-off" rates among top-tier producers. Modern agent onboarding software transforms this bottleneck into a streamlined, digital-first experience that protects compliance while accelerating time-to-market.
The Evolution of Agent Onboarding in the Life Insurance Sector
The life insurance industry faces unique regulatory hurdles that distinguish its onboarding requirements from other financial sectors. Producers must not only be licensed in their resident state but also hold non-resident licenses for every state in which they solicit business. Furthermore, they must be "appointed" by specific carriers and often complete product-specific training or Anti-Money Laundering (AML) certifications before a single policy can be issued.
As of 2026, the industry has shifted away from standalone document storage toward integrated Compliance-as-a-Service models. Modern software does more than just host PDFs; it actively monitors the status of a producer’s credentials. If a license expires or a regulatory action is taken against a producer, the software automatically alerts the compliance department and can "hard-stop" the agent’s ability to submit new business.
Why Digital Transformation is No Longer Optional
For agencies and carriers, the cost of manual processing is no longer just an administrative burden; it is a strategic liability. Producers in 2026 expect a "one-and-done" data entry experience. If an agent is forced to provide their Social Security number, background history, and banking information five different times for five different carriers, they are likely to shift their loyalty to an IMO that utilizes a centralized onboarding platform.
Core Functional Components of Modern Onboarding Platforms
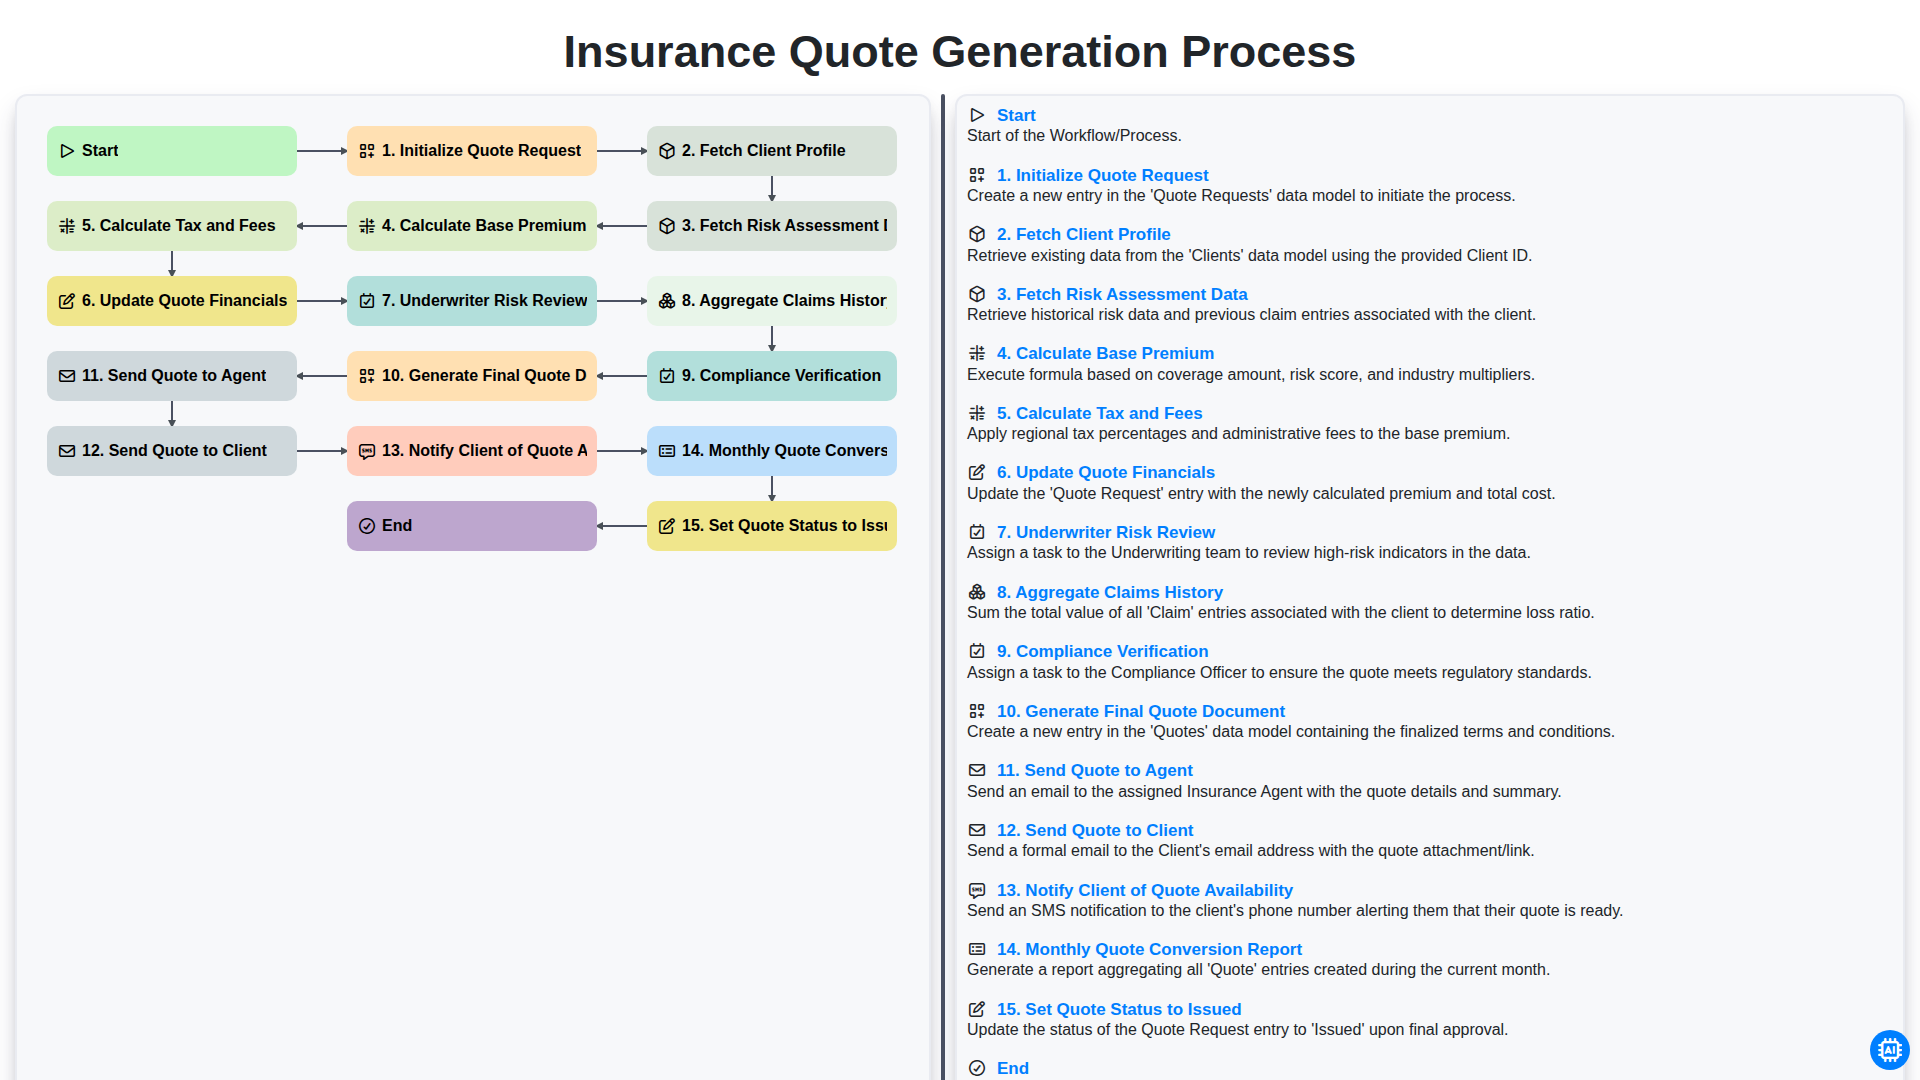
To be effective, agent onboarding software must address the entire lifecycle of the producer relationship. These systems are typically built on a foundation of several key modules.
1. NIPR Integration and Real-Time Verification
The National Insurance Producer Registry (NIPR) is the central hub for producer data in the United States. Advanced onboarding software maintains a persistent connection to the NIPR Gateway. This allows the system to automatically pre-fill producer applications using their National Producer Number (NPN).
Instead of asking an agent to list their active licenses, the software "pulls" this data directly from official records. This ensures 100% accuracy and alerts the onboarding team to any discrepancies, such as lapsed licenses or undisclosed disciplinary actions.
2. Automated Background and Debit Checks
Life insurance carriers must vet the financial reliability and criminal history of their representatives. Integration with services like Vector One (for debit checks) and criminal background check providers is standard in 2026. The software can automatically trigger these checks based on the agent's hierarchy or contract level, flagging any "hits" for manual review by the compliance officer.
3. Hierarchy and Commission Management
Life insurance distribution often involves complex hierarchies, including Managing General Agents (MGAs), General Agents (GAs), and street-level producers. Onboarding software must be "hierarchy-aware," meaning it can correctly map the reporting structure and ensure that commission overrides are accurately configured from day one. In 2026, the best platforms allow for drag-and-drop hierarchy adjustments that automatically update the contracting requirements for everyone downstream.
4. Just-In-Time (JIT) Appointment Processing
One of the most significant cost-saving features of modern software is the management of Just-In-Time appointments. In many states, a carrier does not need to pay an appointment fee to the state until the agent actually submits their first piece of business.
Smart onboarding software tracks which states allow JIT appointments and holds the appointment paperwork in a "pending" status until a policy application is received. This prevents carriers from wasting thousands of dollars in appointment fees for agents who never actually produce business.
Comparing Onboarding Methods: Manual vs. Automated (2026)
The following table illustrates the operational differences between legacy manual onboarding and modern automated software solutions.
| Feature | Manual/Legacy Process | Automated Onboarding Software |
|---|---|---|
| Data Entry | Duplicate entry across multiple forms | Single-entry; NIPR data pre-fill |
| License Verification | Manual lookup on state DOI websites | Real-time automated NIPR sync |
| Contracting Speed | 10–20 business days | 24–48 hours (or instant) |
| E-Signatures | Often requires physical mail or fax | Integrated (DocuSign, Adobe Sign, etc.) |
| Compliance Monitoring | Periodic manual audits | 24/7 automated alerts for lapses |
| Document Storage | Physical files or localized servers | Encrypted cloud-based document vault |
| Agent Experience | High friction; high drop-out rate | Low friction; mobile-responsive |
The Role of AI and Machine Learning in 2026 Onboarding
By 2026, Artificial Intelligence (AI) has moved from a buzzword to a functional component of insurance technology. In agent onboarding, AI is primarily used for document verification and risk scoring.
For example, when an agent uploads a copy of their errors and omissions (E&O) insurance certificate, Optical Character Recognition (OCR) combined with machine learning extracts the expiration date, coverage limits, and policy number. The system then compares this data against the carrier's minimum requirements. If the coverage is insufficient, the system immediately notifies the agent to upload a corrected document, removing the need for a human clerk to review the file.
Furthermore, predictive analytics can now "score" a new recruit based on their onboarding speed and historical NIPR data. Systems can identify patterns—such as producers who complete their onboarding in under four hours—as being highly likely to become "Top of the Table" producers, allowing agencies to prioritize their high-touch support resources effectively.
Security and Data Privacy Standards
Because agent onboarding software handles sensitive Information—including Social Security numbers, banking details for commission payments (ACH), and criminal histories—security is the highest priority.
In 2026, compliant software must adhere to:
- SOC 2 Type II Certification: Ensuring the service provider manages data securely to protect the interests of the organization and the privacy of its clients.
- CCPA/GDPR Compliance: Depending on the jurisdiction, software must allow agents to request data deletion or porting.
- Encryption at Rest and in Transit: Utilizing AES-256 encryption standards to ensure that intercepted data is unreadable.
- Multi-Factor Authentication (MFA): Mandatory for all administrative users to prevent unauthorized access to the producer database.
Integration with the Broader Tech Stack
Onboarding software does not exist in a vacuum. To provide maximum value, it must integrate seamlessly with other core insurance technologies.
CRM Integration
Platforms like Salesforce (Financial Services Cloud) or AgencyBloc are often the primary workspace for recruiters. Onboarding software should "push" status updates back to the CRM. When an agent is "Ready to Sell," the CRM should automatically update the lead status, triggering a welcome email from the sales or training team.
Agency Management Systems (AMS)
Once an agent is appointed, their production data is tracked in an AMS. The onboarding software acts as the "source of truth" for the agent’s profile, ensuring that their payout information and tax documents (1099s) are consistent across all systems.
Learning Management Systems (LMS)
Many life insurance products require specific "Product Excellence" training. Onboarding platforms can gate the final appointment until the agent provides a completion certificate from an LMS, ensuring that no agent sells a complex product like Indexed Universal Life (IUL) without proper education.
Implementation Strategy: Moving to a Digital Model
Transitioning to a dedicated onboarding platform requires more than just a software license; it requires a shift in organizational workflow.
- Workflow Mapping: Before implementation, organizations must document every step of their current process, identifying where "bottlenecks" occur.
- Configuration of Rules Engines: Every carrier has different requirements. The software must be configured with "rules" that dictate which documents are required for which product lines and states.
- Data Migration: If moving from an old system, existing producer data must be cleaned and migrated. This is often the most time-consuming phase but is critical for maintaining historical compliance records.
- Training and Adoption: Internal staff must be trained on how to manage "exceptions"—the cases where the automated system flags a producer for manual review.
Addressing Common Challenges and Troubleshooting
Despite the efficiency of these systems, technical and regulatory challenges can arise.
- NIPR Data Discrepancies: Occasionally, a state Department of Insurance (DOI) may be slow to update NIPR. Most 2026 software allows for "manual overrides" where an admin can upload a screen-capture from a DOI website to temporarily satisfy a requirement.
- Legacy Browser Support: While most systems are mobile-first, some older agents may use outdated hardware. Choosing a platform with broad browser compatibility is essential for minimizing support tickets.
- Integration Failures: API connections between the onboarding software and a carrier’s back-end system can break. Robust platforms offer "retry logic" and detailed error logging to ensure that no producer "falls through the cracks" during a sync failure.
Looking Ahead: The Future of Producer Lifecycle Management
By the end of the decade, the concept of "onboarding" may disappear entirely, replaced by a Continuous Producer Identity. In this model, an agent’s credentials, production history, and compliance status follow them in a digital "wallet." When they join a new agency, they simply grant the agency permission to access their pre-verified profile, reducing onboarding time from days to seconds.
For now, organizations that invest in robust agent onboarding software for life insurance are positioning themselves to attract the best talent. In an industry where the producer is the primary customer, the quality of the onboarding experience is often the deciding factor in where an agent chooses to place their business.
Frequently Asked Questions
What is the average time to onboard a life insurance agent using software? With automated software, the initial data collection and licensing verification can happen in minutes. Depending on the carrier’s internal review process and state appointment rules, an agent can often be "Ready to Sell" in 24 to 48 hours, compared to the 15-30 days common in manual systems.
Can onboarding software handle multi-state licensing? Yes. One of the primary benefits is the ability to manage non-resident licenses. The software tracks the expiration dates for every state where the producer is active and can even facilitate the application for new non-resident licenses directly through the NIPR interface.
How does the software handle E&O insurance tracking? Most platforms include an automated tracking module for Errors and Omissions (E&O) insurance. The system sends automated email reminders to the agent 30, 60, and 90 days before their policy expires. If a policy lapses, the system can automatically suspend the agent's ability to submit business until a new certificate is uploaded.
Is this software compliant with the NAIC's Suitability in Annuity Transactions Model Regulation? Modern onboarding platforms include specific modules to track the training requirements mandated by the National Association of Insurance Commissioners (NAIC). This includes verifying that an agent has completed both the general 4-hour annuity training and the specific product training required by the carrier.
Does the software work for independent agents or only captive agents? It is designed for both. However, it is particularly valuable for Independent Marketing Organizations (IMOs) that work with thousands of independent agents who may be appointed with dozens of different carriers simultaneously.
What are the costs associated with agent onboarding software? Pricing is typically structured in one of two ways: a flat monthly fee based on the number of active producers, or a "per-transaction" fee for every new onboarding initiated. Many vendors in 2026 also charge a small fee for automated NIPR data refreshes to cover the costs of the NIPR gateway access.
Next Action: If you are an agency leader or compliance officer, your next step is to perform a "Time-to-Ready" audit. Track the number of days it takes for your last ten recruits to go from their first interview to their first policy submission. If that number exceeds five business days, it is time to evaluate an automated onboarding solution to prevent producer attrition.