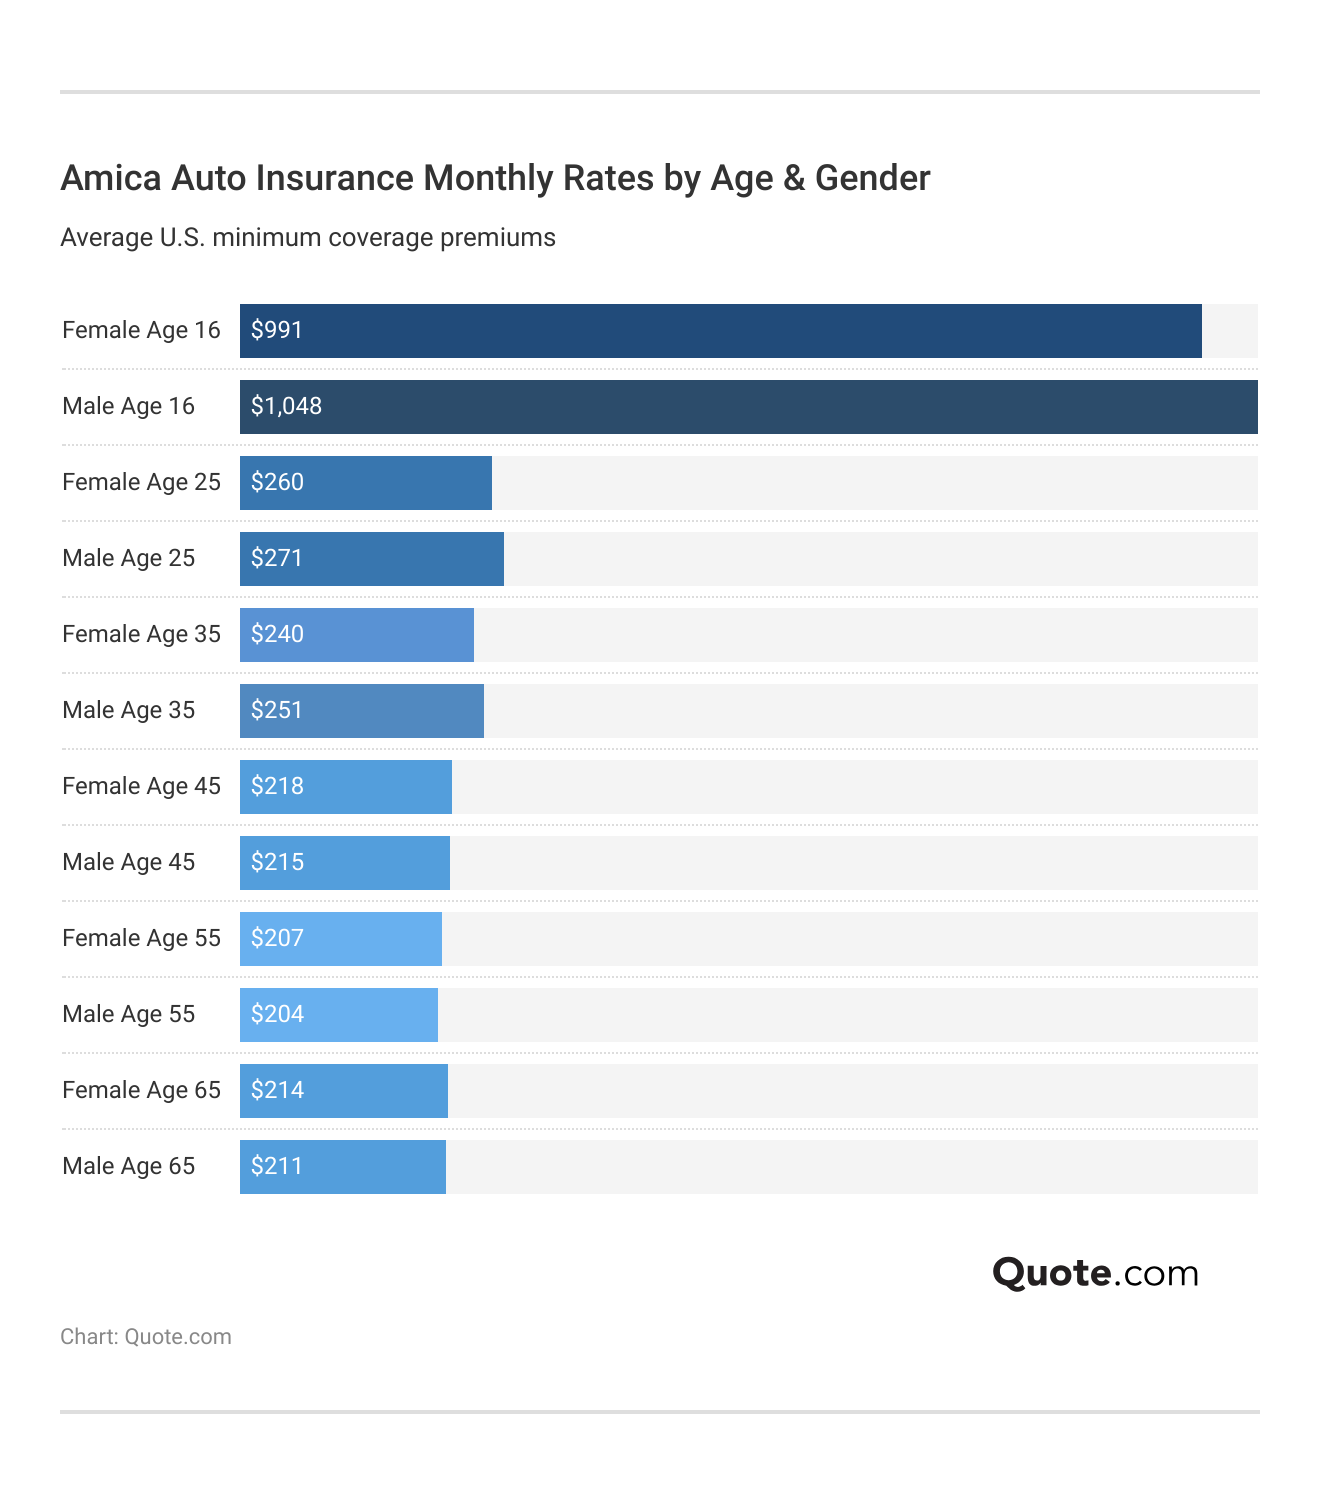
Amica Mutual Insurance provides comprehensive auto insurance coverage to North Carolina residents, emphasizing a high-service model often characterized by its dividend-paying policies and specialized customer support. Understanding how this carrier operates within the state’s specific regulatory and geographic landscape is essential for drivers evaluating whether Amica aligns with their personal risk profile and financial objectives.
Understanding the North Carolina Insurance Landscape
North Carolina operates under a unique regulatory environment managed by the North Carolina Department of Insurance (NCDOI). Unlike states that allow insurance companies to set their own base rates entirely independently, North Carolina utilizes a Rate Bureau system. All licensed auto insurers in the state, including Amica, are members of the North Carolina Rate Bureau (NCRB). This bureau periodically proposes rate adjustments for private passenger auto insurance, which must then be approved or negotiated by the Commissioner of Insurance.
Because of this systemic regulation, auto insurance premiums in North Carolina are more standardized than in many other states. However, this does not mean premiums are identical across all companies. Insurers retain the flexibility to apply their own "deviations"—adjustments to the bureau-set rates based on their specific claims experience, administrative costs, and the risk profiles of the drivers they choose to underwrite. Amica’s pricing in North Carolina is therefore a product of these bureau-approved baselines combined with their internal underwriting adjustments and dividend programs.
Core Coverage Requirements and Options
North Carolina law mandates that all vehicle owners maintain continuous liability insurance. Under North Carolina General Statute § 20-309, you must prove financial responsibility to register a vehicle and maintain it throughout the entire period the registration is valid.
Minimum Liability Limits
As of 2026, the state-mandated minimum coverage requirements for bodily injury and property damage are as follows:
- Bodily Injury (Per Person): $30,000
- Bodily Injury (Per Accident): $60,000
- Property Damage (Per Accident): $25,000
While these are the legal minimums, many experts advise against carrying only these amounts. In the event of a significant accident, these limits can be exhausted quickly, leaving the policyholder personally liable for the remaining costs. Amica offers options to increase these limits significantly, providing a higher layer of financial protection.
Beyond Liability
In addition to the state-mandated minimums, Amica provides several elective coverages common to the industry but managed through their specific claims and service infrastructure:
- Comprehensive Coverage: Protects against non-collision events like theft, fire, vandalism, and damage from falling objects or wildlife.
- Collision Coverage: Covers damages to your vehicle resulting from a collision with another vehicle or an object, regardless of fault.
- Medical Payments: Helps cover reasonable medical expenses for you or your passengers if injured in an accident, regardless of who caused it.
- Uninsured/Underinsured Motorist (UM/UIM): Critical in North Carolina, this coverage protects you if you are hit by a driver who lacks insurance or carries insufficient limits to cover your total losses.
The Amica Service Model and Dividend Program
A primary differentiator for Amica in the North Carolina market is its mutual company structure. As a mutual insurer, the company is technically owned by its policyholders. Historically, this has translated into their "dividend" program. While not guaranteed, Amica has a long-standing practice of returning a portion of premiums to eligible policyholders at the end of the policy term, effectively acting as a partial rebate.
When considering Amica in North Carolina, it is important to factor in the potential for these dividends when performing a price comparison. A premium that appears slightly higher at the outset may, over the course of a year, be more competitive once the dividend is factored into the net cost of the policy.
Claims Handling and Customer Service
Amica is frequently cited in industry surveys for its claims service efficiency. In North Carolina, they utilize a network of approved repair shops, though policyholders generally retain the right to choose their preferred mechanic. Their mobile app and online portal allow for digital claims submission, which can expedite the initial stages of an accident report.
Comparative Overview of Coverage Factors
When evaluating Amica against other providers operating in North Carolina, consider how various factors influence your specific premium and service experience.
| Feature | Amica Characteristics | North Carolina Context |
|---|---|---|
| Pricing Model | NCRB Base + Deviations | Highly regulated; uniform base rates. |
| Dividend Potential | Historical Annual Dividends | Unique to mutual structure; net cost benefit. |
| Claims Access | 24/7 Phone and Digital Portal | Standard industry availability. |
| Service Focus | High-touch / Customer-centric | Significant in complex claims scenarios. |
| Policy Flexibility | Standard and Add-on Options | Must meet state minimums at minimum. |
Steps to Verify Eligibility and Obtain a Quote
To secure auto insurance with Amica in North Carolina, you must undergo the standard underwriting process. Because North Carolina is a "fault-based" insurance state, your driving record, credit history (as permitted by state law), and the garaging address of your vehicle are the primary drivers of your individual rate.
- Gather Documentation: Have your current policy declarations page, driver’s license number, and Vehicle Identification Number (VIN) ready.
- Request a Quote: Utilize the Amica website or speak with a representative. Provide accurate information regarding your annual mileage and usage (commuting vs. pleasure).
- Verify State Compliance: Ensure that the policy includes the state-required "Proof of Insurance" (Form FS-1 or equivalent). Amica will electronically notify the North Carolina Division of Motor Vehicles (NCDMV) that you have secured the necessary coverage to validate your registration.
- Review Underwriting Adjustments: Inquire about specific discounts for which you may qualify, such as multi-policy discounts (bundling home and auto), multi-vehicle discounts, or defensive driving course completions.
Common Considerations and Potential Limitations
Every insurance provider has specific limitations. For Amica, prospective policyholders should be aware of the following:
- Eligibility Criteria: Amica often targets a specific tier of drivers. While they offer standard coverage, their underwriting guidelines may be stricter regarding driving history compared to high-risk or non-standard insurance providers.
- Regional Differences: North Carolina geography impacts premiums. Coastal areas may have different risk assessments for comprehensive coverage due to weather-related events compared to the Piedmont or Mountain regions.
- Not a "Lowest Price" Guarantee: Amica is generally positioned as a premium service provider. If your primary objective is the lowest possible monthly premium regardless of service level or stability, you may find that other providers—particularly those that specialize in non-standard insurance—offer lower initial quotes.
Frequently Asked Questions
Does Amica offer specific discounts for North Carolina drivers?
Yes, Amica provides several standard discounts that apply to their North Carolina policies. These typically include bundling discounts for home or renters insurance, discounts for safety features on your vehicle, and credits for remaining claim-free. Always ask your agent specifically which "deviations" or credits are applicable to your current zip code.
How does the North Carolina Rate Bureau affect my Amica premium?
The NCRB sets the base rates for all licensed insurers in the state. Amica, like all other companies, must file their rates with the Department of Insurance. While Amica cannot charge more than the bureau's set maximums without specific justification, they can choose to charge less. Your premium is the result of the base rate plus these competitive adjustments.
Is my dividend from Amica guaranteed?
No. Dividends are declared at the discretion of the company's board of directors based on financial performance and underwriting results. They are not guaranteed and should not be treated as a fixed discount when calculating your monthly budget.
What happens if I have an accident with an uninsured driver in North Carolina?
If you have Uninsured Motorist (UM) coverage, your policy will step in to cover your damages up to the limits of your policy. North Carolina requires that insurers offer UM coverage, and it is highly recommended to carry limits that mirror your liability coverage to ensure you are fully protected.
Can I manage my North Carolina policy entirely online?
Yes, Amica provides a robust online portal and mobile application. You can view your insurance ID cards, make payments, update your vehicle information, and initiate the claims process without needing to visit a physical office.
Final Recommendation for North Carolina Residents
If you are looking for an insurance partner that emphasizes long-term stability and a high standard of claims service, Amica is a strong candidate for your North Carolina auto insurance needs. Before finalizing your decision, request a formal quote and compare it against your current policy’s declarations page. Ensure you are comparing "apples to apples" by matching the liability limits and deductibles exactly.
When you receive the quote, evaluate it not just on the initial premium, but on the potential for dividends and the inclusion of necessary endorsements, such as gap insurance or rental car reimbursement, if those align with your vehicle’s value and your daily transportation requirements. Maintaining the required state minimums is the baseline; choosing a carrier that provides the most reliable support during a crisis is the final step in securing your financial well-being on North Carolina roads.