Alex Dorfman is a high-level financial professional and Partner at New York Life Insurance Company, specializing in strategic wealth management, insurance planning, and the recruitment of financial talent. His partnership with New York Life leverages the firm’s mutual structure to provide clients and emerging advisors with institutional-grade resources, financial protection, and long-term capital growth strategies.
The Professional Profile of Alex Dorfman
Within the financial services industry, Alex Dorfman has established a reputation grounded in the "General Office" structure of New York Life. As a Partner, Dorfman operates at a leadership level that bridges the gap between individual client advisory and the corporate infrastructure of one of the world's largest mutual insurers. His role is multifaceted: he functions as a mentor for new financial professionals while maintaining the high standards of practice required by a legacy institution.
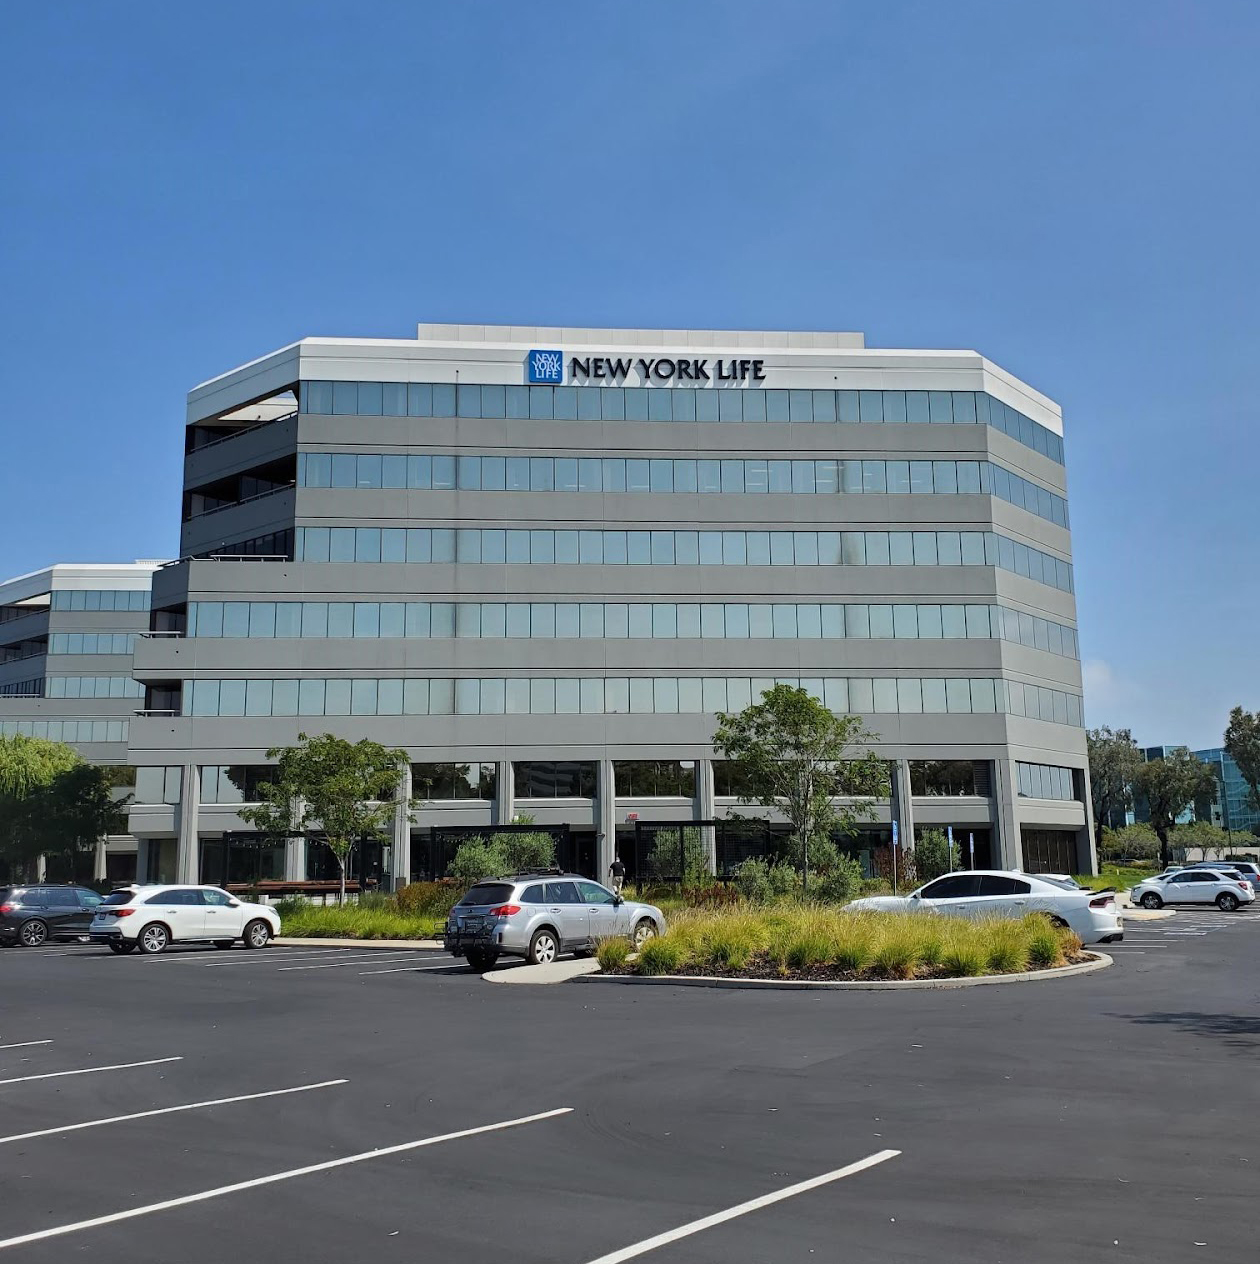
Dorfman’s professional focus typically centers on the New York Life Long Island General Office. This location serves as a hub for regional financial operations, where the partnership model is used to develop comprehensive financial strategies for families and business owners. His approach is often characterized by a "protection-first" philosophy, which posits that wealth accumulation is only sustainable when supported by a robust foundation of risk management.
By 2026, the demand for personalized financial guidance has intensified. Dorfman’s role involves navigating complex economic variables, including fluctuating interest rates and tax law evolutions, to ensure that his clients' portfolios remain resilient. His expertise is not limited to product sales; it extends to macro-financial coordination, where life insurance is used as a versatile tool for tax-efficient wealth transfer and supplemental retirement income.
Decoding the New York Life Partnership Model
The term "partnership" in the context of Alex Dorfman and New York Life refers to a specific career and operational track within the company. Unlike traditional corporate hierarchies, New York Life’s partnership track is designed for high-performing individuals who demonstrate an aptitude for both financial advisory and team leadership.
In this model, a Partner is responsible for identifying, hiring, and training the next generation of financial professionals. For a client, this means that working with a professional like Alex Dorfman provides access to a leader who is deeply embedded in the company’s culture and operational standards. For an aspiring agent, the partnership signifies a mentorship-based environment where they are trained in the "Financial Needs Analysis" (FNA) process.
The partnership is reinforced by New York Life’s status as a mutual company. This means the company is not publicly traded on a stock exchange; rather, it is owned by its policyholders. This structure aligns the interests of the Partners, the agents, and the clients. Because there are no outside shareholders demanding short-term quarterly profits, Partners like Dorfman can focus on long-term financial stability and the payment of dividends to eligible policyholders—a streak New York Life has maintained since 1854.
Core Financial Solutions: Life Insurance and Risk Management
At the heart of the Dorfman and New York Life partnership is a suite of insurance products designed to mitigate various life risks. These products are often classified into three primary categories, each serving a distinct purpose in a 2026 financial plan.
Whole Life Insurance
Whole life insurance remains the flagship product of the New York Life portfolio. It provides permanent protection with a guaranteed death benefit, guaranteed level premiums, and guaranteed cash value growth. For clients working with Dorfman, whole life is often utilized as an asset class rather than just an expense. The cash value grows tax-deferred and can be accessed via policy loans for opportunities like business expansion, college funding, or emergency reserves.
Term Life Insurance
For clients needing maximum protection at the lowest initial cost, term insurance offers coverage for a specific period (typically 10, 15, or 20 years). Dorfman’s strategies often involve "laddering" term policies or using them as a temporary solution until a client’s cash flow allows for a conversion to a permanent policy. New York Life’s term products are particularly valued for their conversion privileges, allowing policyholders to switch to permanent coverage without a new medical exam.
Universal Life and Variable Universal Life
These products offer more flexibility in premium payments and death benefits. Variable Universal Life (VUL) allows the policyholder to invest the cash value in various sub-accounts, similar to mutual funds. This introduces market risk but offers the potential for higher growth. Dorfman’s role involves ensuring that the "suitability" of these products matches the client’s risk tolerance and long-term objectives.
Wealth Management and Retirement via NYLIFE Securities
Beyond traditional insurance, the partnership between Alex Dorfman and New York Life extends into the realm of investments through NYLIFE Securities LLC (a member of FINRA and SIPC). As a Registered Representative, Dorfman can facilitate access to a broad array of investment vehicles.
This integrated approach allows for the creation of a "Retirement Income Strategy." In 2026, where traditional pensions are increasingly rare, Dorfman helps clients engineer their own "personal pensions" using guaranteed internal annuities. These products are designed to provide a lifetime stream of income, protecting retirees against "longevity risk"—the danger of outliving their savings.
The investment philosophy often focuses on:
- Asset Allocation: Diversifying across equities, fixed income, and cash equivalents.
- Tax Diversification: Balancing taxable, tax-deferred (like 401ks), and tax-free (like Roth IRAs or life insurance cash value) buckets of money.
- Legacy Planning: Ensuring that wealth is passed to the next generation with minimal "leakage" to estate taxes or probate costs.
The Mutual Company Advantage in 2026
The stability of the partnership is anchored by New York Life’s financial strength. In the economic landscape of 2026, "flight to quality" is a dominant trend. New York Life consistently earns the highest possible financial strength ratings from the four major rating agencies: A.M. Best (A++), Fitch (AAA), Moody’s (Aaa), and Standard & Poor’s (AA+).
| Feature | New York Life Mutual Model | Publicly Traded Insurers |
|---|---|---|
| Ownership | Policyholders (Members) | Stockholders/Shareholders |
| Primary Goal | Long-term stability & member value | Quarterly earnings & share price |
| Dividends | Paid to eligible policyholders (not guaranteed) | Paid to stockholders |
| Governance | Board elected by policyholders | Board elected by shareholders |
| Capital Management | Conservative, surplus-focused | Often driven by buybacks and dividends |
For clients of Alex Dorfman, this table illustrates why the partnership is viewed as a "safe harbor." The ability of New York Life to maintain its dividend scale even during periods of market volatility is a testament to the conservative management that Dorfman represents.
The Client Experience: Working with a New York Life Partner
Engaging with Alex Dorfman or a member of his team typically follows a structured, consultative process. This ensures that recommendations are data-driven rather than product-driven.
- Discovery Phase: An initial meeting to identify goals, concerns, and current financial standing. This includes a review of existing insurance policies, investment accounts, and estate documents.
- Analysis and Design: Dorfman and his team use proprietary New York Life software to model different scenarios. This might include "stress-testing" a retirement plan against high inflation or a prolonged market downturn.
- Strategy Presentation: The client is presented with a customized roadmap. This includes specific recommendations for coverage amounts, policy types, and investment allocations.
- Implementation: Once a strategy is agreed upon, the team handles the underwriting process for insurance and the account setup for investments.
- Ongoing Review: Financial planning is not a one-time event. Dorfman emphasizes annual reviews to adjust for life changes, such as marriage, the birth of a child, or a business sale.
Technical Specifications and Compliance
As a Partner in a highly regulated industry, Alex Dorfman operates under strict oversight. His partnership with New York Life requires adherence to both state insurance laws and federal securities regulations.
- FINRA Oversight: As a registered representative, his professional conduct is tracked via the Financial Industry Regulatory Authority (FINRA). Clients can verify his history and credentials through the FINRA BrokerCheck system.
- Fiduciary vs. Suitability: Depending on the specific service provided, the standard of care may vary. For investment advisory services, the professional is often held to a fiduciary standard (acting in the client’s best interest), while for insurance products, a high "suitability" standard is maintained.
- Continuing Education: To maintain his partnership status, Dorfman must complete ongoing training in ethics, product knowledge, and regulatory changes, ensuring his advice remains relevant in 2026.
Frequently Asked Questions
What is the difference between a New York Life Agent and a Partner?
An Agent is primarily focused on working directly with clients to solve financial needs. A Partner, like Alex Dorfman, is a leadership role. While Partners still work with clients, they are also responsible for the growth of the General Office, which includes recruiting, hiring, and developing new agents. They are essentially "business developers" within the New York Life ecosystem.
How are Alex Dorfman and his team compensated?
Compensation typically comes through a combination of commissions from insurance product sales and fees for investment management services. New York Life provides transparency through "Illustration" documents for insurance and "Form CRS" (Customer Relationship Summary) for investment services, detailing all costs and potential conflicts of interest.
Can Alex Dorfman help with business succession planning?
Yes. A significant portion of the Dorfman partnership's work involves business owners. This includes setting up "Buy-Sell Agreements" funded by life insurance, creating "Key Person" insurance strategies, and implementing executive bonus plans (Section 162 plans) to retain top talent.
Is New York Life a good choice for someone looking for a career change in 2026?
Under the leadership of a Partner like Alex Dorfman, New York Life offers a comprehensive training program for career changers. The "Partnership" model is designed to support new professionals with a combination of classroom learning and field mentorship, making it a viable path for those looking to build a local financial practice.
What happens to my policy if Alex Dorfman retires or leaves the company?
Because the partnership is with New York Life, your contract is with the insurance company itself, not the individual agent. If a professional leaves, New York Life’s General Office structure ensures that your account is assigned to another qualified representative to provide uninterrupted service.
Final Recommendation: Next Actions
If you are considering working with Alex Dorfman or exploring the New York Life partnership, your first step should be a preliminary consultation. For clients, this is an opportunity to evaluate the compatibility of your financial goals with the company's mutual philosophy. Ensure you have your current financial statements and existing insurance policies ready for a "gap analysis."
For those interested in the professional partnership track, the next action is to schedule an interview with the Long Island General Office. This allows you to vet the mentorship style and resources provided by Dorfman’s leadership team. In either case, verifying credentials via FINRA BrokerCheck and the New York Department of Financial Services is a recommended standard of due diligence.