Finding affordable auto insurance in Springfield, Missouri requires balancing state legal mandates with local risk factors like Ozark weather patterns, college town traffic, and regional accident rates. Driver premiums in Greene County vary significantly depending on coverage limits, driving history, and insurer pricing models, with minimum coverage starting at lower baseline rates and full coverage providing crucial financial protection against severe storms and highway collisions.
Disclaimer: This guide provides general educational information regarding auto insurance guidelines and rates in Missouri. Insurance regulations, state laws, and individual premium rates are subject to change. For legal advice or personalized coverage recommendations, consult a licensed insurance agent or the Missouri Department of Commerce and Insurance.
Understanding Missouri Auto Insurance Laws and Minimum Requirements
Missouri operates under a standard fault-based (tort) insurance system. If you cause an auto accident in Springfield, you are financially responsible for injuries, medical bills, and property damage suffered by other parties. To legally operate a vehicle in Missouri, drivers must maintain minimum financial responsibility through auto liability insurance.
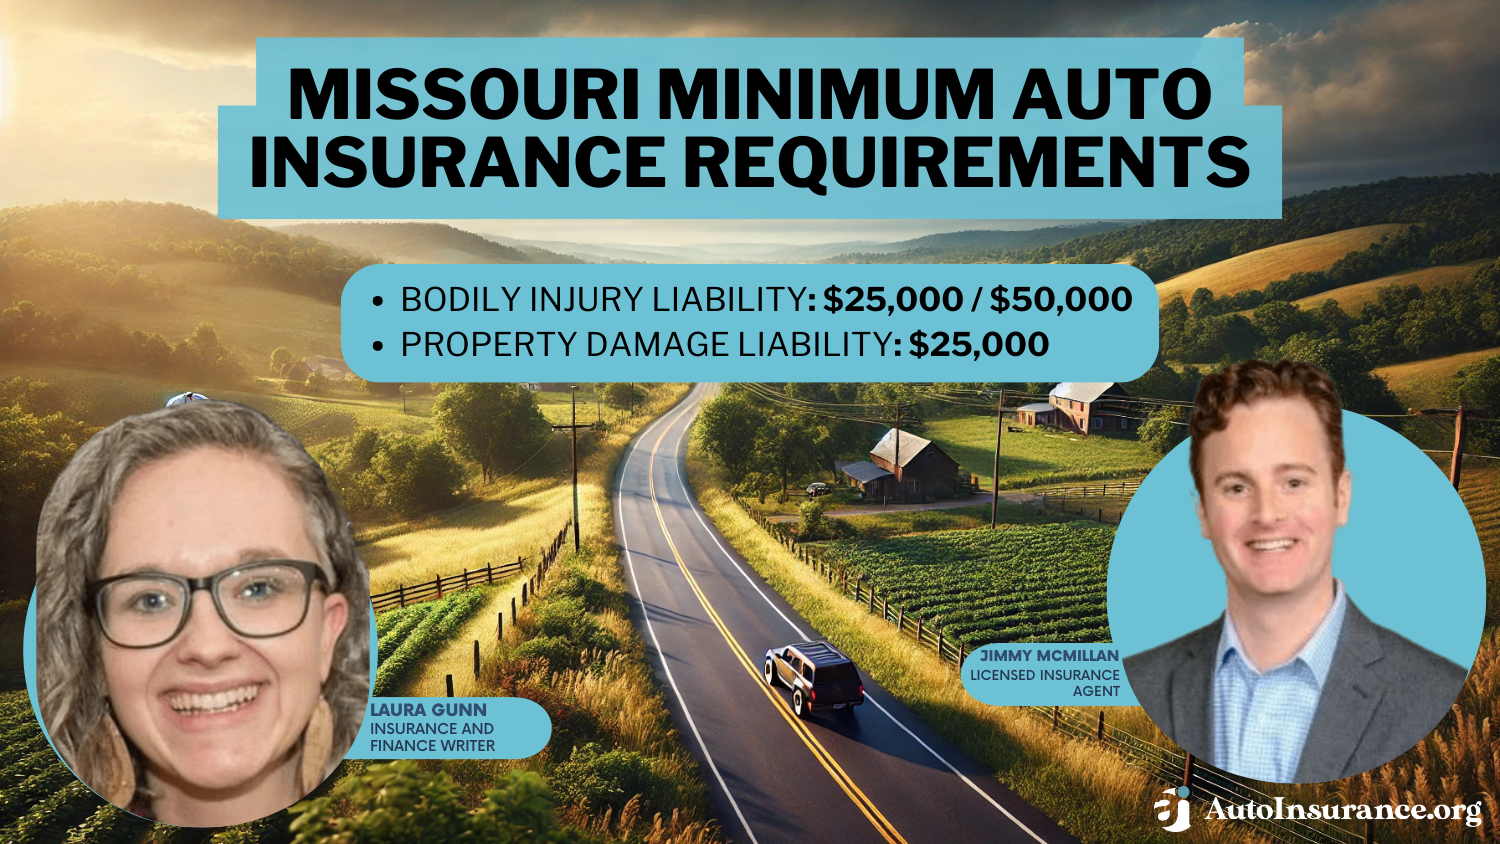
According to the Missouri Department of Revenue, the state requires drivers to carry the following minimum liability limits, often referred to as "25/50/25" coverage:
- $25,000 for Bodily Injury Liability per person: Covers medical expenses and legal costs if an individual is injured in an accident you cause.
- $50,000 for Bodily Injury Liability per accident: The total payout limit for medical expenses per accident, regardless of how many people are injured.
- $25,000 for Property Damage Liability per accident: Pays for damage caused to another person’s vehicle, building, or property.
Mandatory Uninsured Motorist Coverage
Unlike many states where uninsured motorist protection is optional, Missouri law requires all auto policies to include Uninsured Motorist (UM) Bodily Injury coverage.
- $25,000 per person / $50,000 per accident: Protects you, your passengers, and household family members if you are hit by a driver who carries no insurance, or by a hit-and-run driver.
Underinsured Motorist (UIM) coverage—which compensates you when an at-fault driver's policy limits are insufficient to pay for your damages—is optional in Missouri, though strongly recommended due to high healthcare costs and vehicle repair expenses.
Is Minimum Coverage Enough for Springfield Drivers?
While purchasing minimum legal coverage satisfies state mandates, relying solely on 25/50/25 limits leaves drivers exposed to substantial out-of-pocket financial liability. A multi-vehicle crash on I-44 or the James River Freeway can easily exceed $50,000 in combined medical bills or $25,000 in property damage. Once policy limits are exhausted, injured parties can pursue personal assets, wages, and savings.
Key Factors Influencing Springfield Car Insurance Rates
Car insurance premiums in Springfield, MO are calculated using complex actuarial algorithms that combine statewide statistics with hyper-local risk data across Greene County.
| Key Rating Factors in Springfield, MO | Details |
|---|---|
| Local Traffic & Commute Patterns | High-volume routes (I-44, US-65) |
| Severe Ozark Weather Risks | Severe hail, tornadic storms |
| Zip Code & Crime Rates | Vandalism, theft (65802, 65807) |
| Campus Area Dynamics | MSU, Drury, OTC student traffic |
| Personal Credit & Driving History | Insurance score, MVR record |
1. Local Traffic and Commuting Patterns
Springfield serves as the economic and medical hub of Southwest Missouri. Key arteries such as Glenstone Avenue, Sunshine Street, Battlefield Road, and the Chestnut Expressway experience high daily traffic volumes. Merging corridors along Interstate 44 and U.S. Route 65 see frequent high-speed accidents, raising collision claims across local zip codes.
2. Severe Weather in the Ozarks
Springfield experiences extreme weather throughout the year, including severe convective thunderstorms, destructive hail, high winds, and winter ice storms. Hail damage represents one of the largest driver claim categories in Southwest Missouri. Comprehensive insurance coverage is essential for repairing dented auto bodies and cracked windshields caused by severe weather events.
3. Regional Uninsured Driver Rates
Data from the Insurance Information Institute indicates that a significant percentage of drivers nationwide operate vehicles without liability insurance. In Missouri, high uninsured driver rates directly inflate UM coverage premiums and prompt insurers to raise base liability rates to offset uncompensated accident costs.
4. College Town Dynamics
Home to Missouri State University (MSU), Drury University, and Ozarks Technical Community College (OTC), Springfield hosts tens of thousands of student drivers each academic year. Younger drivers (ages 16–24) statistically file more claims, increasing localized accident risks around urban campuses and student housing zones along South National Avenue and Kimbrough Avenue.
5. Neighborhood and Zip Code Variances
Insurance rates vary slightly depending on your exact Springfield neighborhood. Areas with higher rates of vehicle theft, vandalism, or uninsured parked-vehicle accidents (such as zip codes 65802, 65803, or 65806) may carry higher comprehensive premiums than quiet residential neighborhoods in 65804 or 65809.
Top Insurance Companies Serving Springfield, MO
Drivers in Springfield have access to national carriers, regional insurers, and local insurance agencies. Comparing quotes from multiple provider types helps identify competitive rates for your specific driver profile.
1. Regional and State Specialists
- Shelter Insurance: Headquartered in Columbia, Missouri, Shelter Insurance maintains a strong presence in Springfield. Known for strong local agent networks, competitive bundling discounts, and specialized rural/suburban coverage options.
- Missouri Farm Bureau Insurance: Offers competitive rates for Missouri residents, especially when combining auto with homeowners or farm property policies. Requires a small annual Farm Bureau membership fee.
2. Major National Carriers
- State Farm: As one of the largest auto insurers in Missouri, State Farm offers extensive local agent representation throughout Springfield, along with competitive rates for safe drivers and strong multi-policy discounts.
- GEICO: Direct-to-consumer model that often delivers lower baseline premiums for drivers with clean driving records, low annual mileage, or federal employee status.
- Progressive: Known for flexible coverage customization, competitive pricing for drivers with past moving violations, and the Name Your Price® tool.
- American Family Insurance (AmFam): Popular in the Midwest, offering tailored policies, strong claims processing, and generous driver safety discounts.
- Auto-Owners Insurance: Sold exclusively through independent insurance agents, auto-owners frequently receives high marks for customer service and claims handling satisfaction.
Comparison of Coverage Tiers and Costs in Springfield
Insurance costs depend heavily on the depth of protection selected. Below is a structured breakdown comparing common policy configurations available to Springfield drivers.
| Coverage Tier | Key Protection Features | Mandatory / Optional | Ideal Driver Profile | Estimated Monthly Cost Range |
|---|---|---|---|---|
| State Minimum Liability | 25/50/25 Liability + 25/50 Uninsured Motorist | Mandatory under MO Law | Drivers with low-value vehicles, limited personal assets, or severe budget limits | $35 – $65 |
| Standard Liability (50/100/50) | Higher liability limits; 50/100 Uninsured Motorist | Optional upgrade | Budget-conscious drivers with moderate income looking to protect against common asset claims | $55 – $95 |
| Full Coverage (Moderate Deductible) | 100/300/100 Liability + UM/UIM + Comprehensive & Collision ($500 Deductible) | Optional (Required by auto lenders/lessors) | Owners of financed, leased, or newer vehicles; daily commuters on I-44 / US-65 | $110 – $180 |
| Premium / High-Limit Coverage | 250/500/100 Liability + UM/UIM + Comprehensive & Collision ($250 Deductible) + Roadside & Rental | Optional | High-net-worth individuals, luxury vehicle owners, drivers needing total financial protection | $170 – $260+ |
Note: Monthly cost estimates are based on general regional actuarial data for adult drivers with clean records. Actual individual quotes vary based on vehicle model, age, exact zip code, credit score, and claim history.
Proven Strategies to Lower Auto Insurance Premiums
Reducing your car insurance costs in Springfield does not mean sacrificing vital protection. Implementing target savings tactics can dramatically lower your annual premium.
Actionable Savings Checklist
- Shop and compare at least 3-5 quote proposals annually
- Enroll in mobile usage-based / telematics tracking
- Bundle auto policy with homeowners, renters, or condo
- Raise deductible thresholds ($500 to $1,000)
- Maintain good standing on credit report & driving record
- Apply for good student or defensive driver discounts
1. Enroll in Telematics (Usage-Based Insurance)
Most major insurers in Missouri offer mobile app telematics programs (such as State Farm Drive Safe & Save, Progressive Snapshot, or GEICO DriveEasy). These programs monitor braking, acceleration, speed, cornering, and phone usage. Safe drivers in Springfield can earn initial policy sign-up discounts of 5% to 10%, with long-term savings reaching up to 30%.
2. Bundle Auto with Homeowners or Renters Coverage
Combining your auto insurance with a home, condo, or renters policy is one of the most effective ways to lower your rate. Renters insurance in Springfield is relatively inexpensive, and the multi-policy discount on your auto premium can often offset the cost of the renters policy entirely.
3. Adjust Comprehensive and Collision Deductibles
If your vehicle is financed, your lender requires comprehensive and collision coverage. Raising your deductible from $250 or $500 to $1,000 reduces your monthly premium significantly. However, ensure you maintain an emergency savings fund sufficient to cover the higher out-of-pocket cost in the event of an accident or storm damage.
4. Utilize Student and Alumni Discounts
With Springfield's large higher-education student body, insurance carriers offer multiple targeted savings opportunities:
- Good Student Discount: Full-time high school or college students (MSU, Drury, OTC) maintaining a 3.0 GPA ("B" average) or higher can qualify for 10% to 25% premium discounts.
- Distant Student Discount: If a student on your policy attends college more than 100 miles away from home without a personal vehicle, you can reduce their driver status cost.
- Alumni & Professional Associations: Select insurers offer group rates to alumni association members or specific professional credentials.
5. Improve Your Insurance Credit Score
In Missouri, state insurance regulations permit insurance companies to use credit-based insurance scores when calculating premiums. Maintaining a good credit profile (paying bills on time, keeping credit card balances low, monitoring credit reports for errors) lowers your risk rating and qualifies you for cheaper rates.
6. Drop Physical Damage Coverage on Older Vehicles
If your vehicle is fully paid off and its market value has dropped below $3,000 to $4,000, paying for collision and comprehensive insurance may not be cost-effective. Check your vehicle's current value via Kelley Blue Book or NADA. If annual comprehensive and collision premiums plus your deductible exceed the value of the car, switching to liability-only coverage can save hundreds of dollars each year.
High-Risk Auto Insurance and SR-22 Filings in Missouri
Drivers who have experienced major moving violations, DUIs/DWIs, severe at-fault accidents, or lapses in coverage face higher risk classifications and elevated rates.
What is an SR-22 in Missouri?
An SR-22 is not an insurance policy; it is an official certificate of financial responsibility submitted by an insurance company to the Missouri Department of Revenue Driver License Bureau. It verifies that a driver maintains the minimum state-required liability limits.
Common reasons an SR-22 filing is required in Springfield include:
- DWI or DUI convictions.
- Driving without valid liability insurance.
- Accumulation of excessive points on your Missouri driving record.
- Driving on a suspended or revoked license.
How to Obtain Cheap SR-22 Coverage
- Notify your insurer or seek specialized non-standard carriers: Not all insurance carriers write SR-22 policies. Companies like Progressive, Dairyland, The General, and Bristol West specialize in high-risk coverage.
- Maintain continuous coverage: Any gap or cancellation of an SR-22 policy triggers an immediate notification to the Missouri Department of Revenue, resulting in license suspension and reset of the mandatory filing period (typically three consecutive years).
- Consider Non-Owner SR-22 Policies: If you do not own a car but need to fulfill state license reinstatement requirements, a non-owner auto insurance policy with an SR-22 endorsement is significantly cheaper than standard vehicle owner insurance.
Step-by-Step Guide to Shopping for Auto Insurance in Springfield
Finding the cheapest, high-quality auto insurance policy requires systematic comparison shopping. Follow this process to secure the best rates in Springfield:
Auto Insurance Shopping Flowchart
Step 1: Audit Current Coverage – Review limits, deductibles, cost
Step 2: Determine Coverage Needs – Liability-only vs. Full Coverage
Step 3: Gather Personal Information – VINs, Driver Record, Miles
Step 4: Request 3 to 5 Quotes – Direct carriers & local agents
Step 5: Verify Discounts – Telematics, bundling, multi-car
Step 6: Select Policy & Cancel Old Coverage – Avoid coverage gaps
Gather Necessary Information: Have your vehicle identification number (VIN), vehicle make/model/year, estimated annual mileage, driver’s license numbers for all household members, and your current policy dec page ready.
Determine Your Required Coverage Level: Decide whether minimum liability, standard 50/100/50, or full coverage with storm protection fits your vehicle value and personal assets.
Collect Quotes from Multiple Sources: Obtain quotes directly online (from carriers like GEICO or Progressive), request quotes through regional captive agents (Shelter or State Farm), and consult an independent broker who can search multiple mid-tier insurance companies.
Confirm Discount Applications: Ensure quotes apply all eligible discounts, including paperless billing, automatic bank withdrawal (EFT), multi-vehicle savings, and safe driving records.
Check Regulatory Record: Confirm the insurance company is properly licensed and in good standing with the Missouri Department of Commerce and Insurance.
Bind New Policy Before Canceling the Old One: Establish your new effective start date before canceling your previous policy to prevent unintended gaps in coverage, which can lead to legal penalties and higher future rates.
Frequently Asked Questions (FAQ)
What is the average cost of auto insurance in Springfield, MO?
While exact rates depend on age, driving history, and credit, average monthly costs in Springfield range from $35 to $65 for state minimum coverage and $110 to $180 for full coverage on a modern vehicle.
Is full coverage required by law in Missouri?
No. Missouri state law only mandates liability coverage (25/50/25) and uninsured motorist coverage (25/50). However, if your vehicle is financed or leased through a bank or credit union in Springfield, your lender will mandate comprehensive and collision insurance to protect their financial interest.
Does severe weather in Springfield increase car insurance rates?
Yes. Southwest Missouri experiences frequent severe hail, high winds, and ice storms. Because comprehensive insurance pays for weather-related damage, localized claim history during high-storm years causes carriers to adjust comprehensive rates across Greene County zip codes.
How long do tickets stay on my Missouri driving record?
In Missouri, points assessed for moving violations typically remain on your record, but points are reduced by one-third if you drive for one year without receiving additional violations. Most auto insurance companies evaluate the past 3 to 5 years of your motor vehicle record (MVR) when calculating your premium rate.
Can I get insurance if I have a foreign or out-of-state driver's license in Springfield?
Yes. Many insurance companies operating in Springfield provide auto policies to college students, military personnel, and non-US citizens using valid out-of-state or international driver’s licenses. You may need to provide proof of local Springfield residency and vehicle registration documentation.
Final Recommendations for Springfield Drivers
To secure the most affordable auto insurance in Springfield without compromising protection, avoid purchasing baseline minimum limits if you own valuable assets or a newer vehicle. The financial gap between minimal liability and comprehensive 100/300/100 coverage is often modest compared to the catastrophic out-of-pocket expense of a severe accident or severe Ozark hail storm.
Take proactive steps to lower your rate: request quotes from at least three different companies every 12 to 18 months, enroll in usage-based driving apps, combine your auto policy with home or renters insurance, and keep your credit score healthy. By shopping strategically, drivers across Greene County can maintain strong financial protection at a budget-friendly price.