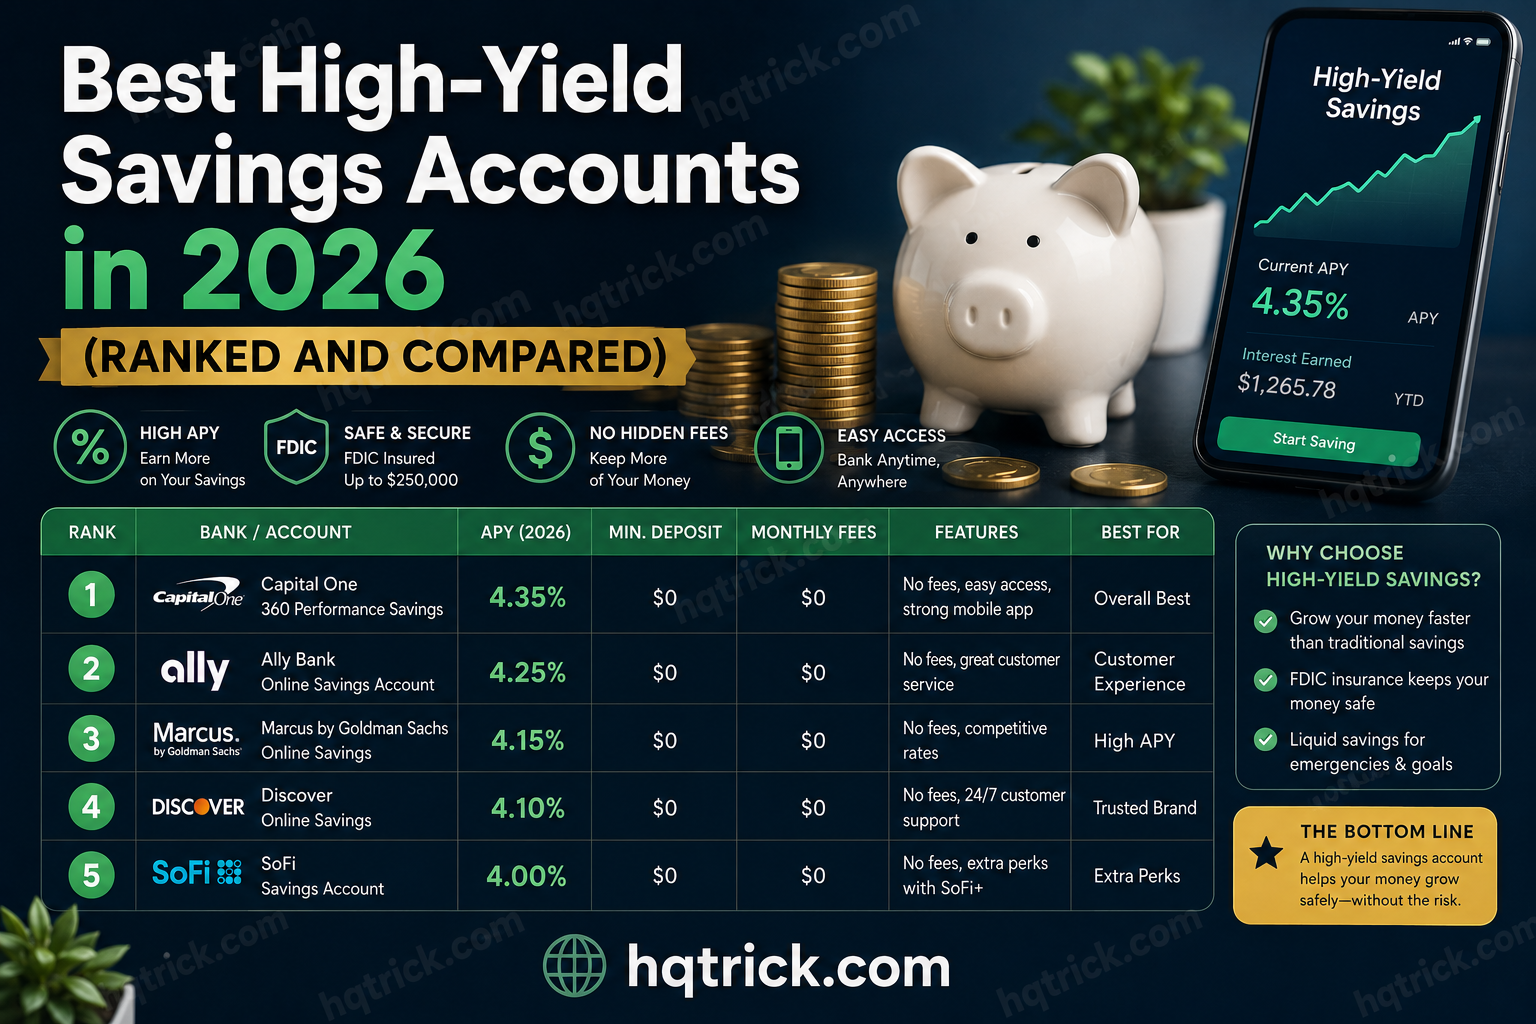
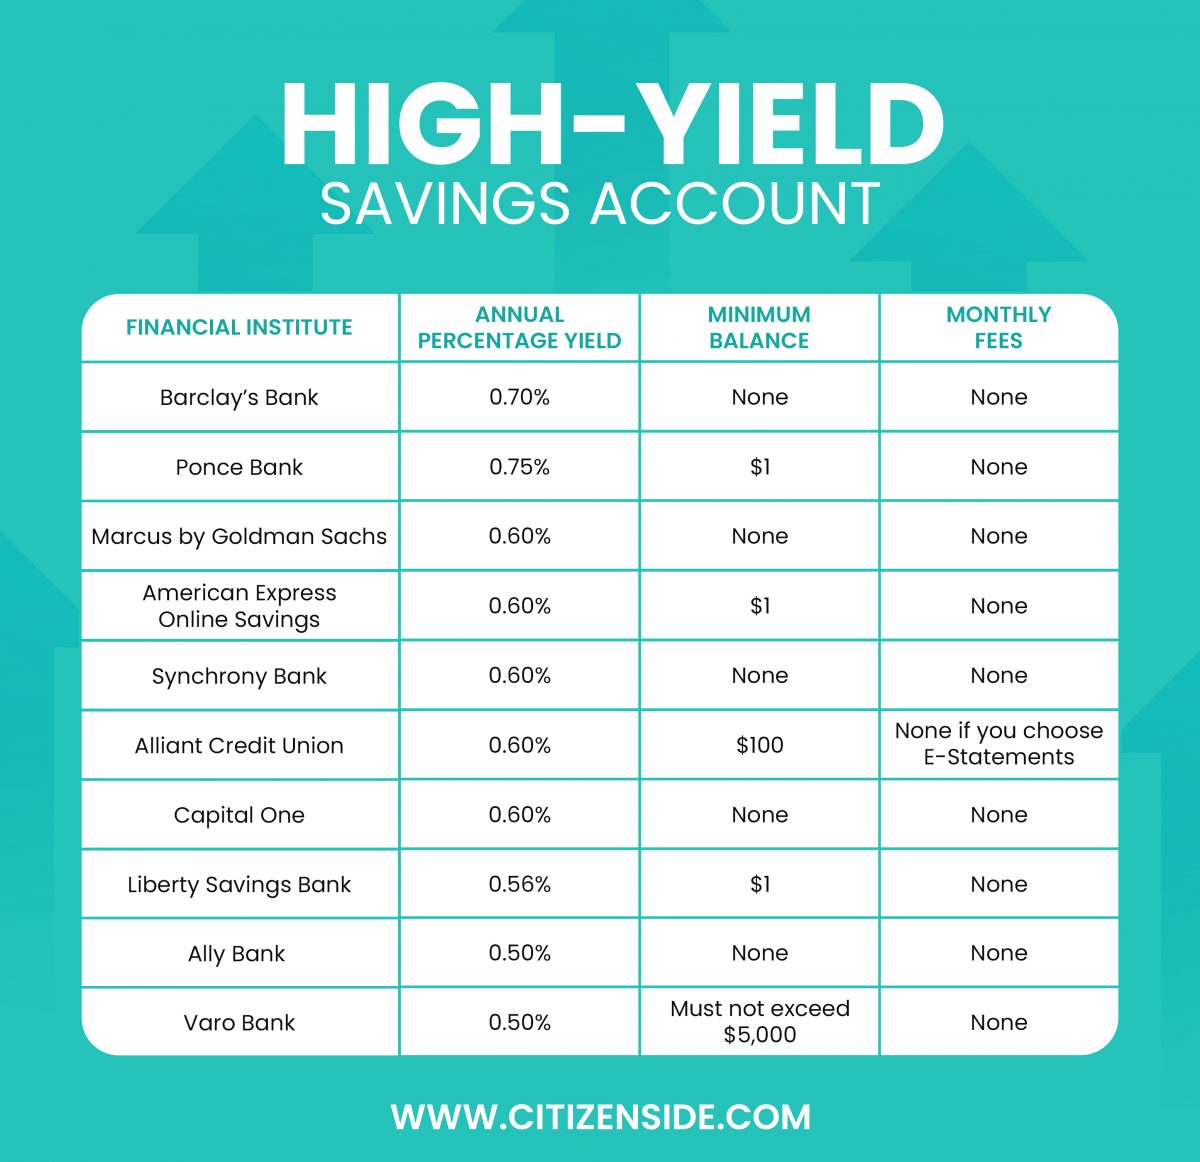
Online high yield savings accounts (HYSAs) are generally as safe as traditional brick-and-mortar savings accounts, provided the institution is insured by the Federal Deposit Insurance Corporation (FDIC) or the National Credit Union Administration (NCUA). These federal protections ensure your deposits are backed by the full faith and credit of the United States government up to $250,000 per depositor, per ownership category, per institution, minimizing the risk of loss due to bank failure.
Understanding the Mechanics of Safety
The perceived risk associated with online banks often stems from their lack of physical branches. However, the regulatory environment for digital-first financial institutions is identical to that of legacy banks. When you deposit money into an online HYSA, you are participating in a system governed by federal law. The safety of your capital does not depend on the presence of a tellers' window; it depends on the institution's charter and its membership in federal insurance programs.
The FDIC is an independent agency of the United States government. If a bank fails, the FDIC typically facilitates the sale of the failed bank to a healthy institution or pays depositors directly for their insured funds. Since the inception of the FDIC in 1933, no depositor has lost a penny of insured funds. The NCUA performs a similar function for credit unions through the National Credit Union Share Insurance Fund (NCUSIF).
Verifying Institution Legitimacy
Before opening an account, it is your responsibility to confirm that the bank is indeed insured. Not all financial institutions are created equal. Some fintech companies act as "neobanks" or "challenger banks" that partner with chartered banks to provide deposit services. In these arrangements, your money is held at the partner bank, and that is the institution where your insurance coverage resides.
To verify the safety of a prospective account:
- Use the BankFind Tool: Visit the official FDIC BankFind website to search for the bank by name. If it is an FDIC-insured institution, it will appear in the registry.
- Check for NCUA Membership: If you are considering a credit union, use the NCUA Research a Credit Union tool to verify its federally insured status.
- Review the Fine Print: Read the account disclosures on the institution's website. They must clearly state that they are an "FDIC Member" or "NCUA Insured."
- Confirm the Partnership: If you are opening an account through a third-party app or a fintech platform, identify the underlying "custodian" bank. The app itself may not be a bank, but the funds should be held in an omnibus or individual account at an insured bank.
Insurance Limits and Ownership Categories
A common misconception is that the $250,000 insurance limit applies to your entire net worth across all banks. It does not. The limit applies to each "ownership category" at each bank. By strategically organizing your accounts, you can increase the total amount of your assets that remain protected.
Common Ownership Categories:
- Single Accounts: Owned by one person ($250,000 coverage).
- Joint Accounts: Owned by two or more people ($250,000 per co-owner, totaling $500,000 for two owners).
- Retirement Accounts (IRAs): These have separate coverage of up to $250,000.
- Trust Accounts: Coverage can vary based on the number of beneficiaries and the structure of the trust.
If you have savings exceeding $250,000, you are not necessarily unsafe; you simply need to diversify your deposits across multiple, unrelated financial institutions to ensure every dollar remains under the federal insurance cap.
Cybersecurity Considerations
While federal insurance protects you against bank failure, it does not protect you against individual account compromise caused by weak passwords or phishing attacks. Because online HYSAs are accessed exclusively through digital interfaces, your personal cybersecurity practices become the primary defense for your funds.
Modern online banking platforms utilize advanced security measures, including:
- Multi-Factor Authentication (MFA): This requires a second form of verification beyond just a password, such as a biometric scan or a time-sensitive code sent to a mobile device.
- Encryption: Financial institutions use high-level Transport Layer Security (TLS) encryption to protect data in transit between your device and their servers.
- Fraud Monitoring: Sophisticated algorithms monitor for suspicious login locations or unusual transaction patterns, often triggering automated alerts or temporary account freezes to prevent unauthorized access.
Comparison of Traditional vs. Online Savings
Many consumers remain hesitant about online banks due to a lack of familiarity. The following table illustrates how online and traditional models compare regarding safety and operational security.
| Feature | Online HYSA | Traditional Savings Account |
|---|---|---|
| Federal Insurance | FDIC/NCUA Insured | FDIC/NCUA Insured |
| Regulation | Same federal oversight | Same federal oversight |
| Access | Web/Mobile App | Web/Mobile/Branch |
| Operating Cost | Lower (no branch overhead) | Higher (branch infrastructure) |
| Cybersecurity | Advanced digital protocols | Mixed (Digital + Physical) |
Risks Beyond Bank Failure
While your deposit principal is protected, there are other nuances to consider regarding the safety of your money in an online HYSA:
- Variable Interest Rates: The "high yield" component of these accounts is not guaranteed. Because these accounts are typically linked to the federal funds rate, the annual percentage yield (APY) can fluctuate. While your principal is safe, your returns are not fixed.
- Withdrawal Limitations: Some high-yield accounts may have restrictions on the number of transfers per month. While federal Regulation D (which previously capped certain transfers) has been largely relaxed, banks may still implement their own internal policies to limit account activity to maintain liquidity.
- Third-Party Platform Exposure: If you manage your money through a "hub" or "aggregator" app, the risk shifts from the bank to the technology platform. Ensure the app has a strong reputation, clear privacy policies, and that you have direct access to your funds at the underlying bank in case the app experiences a service outage.
Common Mistakes to Avoid
When managing your savings online, certain behaviors can compromise your safety:
- Accessing Accounts on Public Wi-Fi: Always use a secure, private network or a Virtual Private Network (VPN) when checking your bank balance.
- Reusing Passwords: Using the same password for your email or social media as you do for your banking portal provides an easy entry point for hackers. Use a dedicated password manager to generate unique, complex credentials.
- Ignoring Alerts: Enable real-time push notifications or email alerts for all withdrawals or logins. Early detection is the best way to stop unauthorized activity before significant damage occurs.
- Failing to Update Devices: Ensure that the smartphone or computer used to access your bank is running the latest security patches. Vulnerabilities in outdated operating systems can be exploited to capture banking credentials.
Frequently Asked Questions
What happens if the online bank goes out of business? If a bank fails, the FDIC acts as a receiver. Your funds are protected up to the $250,000 limit. In most cases, the FDIC arranges for another bank to acquire the failed institution, allowing you to continue using your account seamlessly. If not, the FDIC will issue a payment for your insured balance.
Are these accounts safe for long-term emergency funds? Yes. Because they are liquid and insured, HYSAs are the industry standard for emergency funds. Unlike stocks or bonds, which fluctuate with market volatility, the balance in an insured savings account does not decrease due to economic downturns.
Is my money safe if I use a fintech app instead of a bank? It depends on how the app handles your money. Look for a "sweep" program disclosure, which explains that your money is moved to a network of FDIC-insured banks. As long as the money is held in a properly structured custodial account at an insured bank, it retains federal protection.
What is the best way to secure my login credentials? Use a long, unique passphrase and enable multi-factor authentication. Avoid using SMS-based 2FA if possible, as it is susceptible to "SIM swapping" attacks. Instead, use an authenticator app or a hardware security key.
Can interest rates on HYSAs drop to zero? Yes. While the principal remains safe, the interest rate is variable and market-dependent. If the Federal Reserve lowers interest rates, your bank will likely lower the APY on your savings account shortly thereafter.
Professional Guidance and Next Actions
If you are looking to maximize the safety of your assets while maintaining liquidity, consider a "laddered" or multi-bank approach. By distributing your savings across two or three reputable, FDIC-insured online banks, you not only protect your funds beyond the $250,000 limit but also create redundancy in case of localized technical issues at one specific institution.
Before committing to an account, verify the institution's official standing on the FDIC BankFind website. Once verified, confirm that your total balance at that specific institution does not exceed the insurance limits. By combining federal protections with diligent digital security practices, you can confidently utilize online high yield savings accounts as a cornerstone of your financial strategy in 2026 and beyond.