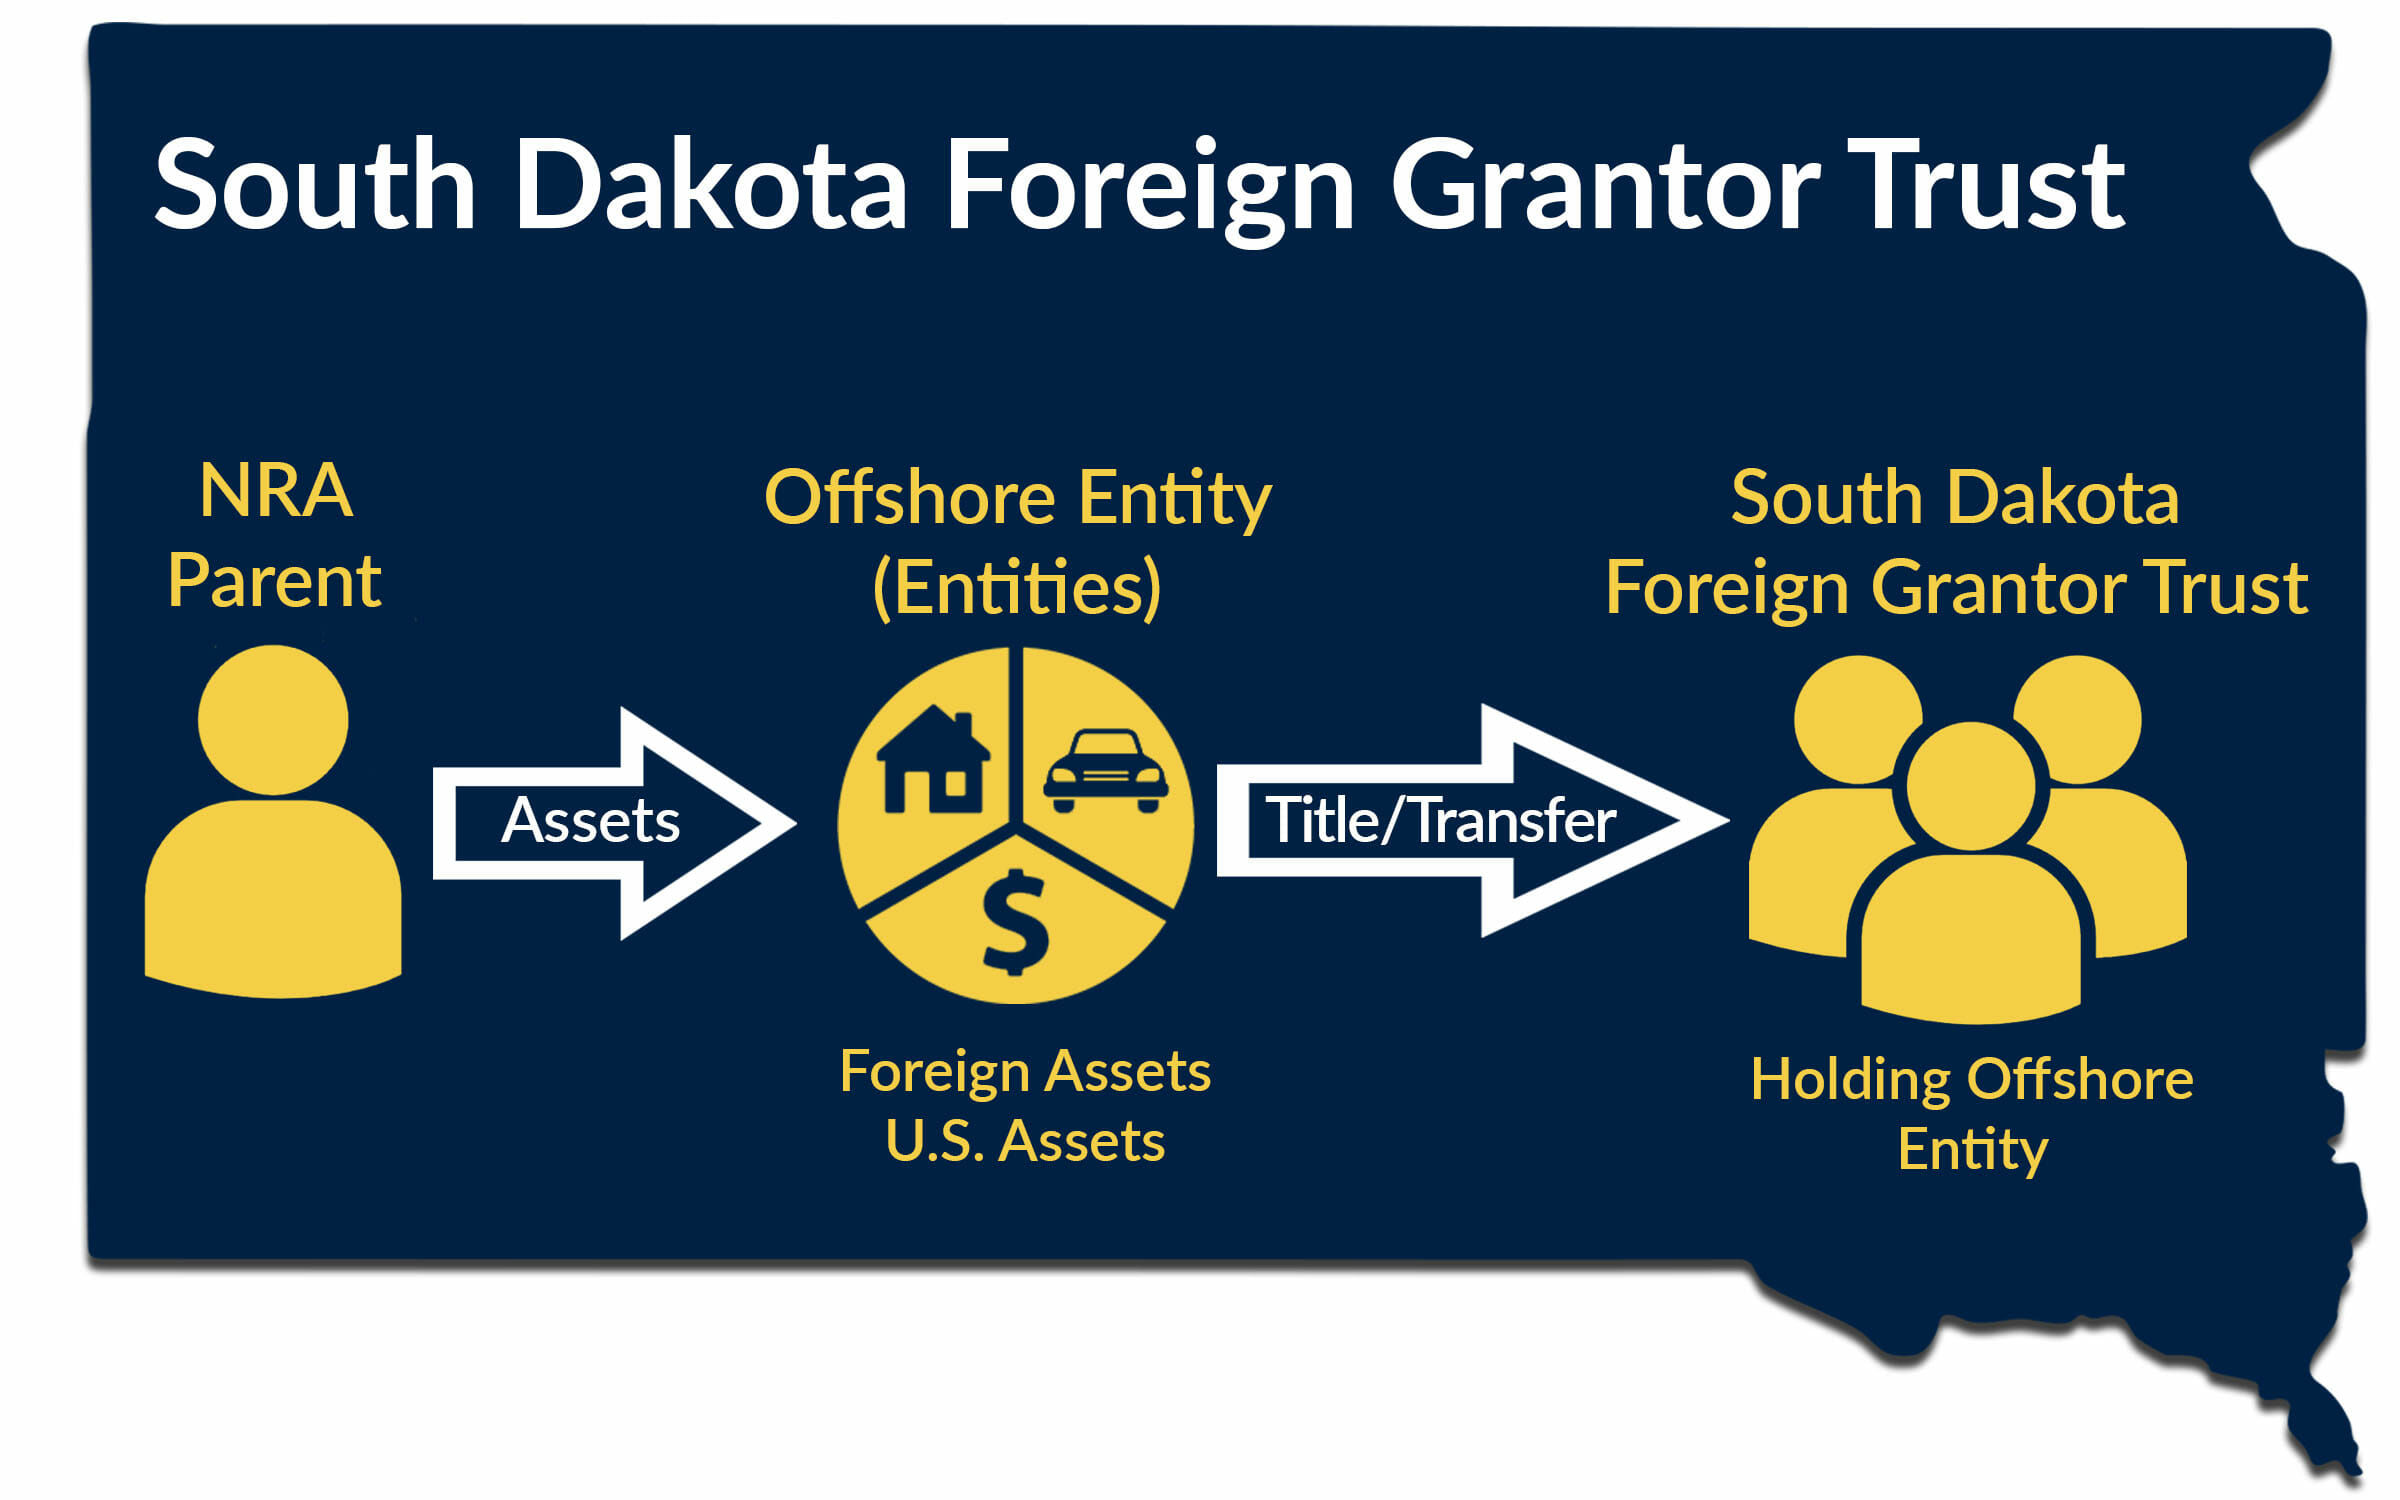
A U.S. trust company is a regulated financial institution authorized to act as a fiduciary, managing assets, estates, and trusts for individuals, families, and corporations. These entities provide specialized legal and financial stewardship, ensuring that complex wealth management and beneficiary obligations are executed in strict accordance with the governing trust instruments or court-ordered mandates.
The Fiduciary Foundation of Trust Companies
At its core, a trust company operates under a fundamental legal obligation known as a fiduciary duty. Unlike standard commercial banking, where the relationship is primarily transactional, the relationship between a client and a trust company is one of profound trust and legal responsibility. When an individual or entity places assets—such as real estate, securities, or cash—into the care of a trust company, that institution assumes the role of trustee.
In this capacity, the trust company is legally bound to act solely in the best interest of the beneficiaries. This is not merely an ethical guideline; it is a rigid legal standard enforced by state and federal regulators. The trust company must manage the assets with a standard of care known as the "prudent person rule," which dictates that the institution must manage, invest, and distribute assets with the same level of care, skill, and caution that a prudent person would exercise in dealing with their own property.
Understanding the Regulatory Landscape
In the United States, trust companies are highly regulated entities. They can be chartered at either the state or federal level. State-chartered trust companies are overseen by state banking departments, while those that operate nationally or have significant interstate operations may fall under the supervision of the Office of the Comptroller of the Currency (OCC).
This regulatory oversight ensures that trust companies maintain adequate capital reserves and adhere to strict reporting requirements. Unlike a standard investment firm, a trust company is subject to frequent audits and exams focused specifically on their fiduciary practices. This oversight is vital for protecting clients, as it ensures that the firm remains solvent and capable of managing long-term, multi-generational wealth transfers.
Key Services Provided by U.S. Trust Companies
Trust companies offer a suite of services designed to handle complex financial planning. While many associate these firms exclusively with the ultra-wealthy, the scope of their work is broad and functional.
Estate Administration and Settlement
When an individual passes away, the process of distributing their assets can be overwhelming for family members. A trust company acts as an executor or successor trustee, taking on the burden of inventorying assets, paying final debts and taxes, and ensuring that distributions are made to beneficiaries according to the terms of the decedent's will or trust document.
Investment Management
Trust companies often provide discretionary investment management services. They maintain a fiduciary standard when selecting assets for a portfolio, meaning they must choose investments that align with the specific goals and risk tolerance defined in the trust agreement. This often involves creating diversified portfolios that balance income generation with capital preservation.
Custodial Services
Many trust companies provide "pure" custody, where they hold and safeguard assets, maintain detailed records, and handle the administrative tasks of settlement and reporting. This is a common service used by smaller family offices, non-profits, and institutional clients who want the security of a regulated trust institution without the need for high-level investment advice.
Specialized Trust Structures
Trust companies are experts in navigating complex tax-advantaged vehicles, such as:
- Grantor Retained Annuity Trusts (GRATs): Used for transferring assets to heirs with minimal gift tax consequences.
- Charitable Remainder Trusts (CRTs): Designed to provide income to the donor for a set period before the remainder goes to a charitable beneficiary.
- Special Needs Trusts (SNTs): Managing assets for beneficiaries with disabilities without disqualifying them from government assistance programs.
Comparing Trust Companies and Traditional Banks
While many major banks own trust company subsidiaries, they are distinct from the bank's retail operations. Understanding the difference is crucial for choosing the right partner for your financial needs.
| Feature | Retail Bank | Trust Company |
|---|---|---|
| Primary Goal | Deposits, lending, payments | Asset protection, administration |
| Legal Status | Creditor/Debtor relationship | Fiduciary relationship |
| Asset Treatment | Assets are on the bank's books | Assets are held in trust (segregated) |
| Complexity | Suitable for everyday transactions | Suitable for complex estate planning |
| Expertise | Customer service and retail loans | Tax, law, and investment management |
In a retail banking environment, your deposits are essentially a liability of the bank; the bank uses your money to fund loans. In a trust company environment, the assets are legally segregated from the firm’s own capital. If a trust company were to face financial distress, the assets held in trust for its clients remain protected and do not become part of the company’s estate for creditors.
Prerequisites for Engaging a Trust Company
Engaging a trust company is typically a deliberate, long-term commitment. Unlike opening a standard brokerage account, the process involves significant documentation and legal review.
- Establishing the Trust Instrument: Before a trust company can act, a legal document (a trust agreement) must be drafted by an attorney. This document defines the rules for the trust, names the beneficiaries, and dictates how the assets should be managed.
- Asset Assessment: Most trust companies require a minimum asset threshold to take on a new client relationship. This can range from $500,000 to several million dollars, depending on the complexity of the account.
- Governance Review: The trust company’s internal compliance and legal teams will review the trust document to ensure that the powers granted to the trustee are clear and that the firm can legally fulfill its duties as written.
- KYC and Anti-Money Laundering (AML): As regulated financial institutions, trust companies must perform rigorous "Know Your Customer" checks to verify the identity of the grantors and beneficiaries.
Common Mistakes to Avoid
The most frequent error individuals make is failing to update their trust documents when personal circumstances change. Marriage, divorce, the birth of children, or a significant change in the value of the trust assets should trigger a review with both an estate attorney and the trust company.
Another common mistake is choosing a corporate trustee solely based on the lowest fee structure. While cost is important, the primary value of a trust company lies in its ability to navigate complex tax laws and administrative duties. A firm that is inexpensive but lacks expertise in specific types of trust assets (such as closely held business interests or specialized real estate) can end up costing the estate more in the long run through mismanagement or tax errors.
Frequently Asked Questions
Is my money insured by the FDIC at a trust company?
No. Trust assets are not "deposits" in the traditional sense and are therefore not covered by FDIC insurance. However, because trust assets are legally segregated from the company's own balance sheet, they are protected from the institution's creditors, providing a different but robust form of security.
How are trust companies compensated?
Trust companies typically charge an annual fee based on a percentage of the assets under management (AUM). This fee is calculated on a tiered schedule, where the percentage decreases as the total value of the assets increases. Some firms may also charge setup fees or flat administrative fees for specialized services.
Can I change my trust company if I am unhappy?
Yes. Most trust documents include a provision that allows the beneficiaries or a "trust protector" to remove and replace a trustee. However, this process often requires a legal review to ensure the transition of asset custody is handled correctly to avoid tax complications.
What is the difference between a directed trust and a delegated trust?
In a directed trust, the trust company is directed by an outside advisor (such as an investment advisor chosen by the grantor) regarding investment decisions. In a delegated or "full-service" trust, the trust company takes on the responsibility for both the administrative and investment decisions.
Why would I use a corporate trust company instead of a family member?
While family members can serve as trustees, they often lack the technical expertise required for complex tax reporting, investment management, and impartial administration. A corporate trustee provides objective, professional management that is unaffected by family dynamics, which can prevent conflicts of interest among beneficiaries.
Recommendations for Action
If you are considering the services of a U.S. trust company, your first step should be to consult with an estate planning attorney who specializes in the jurisdiction where you reside. An attorney can help you determine whether your financial goals require a formal trust structure and, if so, whether your specific needs align with the capabilities of a national institution or a boutique local trust company. Once your legal foundation is set, request a fee schedule and a sample "administration plan" from potential trust companies to compare their administrative approach and cost structure.