Aetna’s life insurance rankings reflect a company with exceptional financial stability but a specialized product focus. Currently, Aetna holds "Superior" financial strength ratings (A or A+) from agencies like A.M. Best, primarily driven by its parent company, CVS Health. While it no longer offers standard individual term or whole life policies, it remains a top-ranked provider for group life insurance and final expense coverage.
Understanding the Modern Aetna Life Insurance Landscape
To accurately explain Aetna’s life insurance rankings, one must first understand the structural shift the company underwent. In 2018, Aetna sold a significant portion of its individual life insurance business to Lincoln Financial Group. This transition is a critical piece of context for any consumer looking at rankings today in 2026. If you hold an older Aetna individual policy, it is likely serviced by Lincoln Financial, meaning Lincoln’s financial rankings are more relevant to your policy’s security than Aetna’s current standings.
In 2026, Aetna’s life insurance presence is concentrated in two primary areas: Group Life Insurance, provided as an employee benefit, and Final Expense Insurance (often marketed as burial insurance), sold through Aetna Senior Products. Rankings for "Aetna Life Insurance" generally aggregate the performance of several subsidiaries, including the Aetna Life Insurance Company and the Continental Life Insurance Company of Brentwood, Tennessee.
Financial Strength Rankings: Can They Pay Your Claim?
Financial strength ratings are the most critical metrics for any insurance provider. They measure the insurer’s "claims-paying ability"—essentially, the likelihood that the company will have the liquid capital necessary to pay out a death benefit decades from now. For Aetna, these rankings remain high due to the massive diversified revenue streams of its parent, CVS Health.
A.M. Best Rankings
A.M. Best is the gold standard for insurance credit ratings. As of 2026, Aetna Life Insurance Company consistently maintains an A (Excellent) or A+ (Superior) rating. This ranking indicates that the agency views Aetna as having an excellent ability to meet its ongoing insurance obligations. For consumers, an "A" category rating is generally considered the threshold for "investment grade" security.
Standard & Poor’s (S&P) and Moody’s
S&P Global Ratings and Moody’s Investors Service provide a broader financial perspective, looking at the company’s debt and market position. Aetna typically holds an A+ from S&P and an A1 from Moody’s. These rankings place Aetna in the "Upper-Medium Grade" of the market. While not the absolute highest possible scores (such as AAA), they signify extremely low credit risk and a stable outlook.
The Comdex Score
The Comdex Score is a composite ranking that averages an insurer’s percentiles across all major rating agencies (A.M. Best, S&P, Moody’s, and Fitch). It is expressed on a scale of 1 to 100. Aetna generally maintains a Comdex Score in the high 80s to low 90s. This ranking is useful because it smooths out any outliers from a single agency and provides a holistic view of the company’s financial health compared to all other life insurers.
Customer Satisfaction and Complaint Rankings
While financial strength tells you if a company can pay, customer satisfaction rankings tell you if they will make the process easy. These rankings are derived from consumer surveys and regulatory data.
J.D. Power Rankings
J.D. Power conducts annual studies on individual and group life insurance satisfaction. In the group life insurance category, Aetna often ranks in the middle of the pack. Because group life insurance is managed through employers, the "customer" is often the HR department rather than the individual employee, which can lead to lower personal satisfaction scores compared to boutique individual life insurers. However, Aetna’s digital portal and claims processing speed are frequently cited as strengths in these surveys.
NAIC Complaint Index
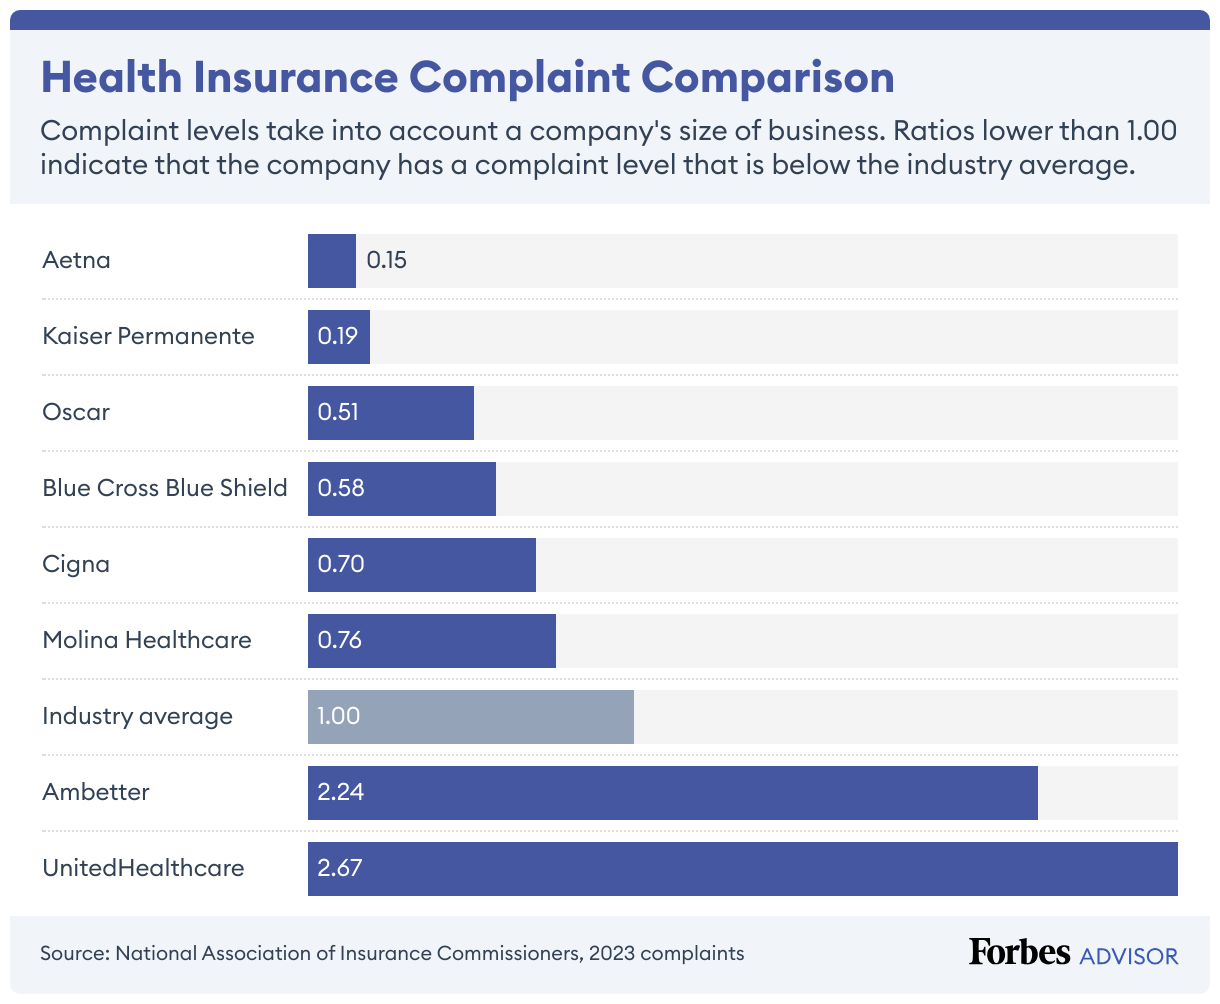
The National Association of Insurance Commissioners (NAIC) tracks the number of complaints filed against insurance companies relative to their market share. The national average is set at 1.00.
- A score below 1.00 means the company receives fewer complaints than expected.
- A score above 1.00 means they receive more.
Aetna’s life insurance subsidiaries, specifically those handling final expense products, typically maintain a complaint index between 0.50 and 0.80. This suggests a high level of consumer satisfaction and effective internal dispute resolution.
Comparative Ranking Overview for 2026
The following table compares Aetna’s core rankings against industry benchmarks to help determine where they stand in the current market.
| Rating Agency | Aetna Ranking (Approx.) | Industry Meaning | Significance for Policyholders |
|---|---|---|---|
| A.M. Best | A+ (Superior) | Highest Tier | Extreme confidence in long-term solvency. |
| S&P Global | A+ (Strong) | Upper-Medium Grade | Strong capacity to meet financial commitments. |
| Moody’s | A1 | Low Credit Risk | High quality and subject to very low credit risk. |
| NAIC Index | 0.65 | Better than Average | Significantly fewer complaints than the industry mean. |
| J.D. Power | 770/1000 | Average | Standard customer service experience for group policies. |
| BBB | A+ | Accredited | High responsiveness to consumer issues and transparency. |
Aetna’s Performance in Group Life Insurance
For many Americans, Aetna is the provider of their employer-sponsored life insurance. In this sector, Aetna is ranked as a Top 5 provider by market share. Their ranking in this niche is driven by their integration with health insurance.
Employers favor Aetna because of the "ecosystem" effect. By linking life insurance with Aetna’s health and disability platforms, claims processing can be streamlined. For example, if an employee goes on long-term disability, the life insurance waiver of premium can often be triggered automatically. This integration gives Aetna a high ranking for administrative efficiency, even if their individual product flexibility is more limited than competitors like Prudential or MetLife.
Final Expense Insurance: A Specialized Top-Tier Ranking
Aetna’s most visible individual life product in 2026 is its Final Expense (Burial) insurance. In this specific niche, Aetna is frequently ranked as a Top-Tier Provider. Unlike their standard life insurance, which was sold off, Aetna built this senior-focused product to complement its massive Medicare Advantage presence.
The ranking for Aetna's Final Expense products is high due to:
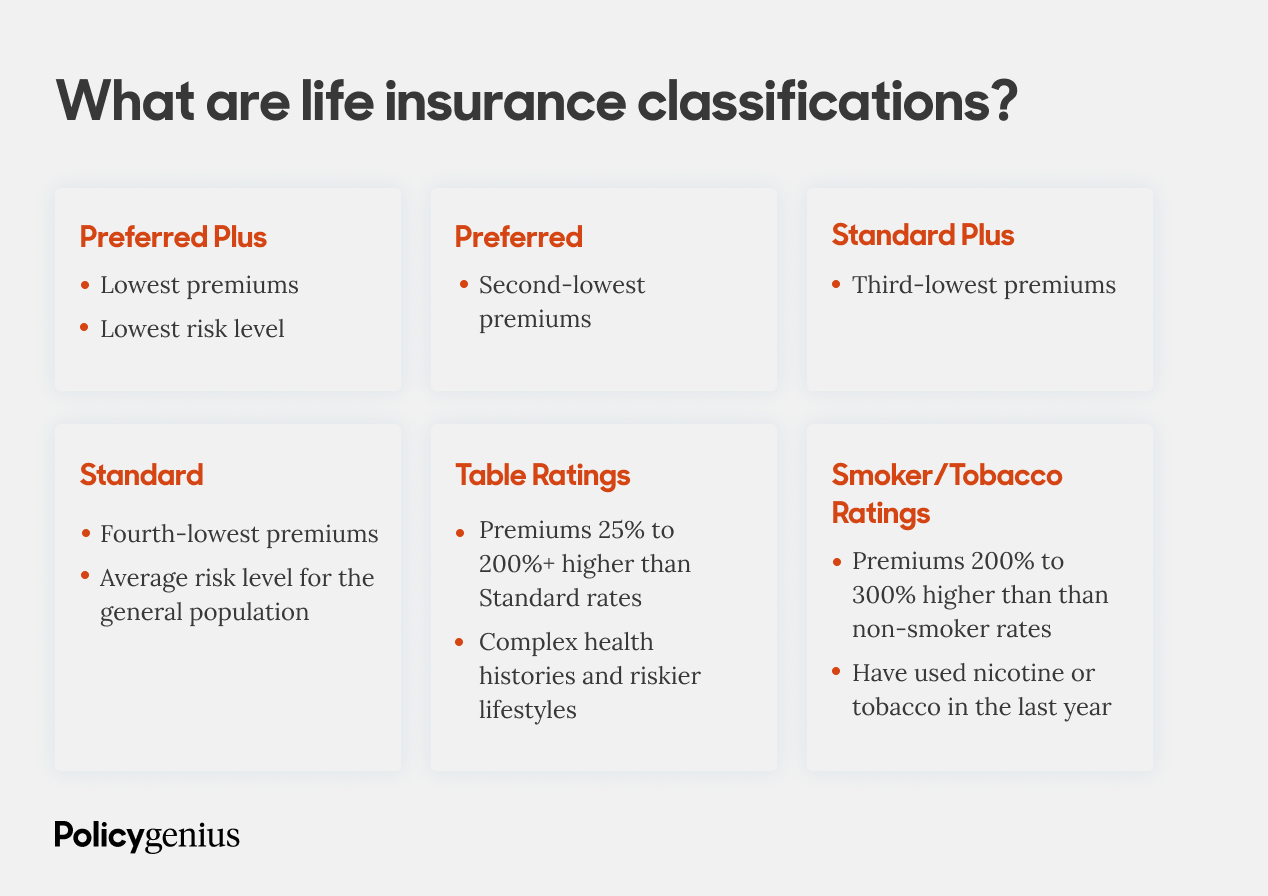
- Underwriting Speed: Their "Accendo" and "Continental Life" subsidiaries use automated underwriting that provides "Super-Preferred" rankings for healthy seniors.
- Price Stability: Aetna is ranked highly for premium consistency, meaning they rarely hike rates on existing policyholders compared to smaller, less capitalized burial insurance companies.
- Ease of Use: Because it targets the 55–89 age demographic, the product is ranked highly for its simplified application process, which requires no medical exams.
Evaluating the Risks: Why Rankings Might Change
While Aetna’s rankings are currently stable in 2026, external factors can influence these scores. As a subsidiary of CVS Health, Aetna’s financial strength is inextricably linked to the parent company’s performance in the retail pharmacy and healthcare services sectors.
Significant debt acquisition by CVS Health or major changes in federal Medicare reimbursement rates can lead rating agencies to adjust their "outlook" from Stable to Negative. For a life insurance policyholder, a change in outlook is an early warning sign that a ranking downgrade could happen in the next 12 to 24 months. However, given CVS Health’s massive cash flow, a drop below "Investment Grade" is considered highly unlikely by market analysts.
How to Verify Current Aetna Rankings
Rankings are not static; they are updated at least annually. To verify the most current status of an Aetna life insurance policy, consumers should follow these steps:
- Identify the Underwriter: Look at the bottom of your policy or marketing material. It may say "Aetna Life Insurance Company," "Continental Life," or "Accendo."
- Check A.M. Best: Visit the A.M. Best website and search for the specific underwriting company name.
- Consult the NAIC Map: Use the NAIC Consumer Insurance Search Tool to view the complaint ratio for the current year.
- Review the CVS Health Annual Report: For a deep dive into the financial backing of Aetna, the "Investor Relations" section of the CVS Health website provides the most granular data on the capital reserves supporting the insurance business.
FAQs About Aetna Life Insurance Rankings
Does Aetna have a good ranking for individual term life insurance?
In 2026, Aetna does not offer new individual term life insurance policies. They sold this business to Lincoln Financial in 2018. If you see rankings for "Aetna Term Life," they likely refer to group policies offered through employers, where Aetna maintains a strong "A" category financial ranking.
How does Aetna’s life insurance ranking compare to MetLife?
Aetna and MetLife both hold high financial strength ratings (typically A or A+). However, MetLife is often ranked higher in the Group Life space due to its larger global footprint, while Aetna is often ranked higher in Final Expense/Senior products due to its integration with CVS/pharmacy and Medicare services.
Is an A+ ranking from A.M. Best the highest possible?
No, the highest A.M. Best ranking is A++ (Superior). Aetna’s A+ ranking is the second-highest possible grade. It still falls within the "Superior" category, indicating that the company has a very strong ability to meet its financial obligations to policyholders.
Why does Aetna have different rankings for different states?
Rankings for financial strength (like A.M. Best) are generally national. However, customer satisfaction and complaint rankings (like the NAIC Index) can vary by state because insurance is regulated at the state level. Aetna might have a 0.40 complaint index in Texas but a 0.90 in Florida, reflecting different regional service qualities or regulatory environments.
Are Aetna’s life insurance rankings affected by their health insurance performance?
Yes. Because Aetna is a unified brand under CVS Health, a major financial loss in the health insurance division (e.g., unexpected spikes in medical loss ratios) could theoretically impact the credit rating of the entire entity, including the life insurance subsidiaries. However, these departments are usually "firewalled" with their own capital reserves to protect life insurance policyholders.
Practical Recommendation: Is Aetna the Right Choice?
If you are looking for Group Life Insurance through your employer or a Final Expense policy to cover funeral costs, Aetna’s rankings suggest they are one of the most secure and reliable choices in the 2026 market. Their "A+" financial strength provides peace of mind that death benefits will be paid, and their low complaint ratios indicate a smooth administrative experience.
However, if you are looking for Individual Term or Permanent Life Insurance for income replacement or estate planning, Aetna is not the correct entity to evaluate. You should instead look at the rankings of companies like Lincoln Financial, Northwestern Mutual, or New York Life, which specialize in those specific individual products. Always verify that the ranking you are viewing corresponds to the specific subsidiary underwriting your policy to ensure total accuracy.