For residents of Bournemouth seeking financial security, the best over 50s life insurance options in 2026 are LV= (Liverpool Victoria) for its local heritage and comprehensive support, SunLife for its market-leading guaranteed acceptance, and Local Independent Financial Advisers (IFAs) who provide tailored, whole-of-market comparisons specifically for the Dorset demographic.
Over 50s life insurance—often referred to as a "no-medical" plan—is a staple for many in Bournemouth’s significant retiree and pre-retiree population. Unlike standard term life insurance, these policies are designed specifically for UK residents aged 50 to 80 (and sometimes up to 85). They guarantee acceptance regardless of health status, making them an essential tool for those who may have developed chronic conditions but still wish to leave a legacy or cover funeral expenses.
In Bournemouth, where the cost of living and the price of local funeral services can trend higher than the national average, selecting the right plan requires a balance between monthly affordability and the ultimate payout value. Whether you are looking for a policy to cover a specific debt or simply want to ensure your family isn't burdened by costs at a difficult time, understanding the nuances of the local and national providers available to you is the first step toward peace of mind.
1. LV= (Liverpool Victoria): The Local Heritage Choice
When discussing insurance in Bournemouth, LV= (Liverpool Victoria) is an institution. With a massive corporate presence at County Gates, on the border of Bournemouth and Poole, LV= is more than just a national provider; it is one of the region’s largest employers and a brand deeply woven into the local community. For a Bournemouth resident, choosing LV= often feels like a "hometown" decision, supported by a long history of mutual values.
Why LV= Stands Out in 2026
In 2026, LV= remains a top contender because of its "Fixed Monthly Premium" model and its reputation for customer service. Their over 50s plan is designed for simplicity. For residents who prefer dealing with a company that has a tangible presence in their town, the brand recognition of LV= provides a level of psychological security that digital-only challengers often lack.
The technical mechanics of an LV= policy involve a "moratorium period." Since there are no medical questions, you are typically not covered for the full sum assured if you die from natural causes within the first 12 to 24 months of the policy (accidental death is usually covered immediately). LV= has been praised for its clarity regarding these terms, ensuring that Bournemouth policyholders understand exactly when their full cover kicks in.
Benefits for Dorset Residents
One of the specific advantages of choosing a provider like LV= is the inclusion of "Member Benefits." Even if you are no longer a "member" in the traditional mutual sense following various corporate restructures, LV= often provides access to health and wellbeing services, such as remote GP appointments and mental health support. In a coastal town like Bournemouth, where access to primary care can sometimes face seasonal pressures due to the influx of tourists and an aging population, these "value-add" digital health services are increasingly relevant.
2. SunLife: The Guaranteed Acceptance Leader
If simplicity and speed are your primary drivers, SunLife is the definitive national option for Bournemouth residents. SunLife pioneered the over 50s plan in the UK and continues to hold the largest market share in 2026. Their "Guaranteed Over 50 Plan" is frequently the benchmark against which all other plans are measured.
The Mechanics of SunLife Coverage
SunLife’s primary appeal is the absolute guarantee of acceptance. If you are a UK resident aged 50 to 85, you cannot be turned down. There are no blood tests, no GP reports, and no invasive questions about your lifestyle. For residents in areas like Westbourne or Southbourne who may have retired early due to health reasons, this "no questions asked" approach is the most accessible route to life insurance.
In 2026, SunLife has refined its offering to include a "Funeral Benefit Option." By linking your policy to a funeral provider (often Dignity or a similar national network with local branches in Bournemouth), you can sometimes increase the value of your payout or receive a discount on funeral costs. Given that the average cost of a funeral in the South West of England has seen steady increases, this integration is a practical way to hedge against inflation.
Practical Considerations
While SunLife is exceptionally easy to set up—often taking less than ten minutes online or over the phone—it is important to monitor the "premium cap." A common critique of over 50s plans is that if you live a very long time (into your 90s), you may eventually pay more in premiums than the policy will pay out. SunLife addresses this by offering "Premium Break" features or capped payment terms in certain policy iterations, which is a vital technical detail for the healthy, active over-50s community in Bournemouth who expect to enjoy many years of coastal living.
3. Local Independent Financial Advisers (IFAs)
While national brands dominate the airwaves, the "third option" for Bournemouth residents is often the most financially savvy: using a Local Independent Financial Adviser. Bournemouth and Poole host a high density of financial services professionals, particularly around the Lansdowne and Christchurch areas.
The Advantage of "Whole-of-Market" Access
An IFA does not sell you their own product. Instead, they use professional software to scan the entire 2026 insurance market—including providers like Legal & General, Aviva, Royal London, and smaller specialist friendly societies. For a resident in Bournemouth, an IFA can provide a personalized comparison that a single-provider website cannot.
The primary benefit here is underwriting optimization. While most over 50s plans are "guaranteed acceptance" (no medicals), some people over 50 are actually healthy enough to pass a simplified medical questionnaire. If you can answer a few basic health questions, an IFA might find you a "Term Life" or "Whole of Life" policy that offers a significantly higher payout for the same monthly premium compared to a standard "Guaranteed Acceptance" plan.
Tailored to the Bournemouth Economy
A local broker understands the Bournemouth property market and the specific needs of its residents. For instance, if you are an over-50 resident with a lingering mortgage on a property in Talbot Woods, a standard £5,000 over 50s plan might be insufficient. A local adviser can help coordinate your life insurance with your inheritance tax planning or your pension structure, providing a holistic service that a call center in another part of the country simply cannot replicate.
Comparative Overview of Options
To help you decide which path fits your specific needs in 2026, the following table compares the key characteristics of these three primary routes.
| Feature | LV= (National/Local) | SunLife (Direct) | Local Bournemouth IFA |
|---|---|---|---|
| Acceptance | Guaranteed (Ages 50-80) | Guaranteed (Ages 50-85) | Varies (Can find Guaranteed or Underwritten) |
| Medical Exam | None required | None required | Depends on chosen policy |
| Best For | Brand loyalty & local trust | Speed and ease of setup | Maximizing payout & expert advice |
| Waiting Period | Typically 12-24 months | Typically 12-24 months | Can be 0 months if underwritten |
| Additional Perks | Health & Wellbeing services | Funeral benefit discounts | Comprehensive financial planning |
| Flexibility | Fixed premiums | Fixed premiums | Highly flexible options |
Understanding the "Bournemouth Factor" in Life Insurance
When searching for the best over 50s life insurance in Bournemouth, it is important to consider regional specifics that influence your decision.
Funeral Costs in the South West
Bournemouth, being a desirable coastal location, often experiences higher-than-average costs for services, including funerals. In 2026, the cost of a cremation or burial in Dorset requires a payout that reflects local prices. When selecting a sum assured (the amount the policy pays out), residents should ensure they are not just looking at national averages. A £3,000 payout might have been sufficient a decade ago, but in the current economic climate, a Bournemouth resident should likely target a higher bracket to ensure full coverage of local professional fees.
The Role of Friendly Societies
The South of England has a strong tradition of "Friendly Societies." These are mutual organizations owned by their members. While LV= is the most famous example in the region, other smaller societies often offer over 50s plans with unique "bonus" structures. An IFA in the Bournemouth area can often point you toward these alternatives, which might offer better long-term value than the heavily advertised national brands.
Technical Specifications and Eligibility
To apply for any of these options in 2026, you must meet certain criteria. While the "over 50s" label is the primary descriptor, the technicalities matter:
- Age Limits: Most policies require you to be at least 50. The upper age limit for new applications is usually 80 for LV= and 85 for SunLife.
- Residency: You must be a legal UK resident. For those who split their time between Bournemouth and homes abroad (e.g., Spain or France), you must ensure your "primary residence" remains in the UK to maintain policy validity.
- Premium Committal: Most over 50s plans require you to pay premiums for life or until a specific anniversary (e.g., your 90th birthday). Stopping payments usually results in the policy lapsing with no cash-in value. It is vital to choose a premium that is sustainable on a retirement income or state pension.
Common Pitfalls to Avoid
When selecting your plan in Bournemouth, be wary of these common mistakes:
- Ignoring the Inflation Gap: A fixed payout of £5,000 will buy less in 2036 than it does in 2026. Look for plans that offer an "increasing cover" option, even if it means slightly higher initial premiums.
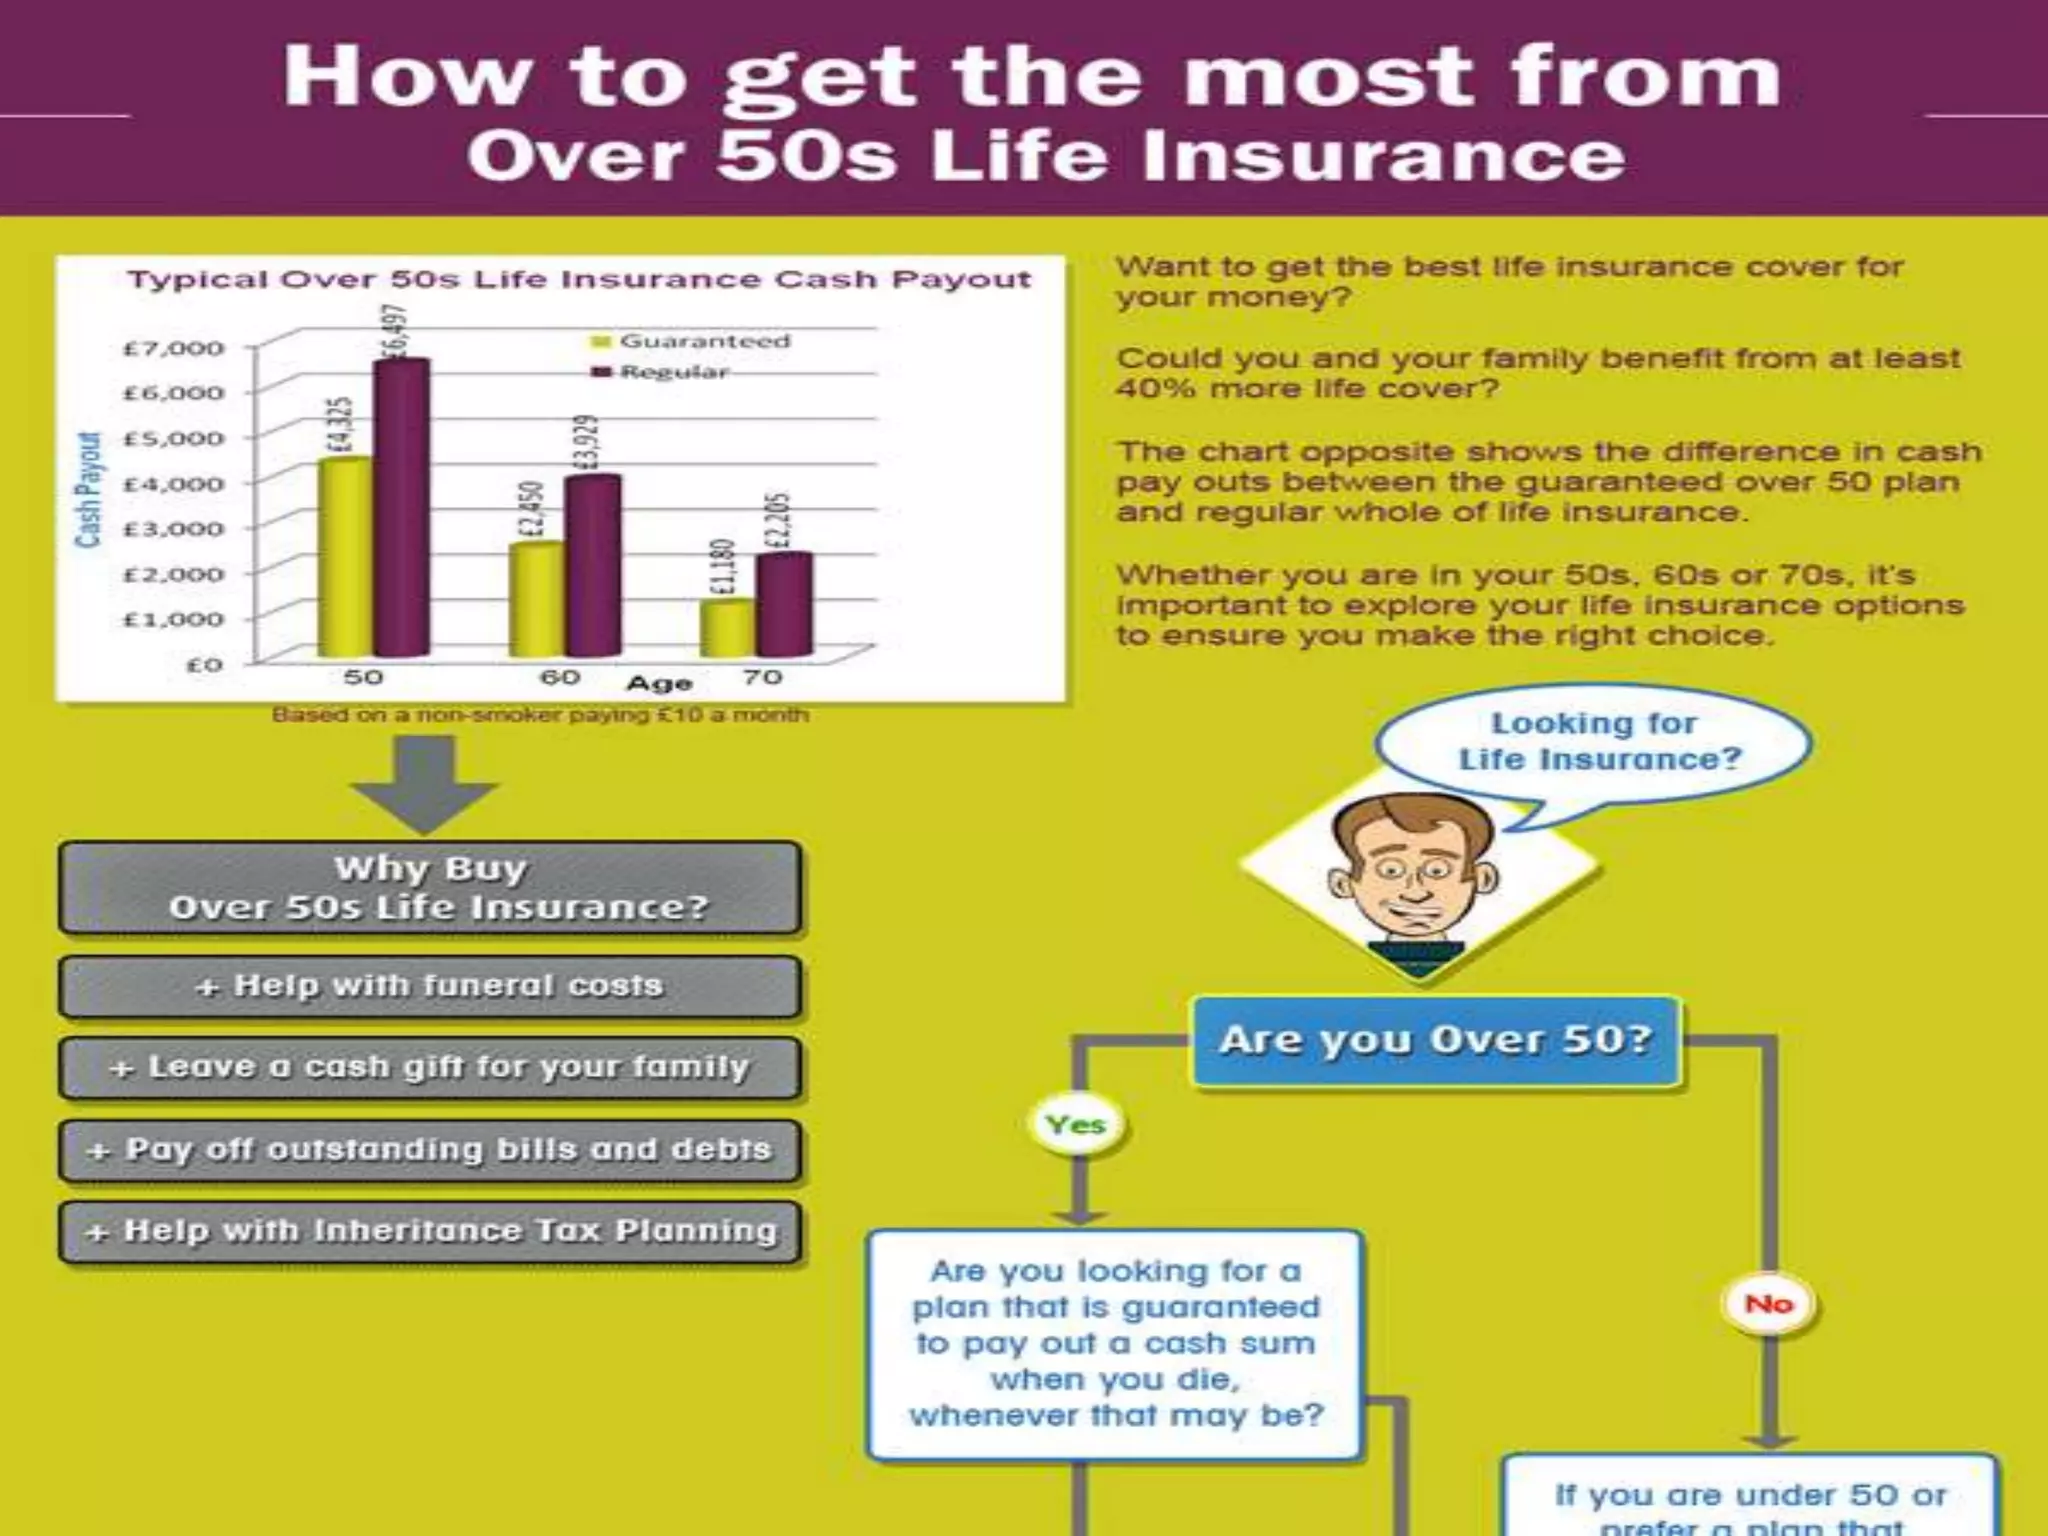
- Overpaying for the Payout: If you start a policy at 50 and live until 95, you may pay in far more than the £4,000 or £5,000 the policy pays out. Always calculate your "break-even" point.
- Assuming All "Over 50s" Plans are the Same: The "waiting period" (moratorium) is the biggest differentiator. Some companies offer a 12-month wait, while others require 24 months before the full sum is payable for natural death. If you have significant health concerns, the shorter the waiting period, the better.
How to Proceed with Your Application
Choosing the best option depends on your personal priority.
- If you value local heritage and added health benefits: Start by requesting a quote from LV=. Their connection to the Bournemouth/Poole area and their robust member support make them a premium choice for residents who value stability.
- If you want the simplest possible process with no questions: SunLife remains the gold standard for accessibility. Their online portal is highly optimized for 2026, allowing you to secure cover in minutes.
- If you want to ensure you are getting the most money for your premium: Contact a Local IFA in Bournemouth. Look for firms with "Chartered" status to ensure the highest level of professional advice. They can compare the likes of Royal London, Aviva, and Legal & General alongside the options mentioned above.
Frequently Asked Questions
Do I need a medical exam for over 50s insurance in Bournemouth?
No, the primary feature of "Over 50s" life insurance is guaranteed acceptance. This means no medical exams, no blood tests, and no access to your GP records is required for the policy to be issued. This is ideal for those with pre-existing conditions that might make traditional life insurance too expensive.
What happens if I die shortly after taking out the policy?
Most policies have a "moratorium period" of 12 to 24 months. If you die of natural causes during this time, the insurer will usually refund the premiums you have paid rather than paying out the full sum assured. However, if death is accidental, most policies (including those from LV= and SunLife) will pay out the full amount immediately from day one.
Can I have more than one over 50s policy?
Yes, you can hold multiple policies with different providers. However, most insurers have a maximum total sum assured you can hold across all their products. For example, you might be limited to a total of £20,000 or £25,000 in cover with a single provider. Holding multiple policies can be a way to increase your total coverage, but you must ensure the combined monthly premiums remain affordable.
Is the payout from these policies taxable?
In the UK, life insurance payouts are generally free from Income Tax and Capital Gains Tax. However, the payout does form part of your estate and may be subject to Inheritance Tax (IHT) if your total estate exceeds the current thresholds. To avoid this, many Bournemouth residents choose to write their policy "in trust," which keeps the payout outside of their estate and allows the money to be paid to beneficiaries more quickly.
Are premiums in Bournemouth higher than elsewhere in the UK?
No, over 50s life insurance premiums are generally national. They are based on your age and the amount of cover you choose, rather than your specific postcode within the UK. A resident in Bournemouth will pay the same as a resident in Manchester for the same product from a national provider like SunLife.
Final Recommendation
For most Bournemouth residents, the "best" option is a balance of trust and value. If you appreciate the presence of a local giant, LV= is an excellent choice. However, before committing to a direct plan, it is highly recommended to speak with a Local Independent Financial Adviser. Given Bournemouth's status as a financial hub, you have access to some of the best advice in the country, which could result in a policy that provides significantly more value for your beneficiaries in the long run.