Obtaining 20-year term life insurance quotes from .org sites in 2026 typically involves utilizing the portals of professional associations, consumer advocacy groups, or non-profit educational foundations. These sites provide a combination of unbiased comparison tools and exclusive member-only group rates that often differ significantly from the commercial quotes found on traditional .com insurance carrier websites.
Understanding the Role of .org Sites in the Insurance Market
In the 2026 financial landscape, the distinction between commercial (.com) and non-profit or association-based (.org) websites remains a critical factor for consumers seeking transparency. A ".org" site in the context of life insurance usually belongs to one of three categories: a professional association (such as those for accountants, engineers, or educators), a consumer advocacy group, or a non-profit educational foundation dedicated to financial literacy.
Unlike commercial brokers who may prioritize carriers based on commission structures, .org sites often operate under a different mandate. Professional associations, for instance, leverage the collective buying power of their entire membership to negotiate "group term" rates. These rates are specifically designed for the demographic profile of that profession, which can lead to lower premiums for 20-year terms if the profession is statistically lower-risk.
Furthermore, educational .org sites, such as the Life and Health Insurance Foundation for Education, provide neutral calculators. These tools allow you to input your 2026 financial data—including current debt, projected college tuition for dependents, and funeral costs—to receive an objective coverage recommendation before you ever see a specific price quote. This "education-first" approach helps prevent over-insuring or under-insuring.
Why a 20-Year Term is the Preferred Choice in 2026
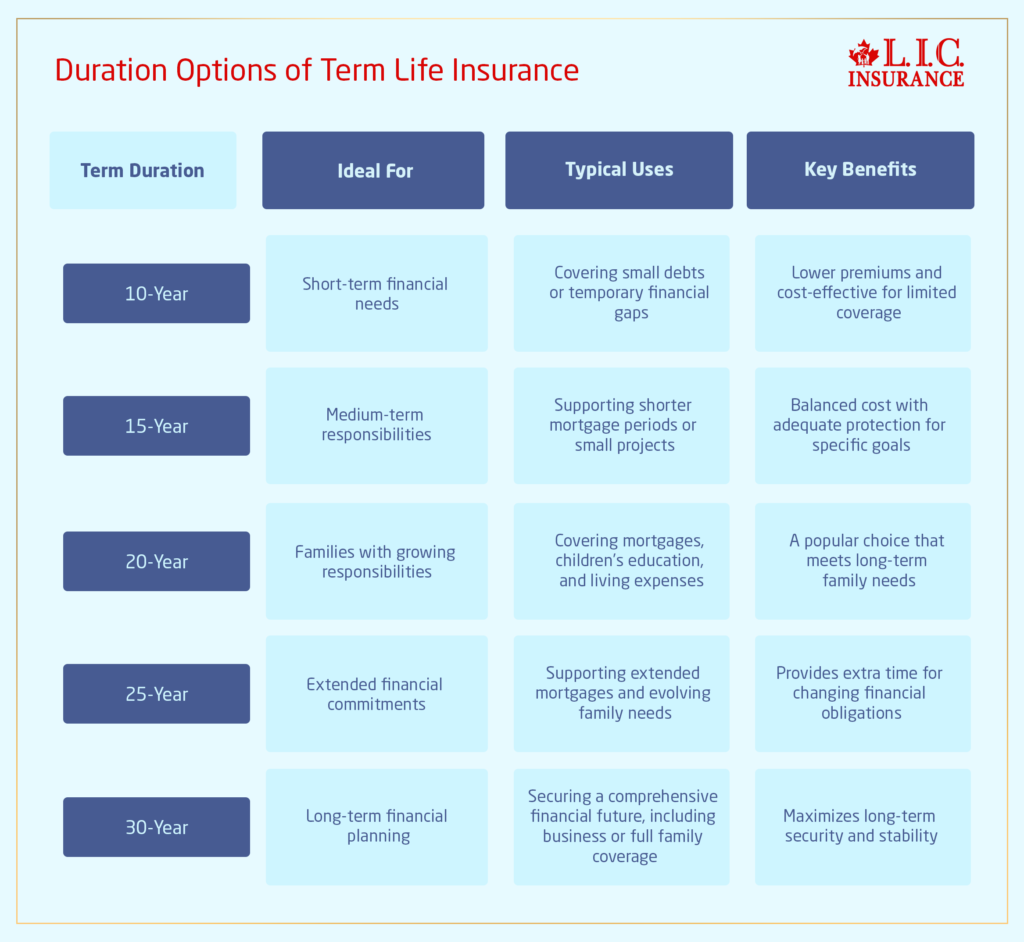
The 20-year term life insurance policy has solidified its position as the "Goldilocks" of life insurance durations. As we navigate the economic environment of 2026, this specific timeframe aligns perfectly with the most common financial obligations of modern households.
Matching the Mortgage Cycle
While 30-year mortgages remain standard, many homeowners in 2026 have transitioned to 15-year or 20-year fixed-rate products, or they are 10 years into a 30-year loan. A 20-year term provides a safety net that covers the remaining duration of the home loan, ensuring that a surviving spouse or family member is not forced to sell the property due to a loss of income.
Protecting the "Launching Years" for Children
For parents of young children or teenagers, a 20-year term covers the critical window of dependency. It protects the family through the remainder of K-12 education and the increasingly expensive university years. By 2026, the cost of higher education has continued to rise, making the "death benefit" of a 20-year policy a vital component of a family’s educational funding strategy.
Cost-Efficiency vs. 30-Year Terms
From a pricing perspective, 20-year terms are significantly more affordable than 30-year terms. In 2026, insurance carriers use highly refined mortality tables that reflect improved medical technology. However, the risk of a claim increases exponentially between years 20 and 30 of a policy. By opting for a 20-year term via a .org association site, healthy individuals can often secure substantial coverage at a fraction of the cost of a permanent or 30-year policy.
Sources for .org Life Insurance Quotes
When searching for "20 year term life insurance quotes from a org site," you should focus your efforts on specific types of organizations that offer verified insurance programs.
Professional and Trade Associations
Many professionals have access to exclusive insurance pools. For example:
- AICPA.org: The American Institute of CPAs offers various life insurance plans specifically for accountants.
- IEEE.org: The Institute of Electrical and Electronics Engineers provides group term life options for technical professionals.
- ABA.org: The American Bar Association provides similar benefits for legal professionals.
These organizations partner with major carriers (like Prudential or MetLife) but offer "association-exclusive" pricing that is not available to the general public.
Credit Union-Linked Organizations
Many credit unions operate through .org domains and provide access to the TruStage insurance program or similar non-profit-aligned insurers. These quotes are often simplified, meaning they require fewer medical hurdles, though the premiums may be slightly higher than a fully underwritten individual policy.
Consumer Advocacy Groups
Sites like ConsumerReports.org (while requiring a subscription) provide deep-dive analytics into which insurers have the best claims-paying reputations in 2026. They often link to neutral quote engines that aggregate data from multiple .org-affiliated providers.
The Quote Process: What to Expect in 2026
The process of getting a quote from a .org site has evolved with the integration of "Accelerated Underwriting." In 2026, the gap between clicking "get a quote" and receiving a firm offer has narrowed to minutes for many applicants.
- Membership Verification: If you are using a professional association site, you will first need to provide your membership ID. The quote is often contingent on you maintaining your "active" status within the organization.
- Data Input: You will provide basic demographic information. By 2026, many .org portals use secure API connections to verify certain health markers or lifestyle data (with your permission), reducing the number of manual questions you have to answer.
- The Preliminary Quote: The site will generate a "soft" quote based on "Standard," "Preferred," or "Super Preferred" health tiers.
- The "Group" Advantage: On a .org site, you might notice that the quote is "age-banded." This means the price may stay the same for five-year increments, or it may be a level-premium 20-year term where the price is locked in for the entire two decades. It is vital to clarify which version you are viewing.
Comparing .org Entities for 20-Year Term Quotes
The following table outlines the differences in what you might find when seeking quotes across different types of .org platforms in 2026.
| Organization Type | Primary Goal | Quote Type | Potential Advantage |
|---|---|---|---|
| Professional Association | Member Benefit | Group Term / Level Term | Negotiated rates based on low-risk professional cohorts. |
| Consumer Advocacy | Unbiased Comparison | Aggregated Individual Quotes | High transparency and side-by-side "A+" rated carrier reviews. |
| Credit Union (.org) | Financial Stability | Simplified Issue Term | Easier qualification for those with minor health issues. |
| Alumni Association | Affinity Benefit | Group Term | Competitive rates for university graduates; often "portable" coverage. |
Factors That Influence Your 2026 Quote
Even when using a trusted .org site, several variables will dictate the final price of your 20-year term policy.
Health and Bio-Data
In 2026, "fluidless" underwriting is the norm. Instead of a paramedical exam (blood and urine samples), many .org-affiliated insurers analyze your prescription history, motor vehicle records, and even wearable fitness data if you choose to opt-in. A history of smoking or chronic conditions like Type 2 diabetes will still impact the quote, though 2026 medical advancements have made "sub-standard" ratings more affordable than in previous decades.
Policy Riders
When requesting a quote, you will often be asked about "riders"—extra features you can add to the 20-year term. Common riders in 2026 include:
- Accelerated Death Benefit: Allows you to access funds if diagnosed with a terminal illness.
- Waiver of Premium: Pays your premiums if you become totally disabled.
- Child Term Rider: Adds a small amount of coverage for your children under your 20-year umbrella.
Conversion Options
A critical feature to look for in a .org quote is the "conversion privilege." This allows you to convert your 20-year term into a permanent policy (like Whole Life) before the term expires, without a new medical exam. In 2026, this is a highly valued feature as it protects your "insurability" as you age.
Group vs. Individual Quotes on .org Sites
It is a common misconception that a quote from a .org site is always cheaper than a .com site.
Group Term (Association Sites): These quotes are often "blended." The insurer looks at the average health of the whole group. If you are exceptionally healthy, you might actually find a cheaper individual policy on a commercial site because you are being "subsidized" by the less-healthy members of the association. However, if you have minor health issues, the group rate is often a significant bargain because the underwriting is less stringent.
Level Term (Individual via .org): Some .org sites simply act as a vetted gateway to individual policies. These quotes will be "level," meaning the price is guaranteed to stay the same for the full 20 years. This provides the most long-term financial certainty for 2026 budget planning.
Common Pitfalls to Avoid
When navigating .org sites for insurance quotes, be mindful of the following:
- Membership Fees: If you are joining an association specifically to get a 20-year term quote, calculate the annual membership dues into the "true cost" of the insurance.
- Portability Issues: If the quote is for a "group" policy through your employer's .org-affiliated union or professional body, ask if the coverage is "portable." If you leave that profession or association, you might lose the coverage or see a massive price spike.
- Limited Customization: .org sites often offer standardized coverage amounts (e.g., increments of $100,000). If you need a very specific amount of coverage, an individual policy via a commercial broker might offer more flexibility.
Frequently Asked Questions
Are quotes from .org sites more accurate than .com sites?
Quotes from .org sites are generally more transparent because the organizations often have a fiduciary or member-advocacy interest. While the "accuracy" depends on the data you provide, .org sites are less likely to use "teaser rates" that apply to only 1% of the population.
Do I have to be a member of the organization to get a quote?
Usually, you can see a "preliminary" quote or a rate table without being a member. However, to receive a formal, binding 20-year term quote and begin the application, you will typically need to provide an active membership number.
What happens to my 20-year term if the .org association changes carriers?
If a professional association switches its insurance partner (e.g., from Carrier A to Carrier B), your coverage is usually "grandfathered" in or transitioned seamlessly. The master policy held by the .org entity protects the members from losing coverage due to corporate contract changes.
Can I get a 20-year term quote on a .org site without a medical exam?
Yes. By 2026, most association-based .org sites offer "Simplified Issue" or "Accelerated Underwriting" for 20-year terms up to certain limits (often up to $1 million or $2 million). If you fall within the healthy height/weight and age brackets, a medical exam is frequently waived.
Is the death benefit taxable in 2026?
Under current 2026 tax laws in the United States, the death benefit from a 20-year term life insurance policy is generally received by the beneficiaries income-tax-free. This remains one of the primary reasons for securing coverage through a trusted .org entity.
Final Recommendation for 2026
To find the best 20-year term life insurance quotes from a .org site, start by listing every professional, academic, or social association you belong to. Visit their respective ".org" member benefit pages first. Compare these association "group" rates against the neutral calculators found on non-profit financial literacy sites. If you are in excellent health, always cross-reference the association quote with at least one highly-rated individual term policy to ensure the "group" rate is actually the most cost-effective option for your specific profile.