Assurity Life Insurance bad reviews typically focus on three primary areas: lengthy claims processing times for disability products, rigorous underwriting requirements that surprise applicants, and occasional technical difficulties with the policyholder portal. While these complaints are significant, they are often offset by Assurity’s "A-" (Excellent) AM Best financial strength rating and its unique status as a certified B Corp.
As we move through 2026, the landscape of the insurance industry continues to shift toward digital-first interactions. For many consumers, the first instinct when researching a provider like Assurity is to search for "bad reviews" to identify potential pitfalls. However, understanding the context behind negative feedback is essential for determining whether a company’s weaknesses are systemic or merely symptomatic of the broader insurance industry. Assurity Life Insurance Company, a mutual organization based in Lincoln, Nebraska, occupies a specific niche in the market, focusing heavily on disability income, critical illness, and individual life insurance. Because their product mix is more complex than a standard term-life provider, the friction points for customers are often more nuanced.
The Scope and Identity of Assurity Life Insurance
Before dissecting negative feedback, it is important to understand the entity in question. Assurity is a mutual insurance company, meaning it is owned by its policyholders rather than outside shareholders. This structure theoretically aligns the company's interests with its customers. Furthermore, Assurity holds a Certified B Corporation status. This designation requires the company to meet high standards of verified social and environmental performance, public transparency, and legal accountability to balance profit and purpose.
Despite these altruistic credentials, Assurity is not immune to criticism. Most "bad reviews" are found on platforms like the Better Business Bureau (BBB), Trustpilot, and the National Association of Insurance Commissioners (NAIC) consumer complaint index. To analyze these reviews effectively, we must categorize them by the specific stages of the insurance lifecycle: application/underwriting, policy maintenance, and claims.
Analyzing the Most Common Complaints
When consumers leave negative feedback for Assurity, the grievances usually fall into one of the following categories. Understanding the technical "why" behind these issues can help prospective buyers navigate the process more effectively.
1. Underwriting Delays and Rigidity
Many negative reviews stem from the initial application phase. Applicants often complain that the process took significantly longer than the "instant" or "accelerated" timelines promised in marketing materials.
Why this happens: Assurity utilizes "Simplified Underwriting" for many of its products, which aims to bypass medical exams. However, if an applicant has a complex medical history, the system automatically pivots to traditional underwriting. This requires the collection of Attending Physician Statements (APS), which can take weeks or even months depending on the doctor's office responsiveness. Users who expected a 48-hour approval often feel misled when the process stretches to 45 days.
2. Disability Claim Denials and Documentation
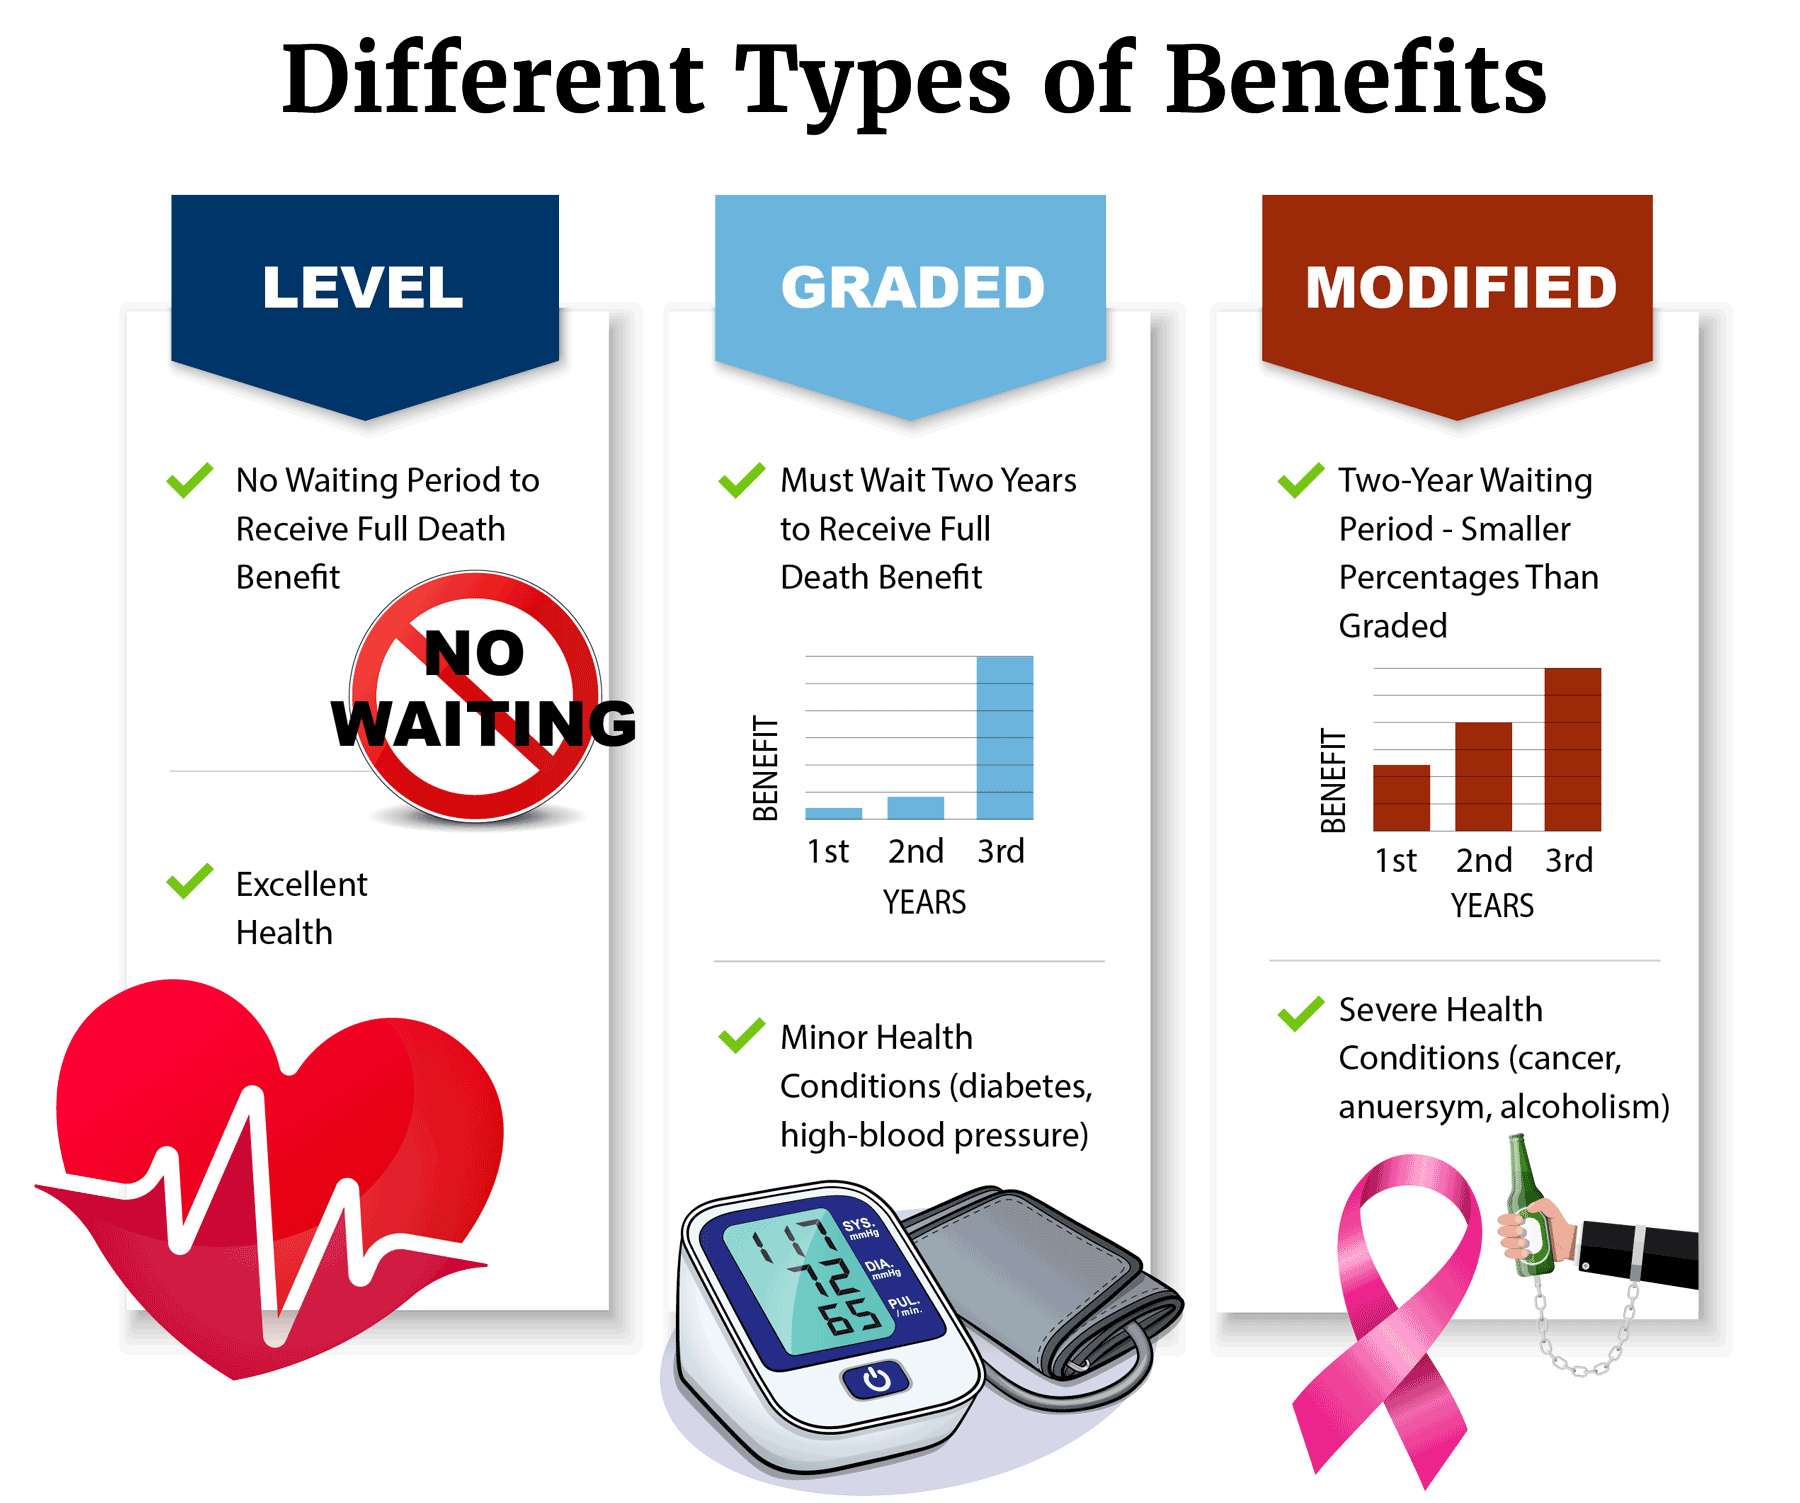
Assurity is a major player in the Disability Income (DI) market. DI insurance is notoriously more complex than life insurance because "disability" is a subjective state compared to the binary nature of a life insurance claim.
Why this happens: Bad reviews in this category often involve the definition of disability. If a policy is "Own-Occupation" versus "Any-Occupation," the criteria for a payout differ wildly. Many disgruntled reviewers cite that Assurity requested excessive documentation—such as repeated functional capacity evaluations or updated tax returns—before releasing monthly benefits. This "administrative friction" is a common pain point for those already facing the stress of a loss of income.
3. Customer Service and Digital Portal Friction
In 2026, policyholders expect seamless mobile integration. Some Assurity reviews point toward a "clunky" user interface in the policyholder portal, making it difficult to update payment methods or view beneficiary designations.
Why this happens: Like many legacy mutual insurers founded in the late 19th century (Assurity's roots go back to 1890), the back-end systems are often a patchwork of older mainframe technology and newer web-based front-ends. This can lead to synchronization issues where a change made online doesn't reflect in the system for several business days, prompting frustrated calls to customer service.
Contextualizing Reviews with the NAIC Complaint Index
To move beyond anecdotal "bad reviews," we must look at the NAIC Complaint Index. This index compares a company's performance against the industry average. A score of 1.00 represents the national average. A score below 1.00 means the company has fewer complaints than expected for its size, while a score above 1.00 indicates a higher volume of dissatisfaction.
| Year | Product Type | Complaint Index | Trend/Status |
|---|---|---|---|
| 2023 | Individual Life | 0.45 | Significantly Better than Average |
| 2024 | Accident & Health | 1.12 | Slightly Worse than Average |
| 2025 | Individual Life | 0.52 | Better than Average |
| 2026 (Est) | Total Market | 0.78 | Favorable Overall |
As the table illustrates, Assurity generally performs very well in the Life Insurance segment, often hovering around half the national average for complaints. However, their Accident and Health segment (which includes Disability and Critical Illness) occasionally spikes above the average. This confirms that the majority of "bad reviews" are likely tied to the complexities of health-related claims rather than life insurance payouts.
Financial Strength: The Counter-Argument to Negative Reviews
A company can have poor Yelp reviews but still be a fortress of financial stability. For an insurance company, financial strength is the most critical metric because it dictates the company's ability to pay a claim twenty or thirty years from now.
Assurity currently maintains an A- (Excellent) rating from AM Best. While this is not the highest possible rating (which would be A++), it signifies a "stable" outlook and a strong ability to meet ongoing insurance obligations. In the context of "bad reviews," it is important to distinguish between "they are slow to answer the phone" (customer service issue) and "they cannot afford to pay my claim" (solvency issue). There is no evidence in 2026 to suggest that Assurity faces solvency issues.
Product Suitability and Limitations
Part of the reason for negative feedback is a mismatch between the product and the consumer’s needs. Assurity focuses on the middle market, often providing coverage to individuals who might be declined by "blue chip" carriers like Northwestern Mutual.
Term Life Insurance
Assurity's term products are straightforward, but they often include "Living Benefits" (Accelerated Death Benefits). A common source of confusion—and subsequent bad reviews—occurs when a policyholder tries to access these benefits for a chronic illness, only to find that the medical criteria are stricter than they anticipated.
Disability Income (DI)
Assurity is one of the few carriers offering DI to middle-income workers and those in higher-risk occupations (e.g., construction, delivery). Because they take on higher risk, their underwriting can be more intrusive, and their claims department may be more vigilant about verifying ongoing disability.
Critical Illness
These policies pay a lump sum upon diagnosis of a covered condition (like cancer or heart attack). Negative reviews here often stem from "exclusion periods" or very specific medical definitions (e.g., a "mini-stroke" vs. a "full stroke") that do not trigger a payout.
Comparing Assurity to Competitors in 2026
When deciding if Assurity's "bad reviews" are a dealbreaker, it helps to compare them to other mutual and B Corp-adjacent insurers.
| Feature | Assurity | Mutual of Omaha | Northwestern Mutual |
|---|---|---|---|
| Primary Strength | Middle-market DI & B Corp Status | Brand Recognition & Term Life | High Net Worth & Dividends |
| AM Best Rating | A- (Excellent) | A+ (Superior) | A++ (Superior) |
| NAIC Index (Life) | Very Low (Good) | Average | Very Low (Good) |
| Application Speed | Moderate (Tech-heavy) | Moderate | Slow (Agent-heavy) |
| Typical Complaint | Claim Documentation | Phone Wait Times | Aggressive Sales Tactics |
Assurity typically wins on flexibility for the average worker, but they may lack the "white-glove" service found at premium-tier carriers like Northwestern Mutual.
How to Avoid the "Bad Review" Experience with Assurity
Most negative experiences with Assurity can be mitigated by following a proactive approach during the application and claims process:
- Be Transparent in Underwriting: Many claims are denied or delayed because of "material misrepresentation" (forgetting to mention a medication or a past surgery). If you are 100% honest during the application, the contestability period is much easier to navigate.
- Understand the "Elimination Period": In disability insurance, the elimination period is the "waiting period" before benefits start. Many bad reviews come from people who didn't realize they had to wait 90 days after becoming disabled before receiving their first check.
- Work with an Independent Agent: Because Assurity's products are specialized, having an agent who can advocate for you during the underwriting process is invaluable. They can often push back on unnecessary medical requests or clarify communication gaps.
- Use the "Free Look" Period: In most states, you have 10 to 30 days to review your policy after delivery. Read the definitions of "Disability" or "Critical Illness" carefully. If the language is too restrictive for your comfort, you can cancel for a full refund.
Frequently Asked Questions
Is Assurity Life Insurance a legitimate company?
Yes, Assurity is a highly legitimate, established mutual insurance company founded in 1890. It is licensed to operate in nearly all U.S. states and is a Certified B Corporation, meaning it meets rigorous standards for social and environmental performance and transparency.
Why does Assurity have an A- rating instead of an A+?
The A- (Excellent) rating from AM Best indicates a very strong financial position. However, it is slightly lower than some "mega-insurers" due to Assurity's smaller size and its concentration in the middle-market disability and health niches, which carry different risk profiles than pure life insurance.
Does Assurity actually pay out claims?
Yes. In the most recent reporting periods leading into 2026, Assurity has paid out hundreds of millions of dollars in claims. Most complaints about "non-payment" are actually disputes over whether the specific medical condition meets the policy's legal definitions, rather than an inability or refusal to pay.
How long does it take for Assurity to process a death claim?
For a standard life insurance claim with all documentation (death certificate and claim form) submitted correctly, Assurity typically processes payments within 7 to 10 business days. Delays usually only occur if the policy is still within the two-year "contestability period."
Can I get Assurity insurance without a medical exam?
Assurity offers "Accelerated Underwriting," which allows many healthy applicants to qualify for coverage without a physical exam. However, this is not guaranteed; the company reserves the right to request a medical exam if your health history, prescription database check, or motor vehicle record shows red flags.
Final Recommendation: Is Assurity Right for You?
Despite the presence of bad reviews, Assurity Life Insurance remains a strong contender for individuals who value a company with a social mission (B Corp) and those who need specialized products like individual disability insurance. The negative feedback regarding claims documentation is a common industry-wide issue in the disability sector and is not unique to Assurity.
If you are looking for simple term life insurance and have a clean medical history, you may find faster digital experiences elsewhere. However, if you are a self-employed professional or a middle-market worker seeking a comprehensive safety net that includes disability and critical illness coverage, Assurity's offerings are robust. To ensure a positive experience, prioritize total honesty during underwriting and ensure you fully comprehend the "Elimination Period" and "Definition of Disability" before signing your policy.