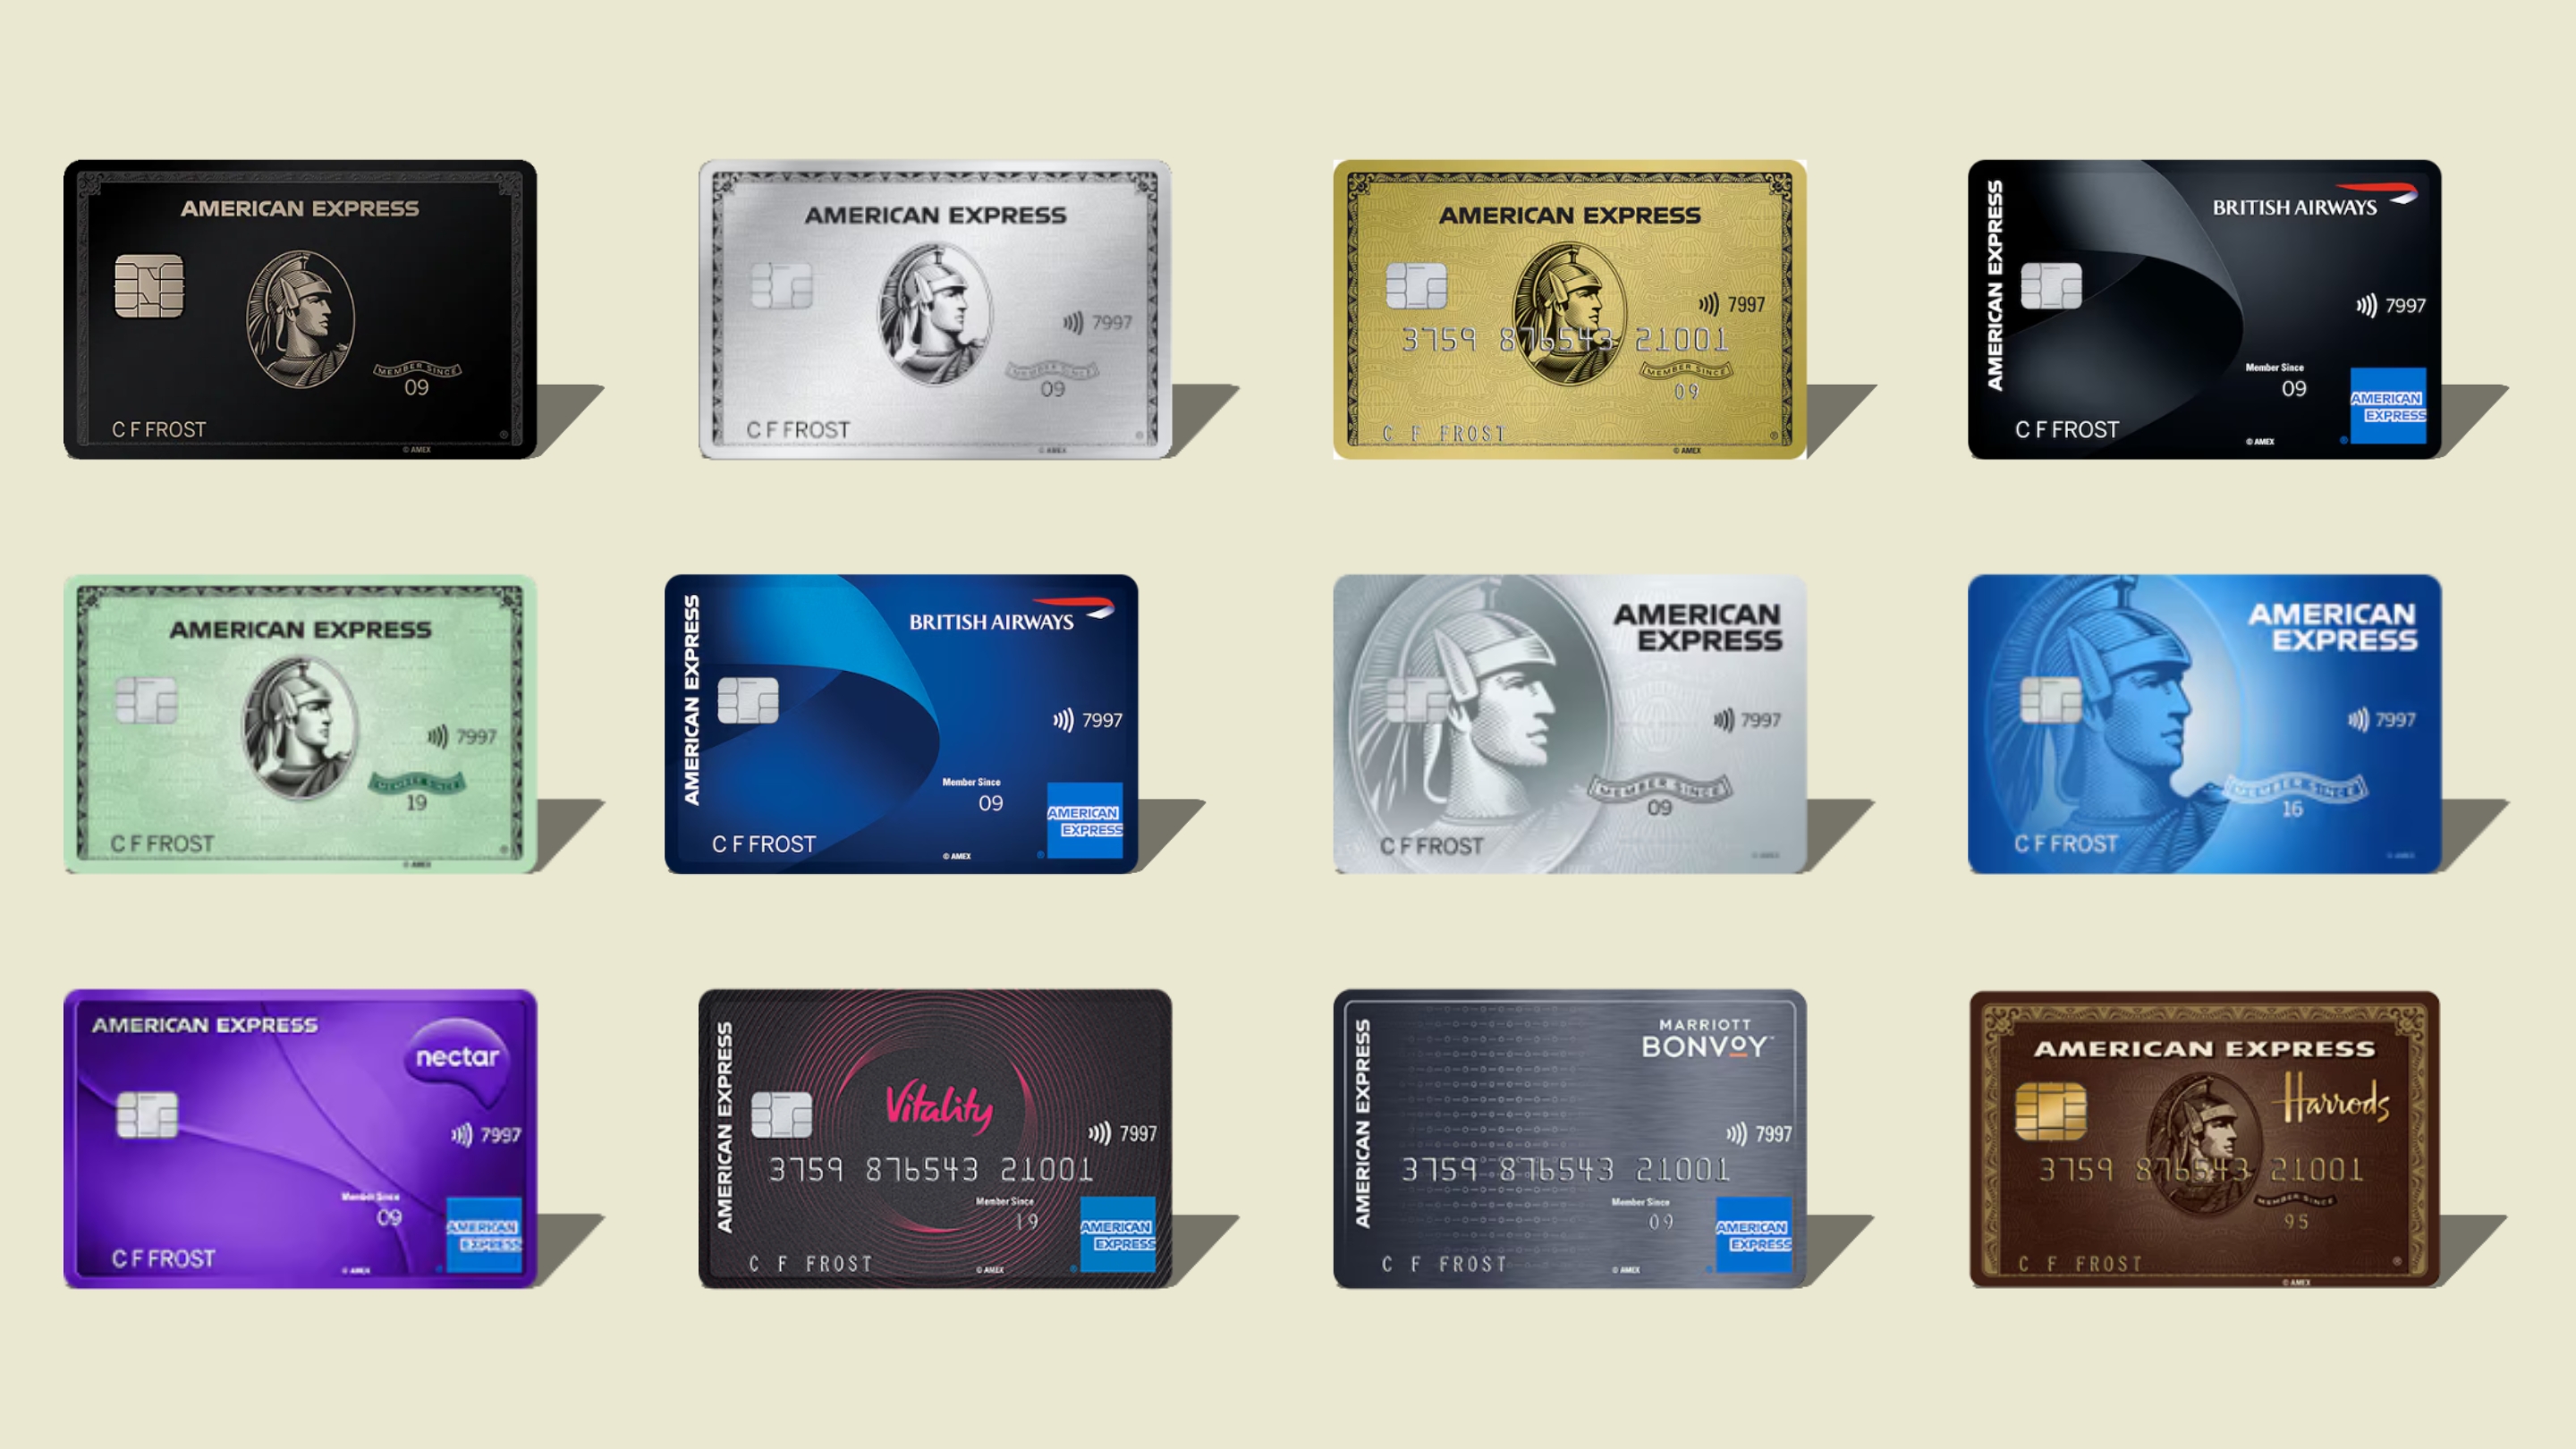
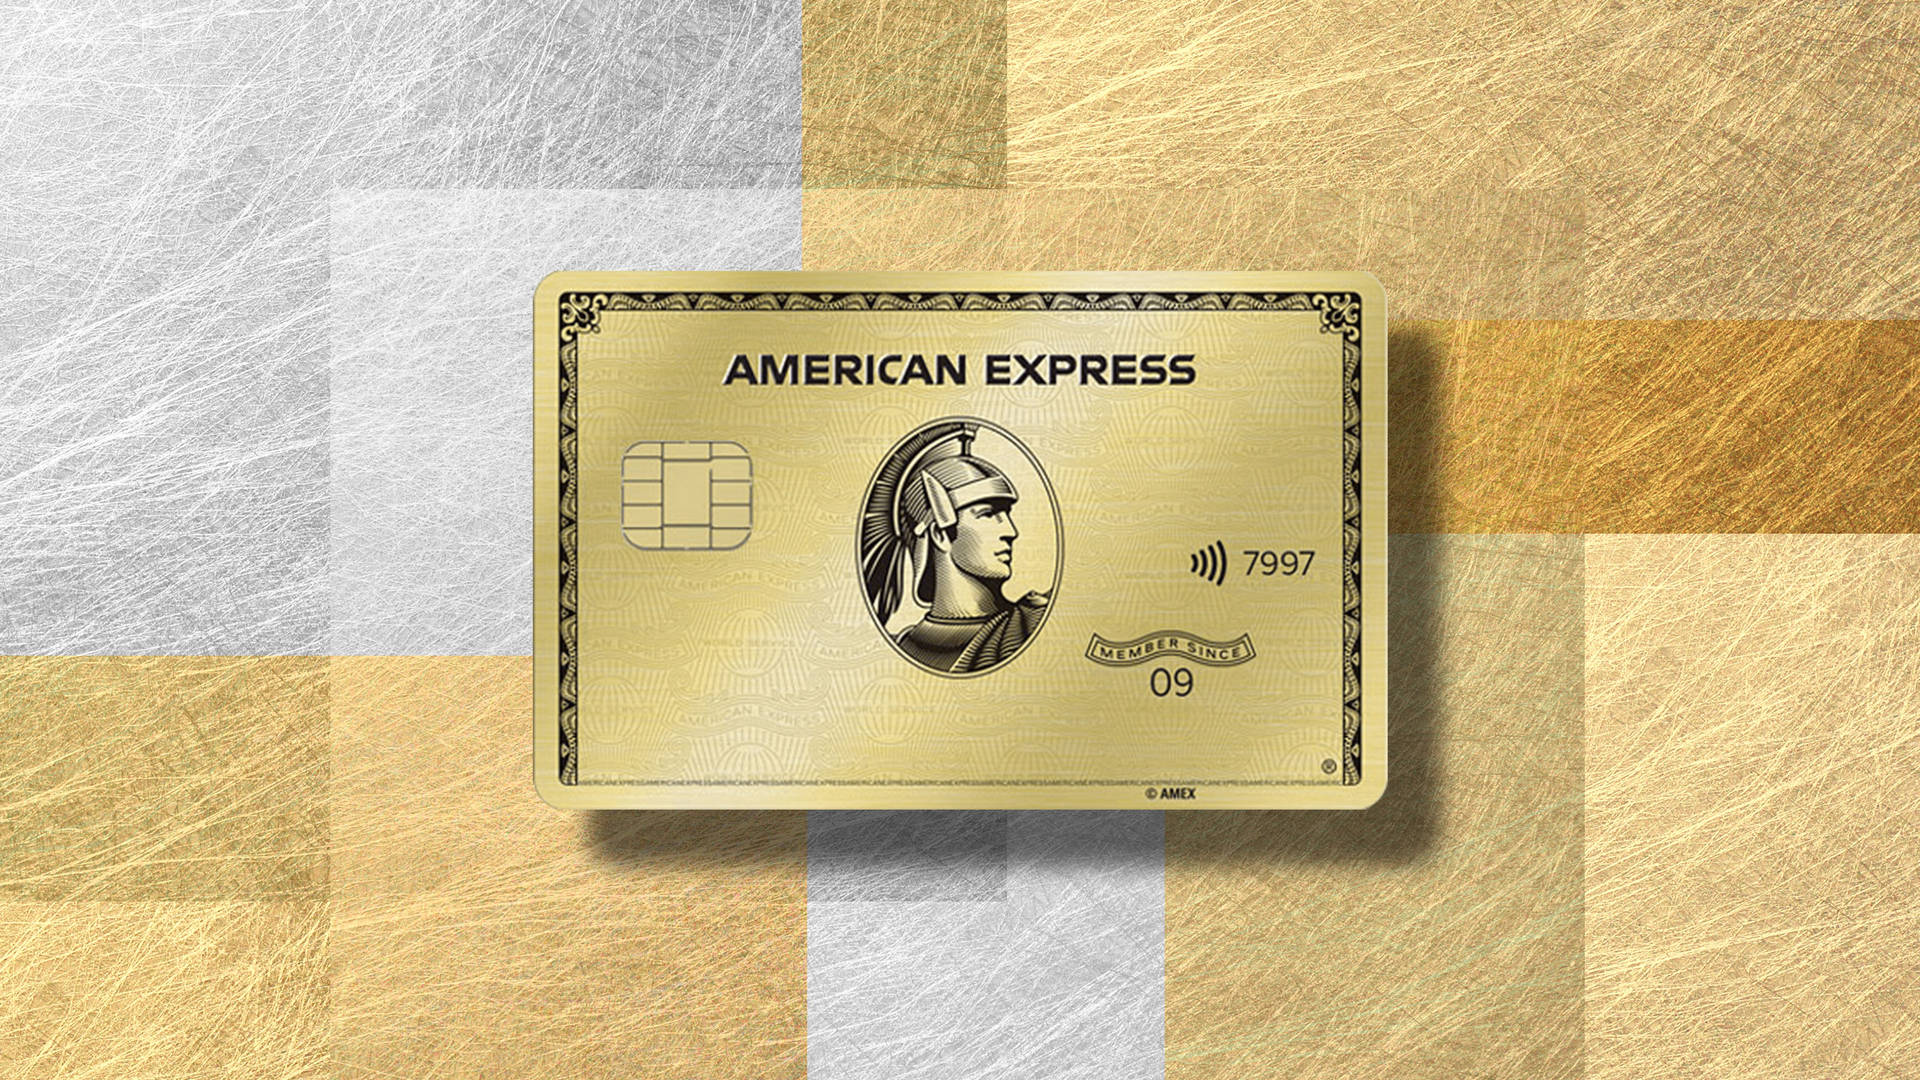
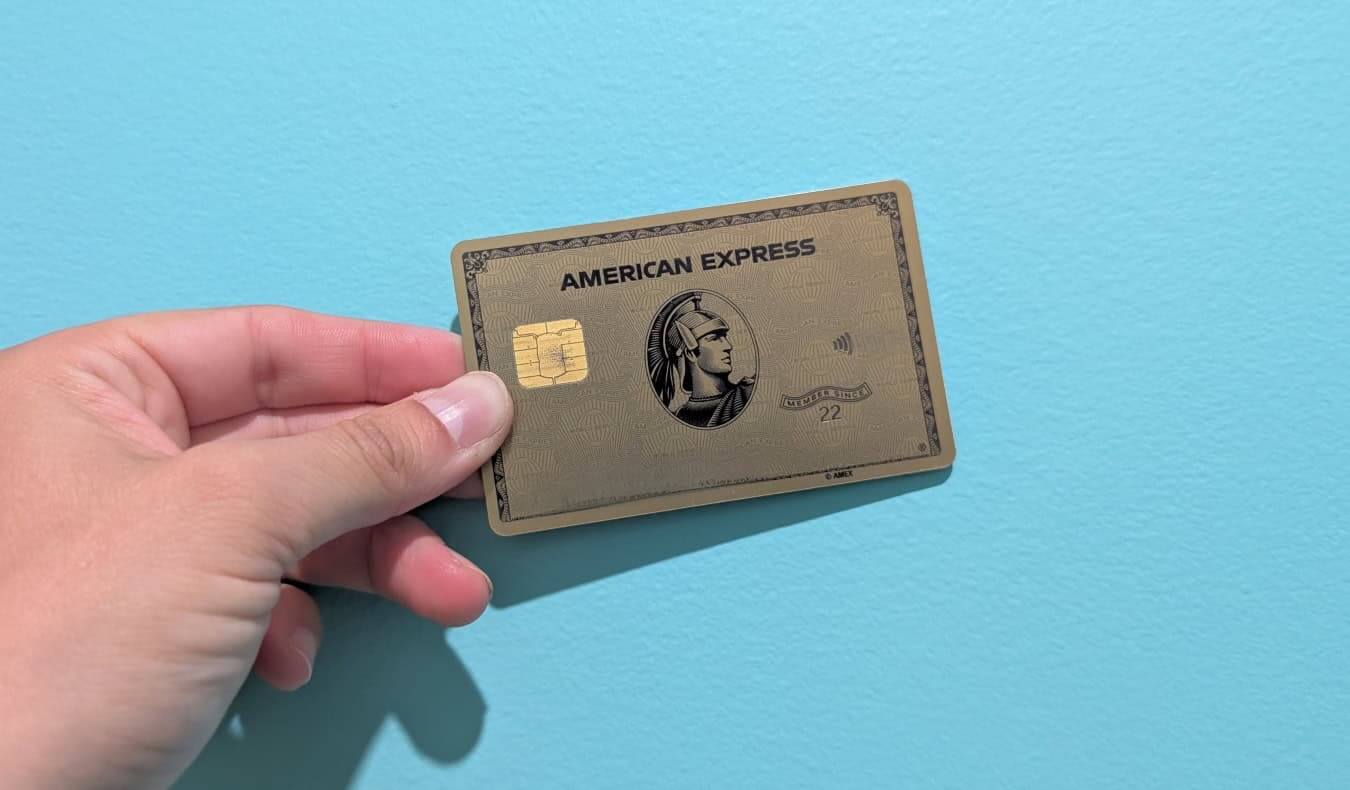
An American Express card is a highly beneficial financial tool for individuals who prioritize premium customer service, robust travel rewards, and comprehensive consumer protections. While often carrying higher annual fees, the value derived from statement credits, airport lounge access, and the flexible Membership Rewards program frequently outweighs the costs for disciplined spenders and frequent travelers.
For decades, American Express (Amex) has maintained a reputation as a "prestige" brand in the payments industry. However, as we move through 2026, the company has successfully pivoted from being an exclusive club for the wealthy to a versatile financial partner offering products for a wide range of lifestyles. Whether you are looking for luxury travel perks, high-yield cash back on groceries, or a tool to manage business expenses, American Express remains a dominant player for several specific reasons.
The Value Proposition of the American Express Ecosystem
Deciding if an American Express card is "good" requires looking beyond the physical card and into the ecosystem American Express has built. Unlike many other issuers that rely solely on interest income, American Express operates a "spend-centric" model. They focus on attracting cardholders who spend significant amounts, which in turn allows them to negotiate better perks with merchant partners.
Unmatched Customer Service and Security
One of the primary reasons consumers remain loyal to American Express is their industry-leading customer service. In an era where automated bots often handle financial inquiries, Amex consistently ranks at the top of J.D. Power’s Credit Card Satisfaction Studies. Their "Global Assist" and 24/7 concierge services (available on premium tiers) provide a level of security that is particularly valuable for international travelers.
Beyond human interaction, the security features are robust. Amex is known for its proactive fraud detection and its willingness to side with the cardholder during legitimate billing disputes. For many, the peace of mind knowing that a "chargeback" or dispute will be handled professionally is worth the price of admission alone.
Consumer Protections and Insurances
When you purchase high-ticket items or book travel with an American Express card, you are often automatically covered by various insurance policies. As of 2026, these protections remain a core pillar of the Amex value proposition:
- Purchase Protection: Most Amex cards cover eligible purchases against accidental damage or theft for up to 90 days.
- Extended Warranty: Amex typically adds an additional year to the manufacturer’s warranty for eligible items with warranties of five years or less.
- Trip Delay and Cancellation Insurance: Premium cards like the Platinum and Gold offer significant reimbursement if your travel plans are disrupted by weather or illness.
- Cell Phone Protection: Many cards now offer coverage against theft or damage to your smartphone, provided you pay your monthly bill with the card.
Understanding Membership Rewards (MR) Points
The "Membership Rewards" program is often cited by financial experts as the most flexible and valuable points currency in the market. Unlike "cash back" which has a fixed value, MR points can be transferred to a variety of airline and hotel partners, often at a 1:1 ratio.
Flexibility and Transfer Partners
The true power of an American Express card lies in the ability to move points to partners like Delta Air Lines, British Airways, Hilton, and Marriott. This allows cardholders to "arbitrage" their points. For example, while 50,000 points might be worth $500 when used for a statement credit, those same points could be transferred to an airline partner to book a business-class flight worth $2,000.
In 2026, the list of partners remains extensive, covering all three major airline alliances (Star Alliance, SkyTeam, and Oneworld). This flexibility ensures that you are never locked into a single airline’s loyalty program, protecting you against devaluations in any one specific carrier’s points system.
Redemptions Beyond Travel
While travel offers the highest "cents per point" (CPP) value, American Express provides multiple ways to use points:
- Cover Your Charges: Use points to pay for previous purchases on your statement.
- Amex Travel Portal: Book flights, hotels, or cruises directly through the Amex website.
- Gift Cards and Shopping: Redeem points at various retailers, though this usually yields the lowest value.
Comparing Popular American Express Cards in 2026
To determine if an American Express card is good for your specific needs, you must compare the different tiers. The "best" card depends entirely on your spending habits.
| Feature | The Platinum Card® | American Express® Gold Card | Blue Cash Preferred® Card |
|---|---|---|---|
| Primary Focus | Luxury Travel & Lifestyle | Dining & Groceries | Everyday Cash Back |
| Annual Fee | High (Approx. $695) | Moderate (Approx. $325) | Low (Approx. $95) |
| Key Earning Rate | 5x on Flights & Hotels | 4x on Dining & US Supermarkets | 6% on US Supermarkets |
| Main Perk | Global Lounge Collection | Annual Dining Credits | Cash Back Statement Credits |
| Best For | Frequent Flyers | Foodies & Families | Budget-Conscious Shoppers |
The Platinum Card: The Traveler's Choice
The Platinum Card is often viewed as the flagship American Express product. In 2026, it remains the gold standard for airport lounge access. Cardholders get entry to the Centurion Lounge network, Delta Sky Clubs (when flying Delta), and Priority Pass lounges. When you factor in the various "lifestyle credits"—such as those for digital entertainment, Uber, and Saks Fifth Avenue—the effective annual fee can drop significantly, provided you were already planning to spend money with those merchants.
The Gold Card: The Everyday Powerhouse
For the average consumer, the Gold Card is often the "better" card. Because most people spend more on groceries and dining than they do on luxury airfare, the 4x multiplier on these categories makes it one of the fastest ways to accumulate points. It bridges the gap between a high-end travel card and a functional daily driver.
Blue Cash Preferred: Simple and Effective
Not everyone wants to manage travel points. For those who prefer straightforward savings, the Blue Cash Preferred card offers one of the highest cash-back rates available for U.S. supermarkets and streaming services. It is an excellent example of Amex providing value to those who don't necessarily travel but want a premium service experience.
The Financial Requirements: Who Can Get an Amex?
While American Express has expanded its reach, they still maintain relatively high standards for approval. Understanding these requirements is essential before applying.
Credit Score and Income
Generally, a "Good" to "Excellent" credit score (typically 700 or higher) is required for the most popular Amex cards. However, in recent years, Amex has introduced tools like "Apply with Confidence," which allows applicants to see if they are approved with a soft credit pull before any impact occurs to their credit score.
Income requirements vary. While you don't need to be a millionaire to own a Platinum card, you do need to demonstrate a stable income that justifies the credit limit or "Pay Over Time" limit American Express extends to you.
Credit Cards vs. "Pay Over Time" Cards
Historically, Amex was famous for its "Charge Cards," which required the balance to be paid in full every month. In 2026, most American Express cards (like the Gold and Platinum) feature "Pay Over Time" capabilities. This makes them function similarly to traditional credit cards where you can carry a balance with interest, though it is always financially optimal to pay in full to avoid high APRs.
Potential Drawbacks: Why Amex Might Not Be "Good" for You
No financial product is perfect. There are three main reasons why an American Express card might not be the right choice for certain individuals.
1. High Annual Fees
The "coupon book" nature of modern Amex cards requires effort. To justify a $695 annual fee on the Platinum card, you must actively track and use your Uber credits, airline fee credits, and hotel credits. If you find this management tedious or if you don't naturally shop at the partnered merchants, you may end up losing money on the card.
2. Merchant Acceptance
While Amex acceptance in the United States is now nearly at parity with Visa and Mastercard (roughly 99% of credit-card-accepting merchants), international acceptance can still be hit-or-miss. In Europe, Asia, and South America, smaller vendors may still prefer Visa or Mastercard due to the lower merchant fees those networks charge. Travelers should always carry a backup card from a different network.
3. Temptation of High Spending
Because American Express cards often come with high "limits" or no pre-set spending limits, there is a risk of overspending. The rewards are only "rewards" if you aren't paying monthly interest that negates their value. The high APRs typical of premium cards in 2026 mean that carrying a balance is a very expensive proposition.
Strategic Tips for Prospective Cardholders
If you decide that an American Express card is right for you, following a few strategic steps will maximize your benefit:
- Wait for a "Welcome Offer": Never apply for an Amex card when the sign-up bonus is at its historical low. Amex frequently runs "elevated" offers where you can earn 100,000 to 150,000 points for the Platinum card or 60,000 to 90,000 for the Gold.
- Understand the "Once Per Lifetime" Rule: American Express generally limits you to receiving a welcome bonus on a specific card once in your lifetime. This makes the timing of your application crucial.
- Utilize the Amex Offers Program: In the Amex mobile app, you can "add" specific discounts for retailers (e.g., "$10 back when you spend $50 at a specific store"). These can easily add up to hundreds of dollars in savings per year, further offsetting the annual fee.
Frequently Asked Questions
Does American Express offer any cards without an annual fee?
Yes. American Express offers several cards with no annual fee, such as the Blue Cash Everyday® Card and the Amex EveryDay® Credit Card. These cards still provide access to the Amex ecosystem and the "Amex Offers" program, though their reward earning rates and travel perks are lower than the premium versions.
How much are Amex Membership Rewards points worth?
The value of MR points varies by redemption. When transferred to high-value airline partners for international business class, they can be worth 2.0 cents per point or more. When used for statement credits ("Cover Your Charges"), they are generally worth only 0.6 cents per point. For the best value, they should almost always be used for travel.
Is American Express harder to get than a Chase or Citi card?
Not necessarily. While Amex looks for good credit scores, they are known for being more "approvable" for those with a limited credit history but a high income compared to some other issuers. Additionally, their "Apply with Confidence" feature makes the application process less risky for your credit score.
Can I have more than one American Express card?
Yes, you can hold multiple Amex cards simultaneously. Many users employ a "trifecta" strategy, holding a Platinum card for travel, a Gold card for dining, and a Blue Business® Plus card for all other "non-category" spending to maximize point accumulation.
Does American Express report to all three credit bureaus?
Yes. American Express reports your account activity to Equifax, Experian, and TransUnion. This means responsible use of an Amex card—paying on time and keeping your utilization low—will help build your credit score across all major reporting agencies.
Final Recommendation: Is It Worth It?
An American Express card is a "good" credit card to have if you are a proactive consumer who values service and rewards over a simple, fee-free experience. If you travel at least twice a year and spend heavily on dining or groceries, cards like the Platinum or Gold can provide thousands of dollars in value through lounge access, insurance, and points. However, if you prefer a "set it and forget it" financial life or if you struggle with credit card debt, the high annual fees and interest rates of American Express may be more of a burden than a benefit. Before applying, audit your last six months of spending to see which Amex "multiplier" would have earned you the most rewards.