In 2026, payday loans remain a high-cost, short-term financial tool for Redding residents facing immediate cash shortages. While they offer rapid access to funds without a credit check, they are rarely considered a "good" option due to triple-digit APRs and a maximum loan limit of $300 under California law. For most, local credit unions or community assistance programs in Shasta County provide safer, more sustainable alternatives.
Understanding the Landscape of Payday Lending in California
To determine if a payday loan is the right choice for your situation in Redding, it is essential to first understand the legal and regulatory environment that governs these transactions. In California, payday loans are officially known as Deferred Deposit Transactions. These are regulated under the California Deferred Deposit Transaction Law, overseen by the Department of Financial Protection and Innovation (DFPI).
As of 2026, the fundamental rules remain strict. A lender cannot provide a loan for more than $300. When you take out this loan, you typically provide the lender with a post-dated check or authorization to electronically debit your bank account on your next payday. The lender provides you with the cash upfront, minus a fee.
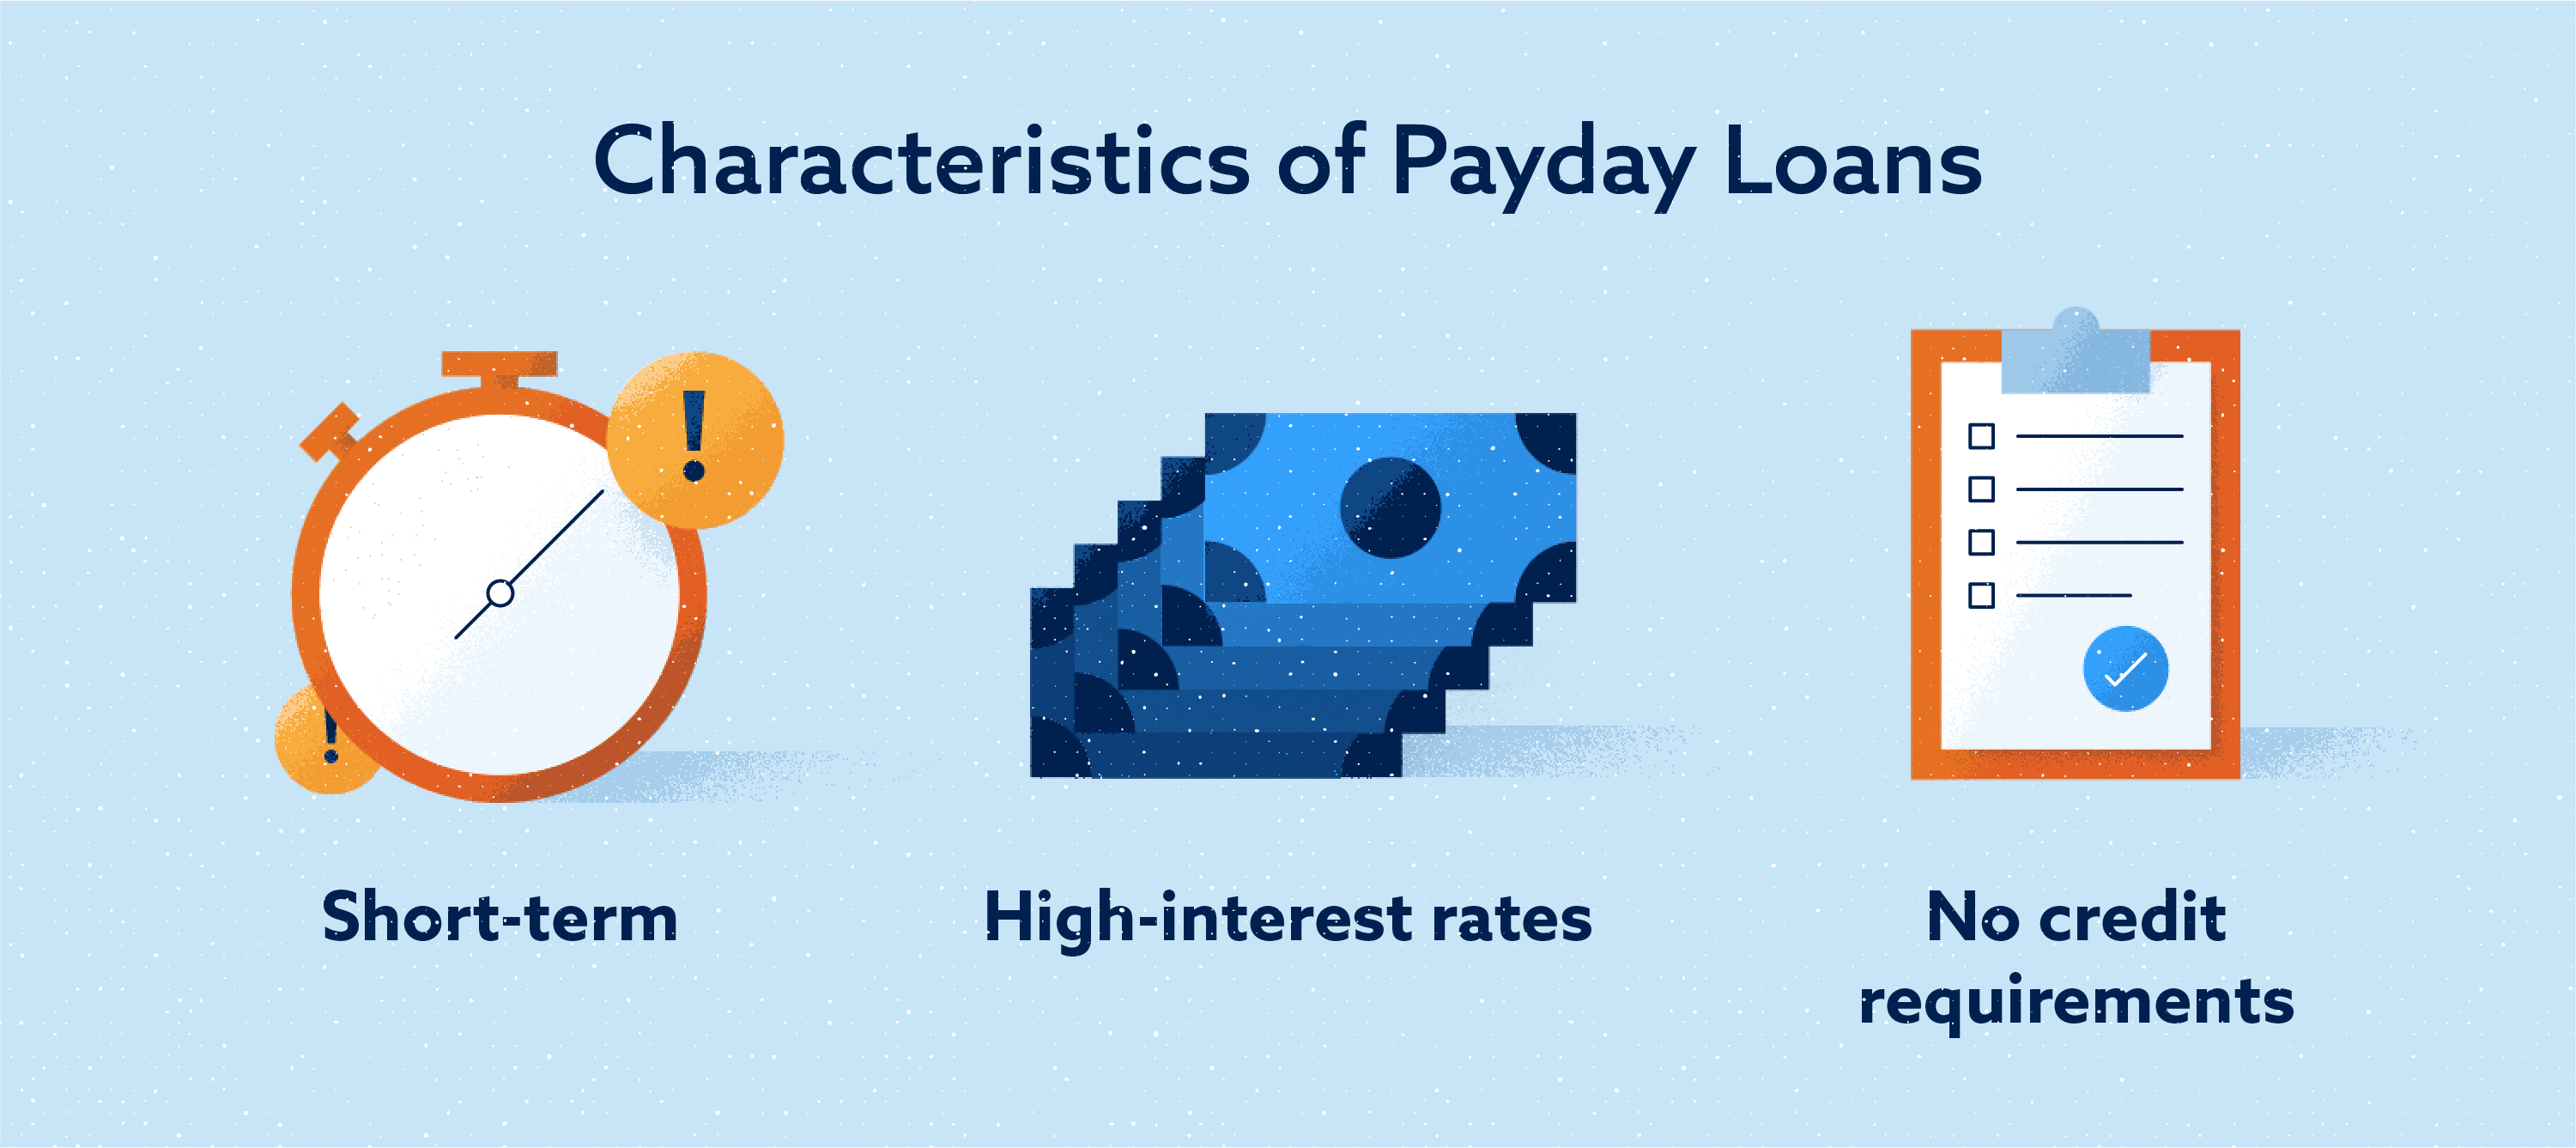
The maximum fee a lender can charge is 15% of the face value of the check. If you write a check for $300, the lender takes $45 as a fee and gives you $255. While a $45 fee might sound manageable for a one-time emergency, the financial danger lies in the effective Annual Percentage Rate (APR). Because these loans are usually due within 14 to 31 days, that 15% fee translates to an APR of approximately 372% to 460%, depending on the exact length of the loan term.
The Economic Context of Redding, California in 2026
Redding serves as the economic hub for the North Valley and Shasta County. While the city has seen growth in sectors like healthcare and tourism, many residents continue to navigate a cost-of-living index that fluctuates with state-wide trends. In 2026, housing costs and utility rates in the North State remain significant pressures on household budgets.
For a resident in Redding, a $255 cash infusion (the typical net amount of a maximum payday loan) may cover a utility bill or a minor car repair to ensure transit to work. However, in a city where the median income may not always keep pace with the rising costs of goods, the risk of the "debt trap" is high. If a borrower cannot afford their basic expenses before the loan, they are unlikely to afford those same expenses plus the $300 repayment two weeks later. This often leads to a cycle where the borrower must take out another loan immediately after paying the first, leading to a perpetual state of debt.
Pros and Cons of Payday Loans for Redding Residents
Evaluating whether these loans are a "good" option requires a balanced look at their utility versus their long-term impact on financial health.
The Arguments in Favor (The "Pros")
- Accessibility: Payday lenders in Redding, such as those found along Churn Creek Road or Dana Drive, typically do not perform a traditional hard credit pull. This makes them one of the few options for residents with "deep subprime" credit scores or no credit history at all.
- Speed: In most cases, you can walk into a storefront in Redding and walk out with cash or a debit card load in under 30 minutes. Online lenders can often deposit funds by the next business day.
- Minimal Requirements: Usually, all that is required is an active bank account, a steady source of income (which can include Social Security or disability payments), and proof of residency in California.
The Arguments Against (The "Cons")
- Extreme Cost: The APRs are astronomical compared to credit cards (which average 18-30%) or personal loans (which average 10-36%).
- Small Loan Limits: Because the cap is $300, a payday loan is insufficient for major emergencies like a transmission failure or a medical deductible.
- Short Repayment Window: Most Redding employers pay bi-weekly or monthly. Having to pay back the full amount plus fees in a single lump sum can deplete a worker's entire paycheck, leaving nothing for the next month's rent.
- No Credit Building: Most payday lenders do not report positive payment history to the major credit bureaus (Equifax, Experian, TransUnion). Therefore, even if you pay on time, it will not help improve your credit score for future, cheaper borrowing.
Comparing Financial Options in Redding
Before committing to a high-interest payday loan, Redding residents should compare the costs of various borrowing methods available in 2026.
| Feature | Payday Loan (Storefront/Online) | Credit Union PAL (Payday Alternative Loan) | Traditional Credit Card | Shasta County Community Assistance |
|---|---|---|---|---|
| Max Amount | $300 (CA Law) | Typically $200 - $1,000 | Varies by Credit Limit | Varies by Need |
| Typical APR | 370% - 460% | 28% (capped by NCUA) | 18% - 29% | 0% (Grant/Gift) |
| Repayment Term | 14 - 31 days | 1 - 6 months | Ongoing (Monthly) | N/A |
| Credit Check | No | Yes (usually "soft" pull) | Yes (Hard pull) | No |
| Speed | Instant / Same Day | 1 - 3 Business Days | Instant (if card is active) | 3 - 10 Business Days |
Local Alternatives to Payday Loans in Redding
Redding has a robust network of credit unions and community organizations that offer more favorable terms for those in a financial pinch. In 2026, these should be the first stop for anyone considering a short-term loan.
Redding-Based Credit Unions
Credit unions like Sierra Central Credit Union, Members 1st Credit Union, and Rolling Hills Federal Credit Union often provide small-dollar loans to members. Many credit unions offer Payday Alternative Loans (PALs). These are designed specifically to compete with payday lenders. They offer lower interest rates (capped at 28%) and longer repayment terms, allowing you to pay back the money over several months rather than weeks.
Employer-Based Advances
Several large employers in the Redding area, including those in the healthcare and retail sectors, have begun integrated "earned wage access" programs. These allow employees to tap into the money they have already earned before payday for a nominal fee or for free, avoiding the 400% APR of a payday lender.
Community and Non-Profit Resources
For those facing a crisis regarding food, utilities, or housing, Redding offers several non-loan alternatives:
- Great Help (formerly Redding One Safe Place): Offers assistance and referrals for those in crisis.
- Shasta County Health and Human Services Agency (HHSA): Can provide information on General Assistance (GA) or CalWORKS for eligible families.
- Local Food Banks: Utilizing the North Valley Food Bank or local church pantries can free up cash that would otherwise be spent on groceries, allowing that money to go toward an urgent bill.
Legal Protections and Rights for Borrowers in 2026
If you decide to proceed with a payday loan in Redding, you are protected by specific California statutes. Understanding these rights is vital to avoiding predatory behavior.
- The Single Loan Rule: A lender cannot have more than one loan outstanding with you at any given time. They also cannot "roll over" a loan. This means they cannot charge you a new fee to push the due date back; the original loan must be paid in full before a new one is issued.
- No Criminal Prosecution: In California, it is illegal for a payday lender to threaten you with jail time or criminal prosecution for a bounced check. Failure to pay a payday loan is a civil matter, not a criminal one.
- Right to Cancel: You generally have the right to void the contract and return the money by the end of the next business day without penalty.
- Fee Limits: If your check bounces, the lender can only charge a one-time NSF (non-sufficient funds) fee of up to $15. They cannot repeatedly hit your account with fees that drain your balance.
How to Identify Predatory Lenders
Not all lenders operating in the Redding area are equal. While storefront lenders are strictly regulated by the State of California, the internet is home to "tribal lenders" and offshore entities that claim they are not subject to California's $300 limit or 15% fee cap.
Red Flags to Watch For:
- Loans exceeding $300: If an online lender offers you $500 or $1,000 for a payday loan, they are likely operating outside of California law. This means you lose the protections offered by the DFPI.
- No License Verification: Before signing, check the DFPI website to ensure the lender is licensed to operate in California.
- Upfront Payment: Never pay an "origination fee" or "insurance fee" upfront before receiving your loan. This is a common hallmark of loan scams.
Steps to Take if You Are Struggling with Payday Debt
If you already have a payday loan in Redding and are struggling to pay it back, do not take out a second loan. Instead:
- Request an Extension: While not legally required to offer one, some lenders will provide a payment plan if you contact them before the due date.
- Contact a Credit Counselor: Non-profit agencies like the National Foundation for Credit Counseling (NFCC) can help Redding residents build a budget and negotiate with creditors.
- Notify Your Bank: If you are worried about a lender draining your account and leaving you unable to pay rent, you can revoke the ACH authorization. Note that you still owe the debt, but this gives you control over the timing of the payment.
- Prioritize Essentials: Always pay for housing, food, and necessary transport (like a Redding Area Bus Authority pass or car insurance) before paying a high-interest payday lender.
Expert Recommendation: Is it a Good Option?
From a technical financial perspective, a payday loan is almost never a good option for a Redding resident. The only scenario where it might be considered acceptable is if the alternative is a significantly higher cost—such as a $100 late fee on a mortgage or the disconnection of a vital utility that would cost hundreds to reconnect.
Even in these extreme cases, the borrower should have a guaranteed source of funds coming in to pay off the loan in full on the very next payday. Using a payday loan to cover recurring monthly expenses like groceries or rent is a sign of a structural budget deficit that a high-interest loan will only worsen.
For 2026, the recommendation for those in Redding is to exhaust all "soft" options first:
- Ask your employer for an advance.
- Sell unused items on local marketplaces.
- Apply for a small loan at a local credit union.
- Use a credit card (even with interest, it is 10 times cheaper than a payday loan).
Frequently Asked Questions
What is the maximum payday loan amount in Redding, CA for 2026?
The maximum amount is $300. This is a state-wide limit set by California law. After the maximum 15% fee is deducted, the most cash a borrower will typically receive is $255.
Can I have multiple payday loans in California?
No. California law prohibits lenders from issuing a new loan to a borrower who already has an outstanding deferred deposit transaction. Furthermore, you cannot "roll over" a loan into a new one by paying only the fee.
Do Redding payday lenders check my credit score?
Most storefront lenders in Redding do not perform a "hard" credit pull through the major bureaus. However, they may use specialized services like Teletrack or Clarity to see if you have outstanding payday loans with other lenders or a history of bounced checks.
What happens if I can't pay back my payday loan in Redding?
The lender will likely attempt to deposit your check or debit your account. If the funds are not there, you will owe an NSF fee to your bank and a one-time $15 fee to the lender. The debt may be sold to a collection agency, which will impact your credit score, but you cannot be arrested for failing to pay.
Are there any 0% interest loans in Shasta County?
While not "loans" in the traditional sense, various community grants and emergency assistance programs through organizations like the Salvation Army or local religious groups can provide one-time financial aid for emergencies that does not need to be repaid.
Is an online payday loan better than a storefront in Redding?
Storefront lenders are often easier to verify as being California-compliant. Online lenders can be convenient but carry a higher risk of being unlicensed "offshore" or "tribal" lenders that do not follow California's interest rate caps or consumer protection laws.