Obtaining life insurance quotes in Atlantic Beach, FL, in 2026 involves comparing term and permanent policies through digital aggregators or local Duval County agencies. Florida residents benefit from a mandatory 14-day free-look period and a 30-day grace period, ensuring robust consumer protection while navigating the competitive landscape of the Sunshine State’s insurance market.
The process of securing financial protection for your family in Atlantic Beach is unique, influenced by Florida’s specific regulatory environment and the diverse demographic profile of the Jacksonville beach communities. Whether you are a young professional working in downtown Jacksonville, a military family stationed near Naval Station Mayport, or a retiree enjoying the coastal lifestyle, understanding how to navigate life insurance quotes is essential for long-term fiscal health.
Understanding Life Insurance Policy Types in 2026
Before soliciting quotes, it is imperative to distinguish between the primary vehicles of life insurance. In 2026, the market has bifurcated into highly streamlined term products and increasingly flexible permanent solutions.
Term Life Insurance
Term life insurance remains the most popular choice for residents of Atlantic Beach due to its simplicity and affordability. It provides coverage for a specific period—typically 10, 20, or 30 years. If the insured passes away during this "term," the death benefit is paid to the beneficiaries tax-free.
In 2026, many term policies now include accelerated death benefits as a standard feature. This allows policyholders to access a portion of the death benefit if diagnosed with a terminal or chronic illness. For families in Atlantic Beach with high mortgages or young children, a 20-year term policy often serves as the most cost-effective "safety net."
Permanent Life Insurance
Permanent insurance, including Whole Life and Universal Life, offers lifelong coverage and a cash value component.
- Whole Life: Provides a fixed premium and a guaranteed death benefit. The cash value grows at a steady rate set by the insurer.
- Universal Life (UL): Offers more flexibility, allowing policyholders to adjust their premiums and death benefits as their financial situation changes.
- Indexed Universal Life (IUL): In 2026, IULs remain popular for those looking to link cash value growth to market indices (like the S&P 500) while maintaining a floor to protect against market losses.
Residents of Atlantic Beach often utilize permanent policies as part of a broader estate planning strategy, particularly to mitigate the impact of federal estate taxes for high-net-worth individuals.
Florida-Specific Insurance Regulations and Protections
Florida’s insurance market is governed by the Florida Department of Financial Services (DFS). When reviewing quotes in Atlantic Beach, you are protected by several state-mandated provisions that may differ from other states.
The 14-Day Free-Look Period
Florida law requires a "free-look" period for life insurance policies. Once you receive your policy document, you have 14 days to review the terms. If you decide the policy does not meet your needs, you can cancel it for a full refund of all premiums paid. This is an essential safeguard for Atlantic Beach consumers who may feel pressured during the sales process.
Grace Period Requirements
Florida mandates a 30-day grace period. If you miss a premium payment, the insurance company cannot immediately cancel your coverage. They must provide at least 30 days for you to make the payment. For policyholders over the age of 64, Florida law (Statute 627.4557) often requires an additional notification to a secondary addressee to prevent unintentional lapses in coverage.
Florida Life & Health Insurance Guaranty Association (FLAHIGA)
If an insurance company becomes insolvent, the Florida Life & Health Insurance Guaranty Association provides a safety net. As of 2026, the association generally protects life insurance death benefits up to $300,000 and cash surrender values up to $100,000 per person. While it is always best to choose a company with a high A.M. Best or Standard & Poor’s rating, this association provides peace of mind for Atlantic Beach residents.
Factors Influencing Your 2026 Life Insurance Quote
When you request a quote in Atlantic Beach, underwriters evaluate several variables to determine your risk profile. While some factors are universal, others have evolved with the technology of 2026.
1. The Shift to Accelerated Underwriting
By 2026, the "paramedical exam" (blood draw and physical) is no longer the default for every policy. Many carriers now use algorithmic underwriting, pulling data from your electronic health records (EHR), motor vehicle reports, and prescription drug history to provide a quote in minutes. Residents with a clean health history can often secure "Best Class" rates without a medical exam.
2. Age and Gender
Age remains the primary driver of cost. A 30-year-old Atlantic Beach resident will pay significantly less for a 20-year term policy than a 50-year-old. Statistically, women still have longer life expectancies than men, which is reflected in lower premium quotes for females.
3. Health History and Lifestyle
Tobacco use remains the single largest controllable factor in quote pricing. In Atlantic Beach, where the outdoor lifestyle is prevalent, insurers also look at "avocation risks." While surfing at the Atlantic Beach pier isn't typically a rating factor, activities like private aviation or technical scuba diving might lead to "flat extra" charges on your premium.
4. Credit-Based Insurance Scores
While controversial, many insurers in 2026 use credit-based data as a predictor of policy longevity and risk. Maintaining a strong credit score can indirectly lead to more favorable life insurance quotes in Florida.
Estimated Life Insurance Rates in Atlantic Beach (2026)
The following table provides estimated monthly premiums for a $500,000 20-Year Term Life Insurance Policy for non-smokers in excellent health residing in the 32233 zip code.
| Age | Gender | Estimated Monthly Premium (Standard) | Estimated Monthly Premium (Preferred Plus) |
|---|---|---|---|
| 25 | Male | $22.50 | $16.75 |
| 25 | Female | $19.10 | $14.20 |
| 35 | Male | $28.40 | $21.15 |
| 35 | Female | $24.80 | $18.50 |
| 45 | Male | $58.10 | $44.30 |
| 45 | Female | $49.25 | $37.60 |
| 55 | Male | $142.00 | $108.00 |
| 55 | Female | $112.50 | $86.40 |
Note: These figures are estimates based on 2026 market trends. Actual quotes depend on individual medical underwriting and specific carrier guidelines.
How to Compare Atlantic Beach Life Insurance Quotes
To ensure you are getting the most competitive rate in Duval County, follow this structured comparison process.
Step 1: Determine Your Coverage Gap
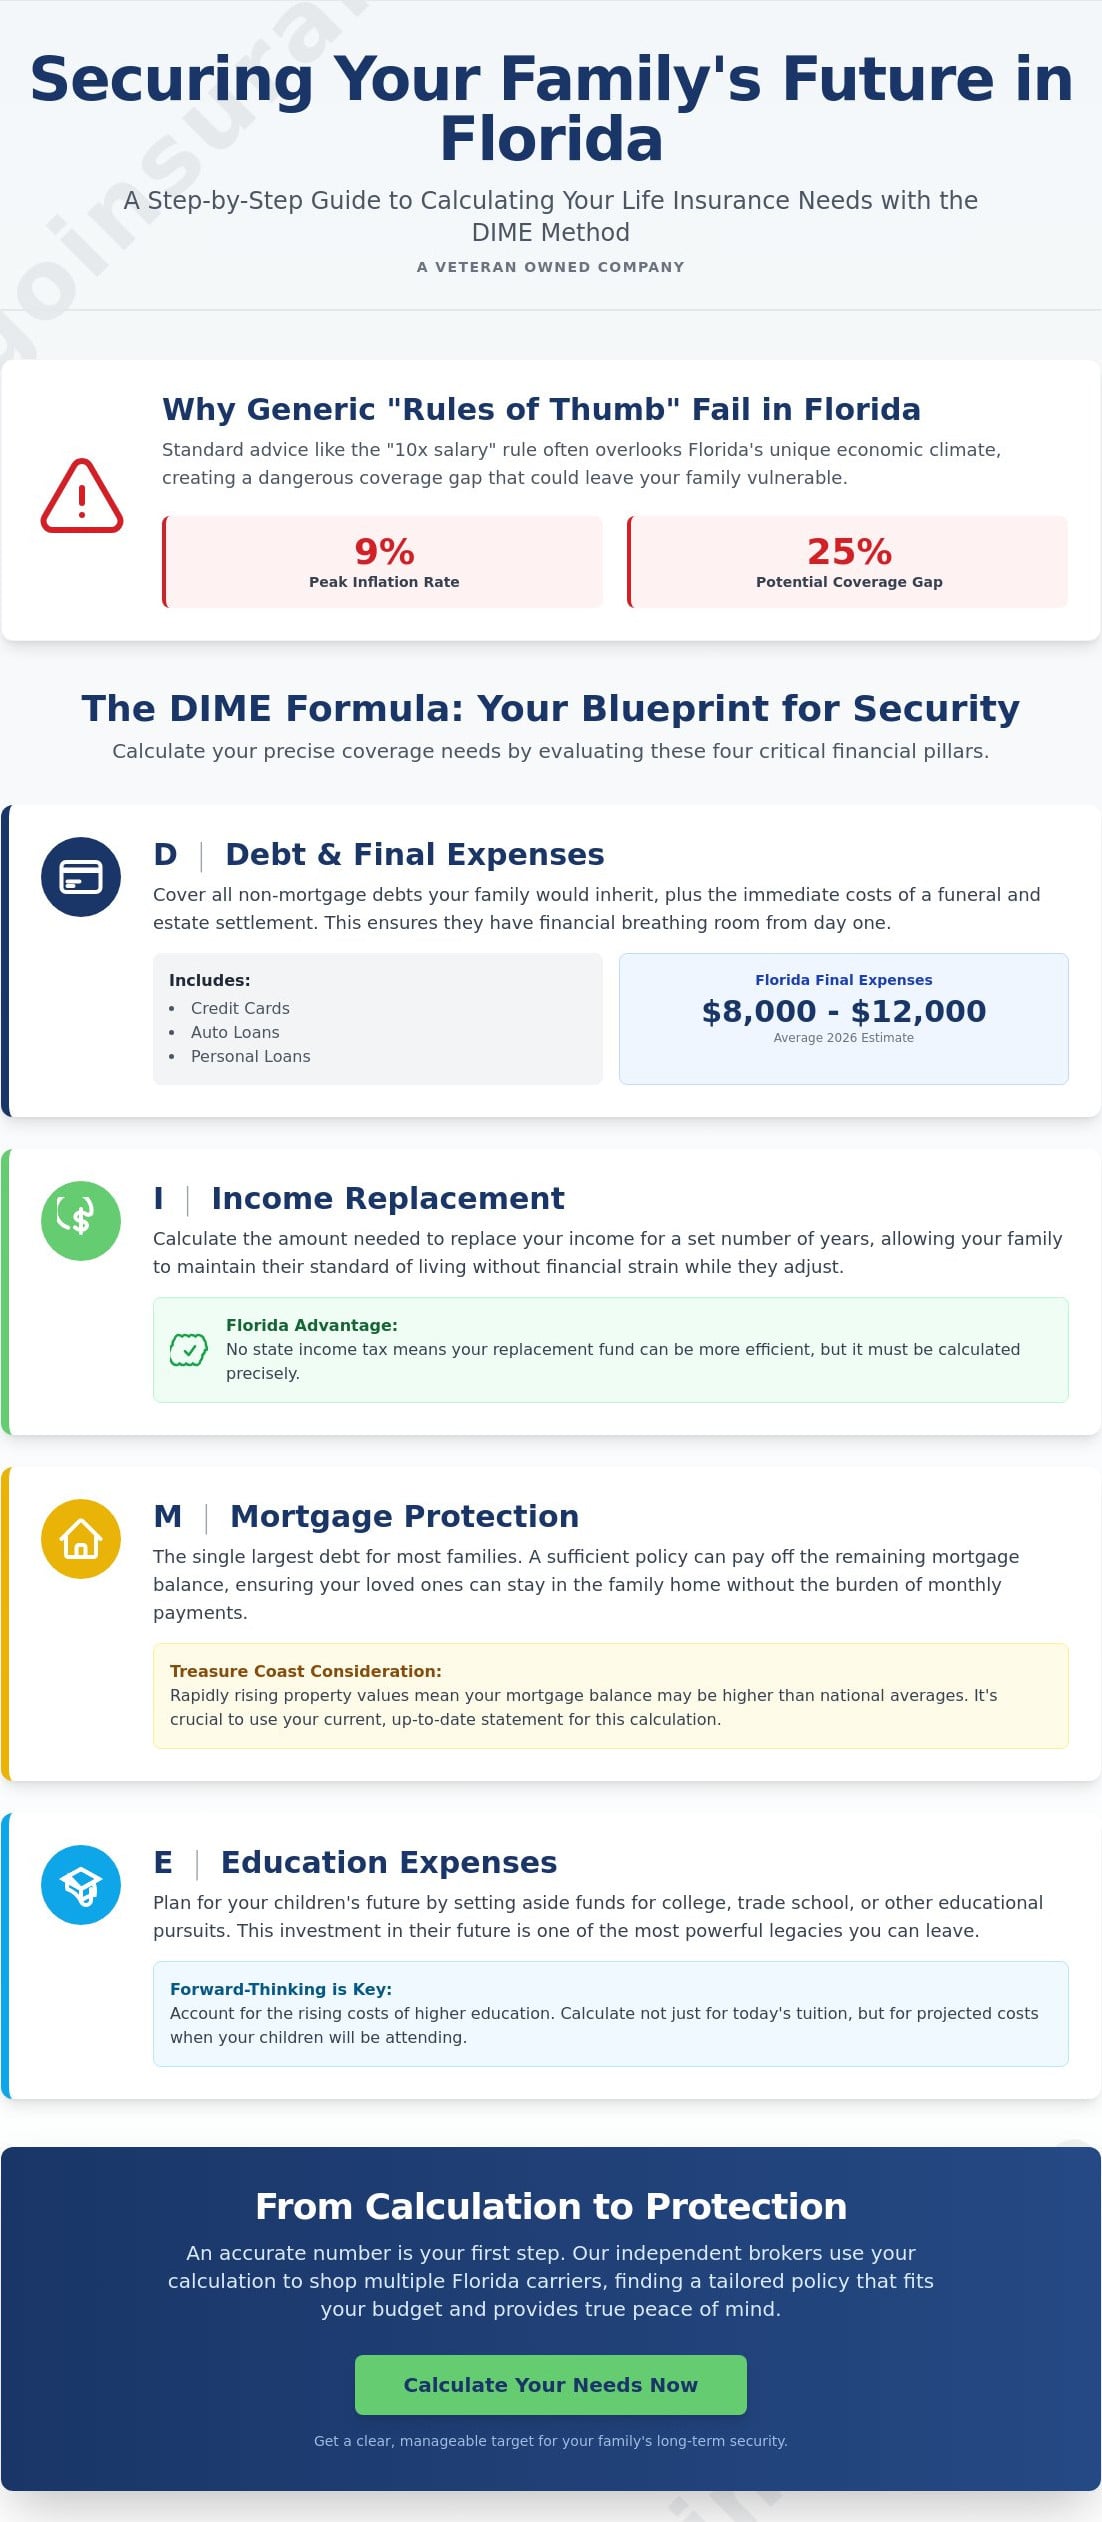
Do not guess your coverage amount. Use the DIME formula to calculate your needs:
- Debt: Total outstanding debt (excluding mortgage).
- Income: Annual income multiplied by the number of years your family needs support.
- Mortgage: The balance on your Atlantic Beach home.
- Education: Future college tuition for children.
Step 2: Choose Between Local Agents and Online Aggregators
Atlantic Beach offers two primary paths for quotes. Local independent agents in the Jacksonville area offer personalized service and can shop multiple carriers. They are particularly helpful if you have complex health issues or need to coordinate life insurance with a business buy-sell agreement.
Conversely, online quote engines provide instant gratification and allow you to compare 20+ carriers simultaneously. In 2026, the most sophisticated platforms offer "soft credit pull" quotes that do not impact your credit score.
Step 3: Verify Carrier Financial Strength
A low quote is meaningless if the company cannot pay the claim decades from now. Before committing, check the financial strength ratings from agencies like A.M. Best or Fitch Ratings. Look for carriers with an "A" rating or better.
Step 4: Evaluate Riders and Add-ons
Quotes often include "riders" which are optional features. In the humid, coastal climate of Florida, some residents prioritize Waiver of Premium riders, which keep the policy in force if you become totally disabled and cannot work. Another relevant option is the Child Term Rider, which provides a small death benefit for children that can often be converted to permanent coverage later in life without a medical exam.
Common Mistakes to Avoid
- Underestimating the "Inflation Hedge": In 2026, a $500,000 policy does not have the same purchasing power it did a decade ago. Consider laddering policies or purchasing slightly more than you think you need.
- Relying Solely on Group Life Insurance: Many Atlantic Beach residents have life insurance through their employers (e.g., at the Mayo Clinic or CSX). However, these policies are usually not portable. If you change jobs, you lose your coverage, and getting a new policy when you are older or less healthy will be significantly more expensive.
- Waiting to Buy: Every year you wait increases the premium by 5% to 8% on average. Furthermore, you risk developing a medical condition that could make you uninsurable.
- Inaccurate Disclosure: Be honest about your health history and tobacco use. Florida insurers have a two-year contestability period. If the insurer finds you lied on the application during this window, they can deny the claim.
The Role of Life Insurance in Atlantic Beach Estate Planning
For the affluent residents of Atlantic Beach, life insurance is more than just a death benefit; it is a strategic financial tool. In 2026, life insurance is frequently used to:
- Equalize Inheritances: If one child is inheriting a family business or a beachfront property, life insurance proceeds can provide an equivalent cash inheritance for other children.
- Fund Buy-Sell Agreements: For local business owners, life insurance ensures that if a partner passes away, the surviving partner has the cash to buy out the deceased partner's heirs, maintaining business continuity.
- Charitable Giving: Policyholders can name local Jacksonville non-profits as beneficiaries, creating a lasting legacy in the community.
Frequently Asked Questions
Do I need a local Atlantic Beach agent to get a quote?
No. While local agents provide valuable insight into the Florida market, you can obtain and finalize life insurance policies entirely online or over the phone in 2026. However, for complex estate planning or if you prefer a face-to-face relationship, a local Duval County agent is recommended.
How does being a smoker affect my Atlantic Beach life insurance quote?
Tobacco use typically doubles or triples the cost of life insurance. Insurers in 2026 also test for nicotine in many standard applications. If you have quit smoking, most carriers require you to be tobacco-free for at least 12 to 24 months before you qualify for non-smoker rates.
Can I get life insurance if I have a pre-existing condition?
Yes. Many carriers specialize in "impaired risk" underwriting. Conditions like well-managed type 2 diabetes or high blood pressure often still qualify for standard rates. In 2026, specialized high-risk quotes are more accessible through brokers who understand which carriers have the most lenient guidelines for specific ailments.
Are life insurance proceeds taxable in Florida?
Generally, no. Life insurance death benefits are paid to beneficiaries free of federal and state income tax. However, if the policy is owned by the insured, the proceeds may be included in the taxable estate for federal estate tax purposes if the estate exceeds the current exemption limits.
What is "No-Exam" life insurance?
"No-exam" or simplified issue life insurance uses data sources to evaluate your health instead of a physical exam. In 2026, these policies are often priced competitively with traditional underwritten policies for individuals under age 60 with moderate coverage needs (typically up to $1 million or $2 million).
Practical Recommendation for Atlantic Beach Residents
For most individuals in Atlantic Beach, the optimal path is to start by using an online comparison tool to establish a baseline for 20-year or 30-year term rates. This provides a "no-pressure" environment to see how your age and health affect premiums.
Once you have a baseline, consult with a financial advisor or an independent insurance agent who can help you determine if your coverage should be "laddered" (multiple policies of different lengths) or if a permanent policy is necessary for tax or legacy purposes. Always ensure your chosen carrier has a strong financial rating and that you fully understand the Florida "Free Look" provisions before signing your final policy documents.