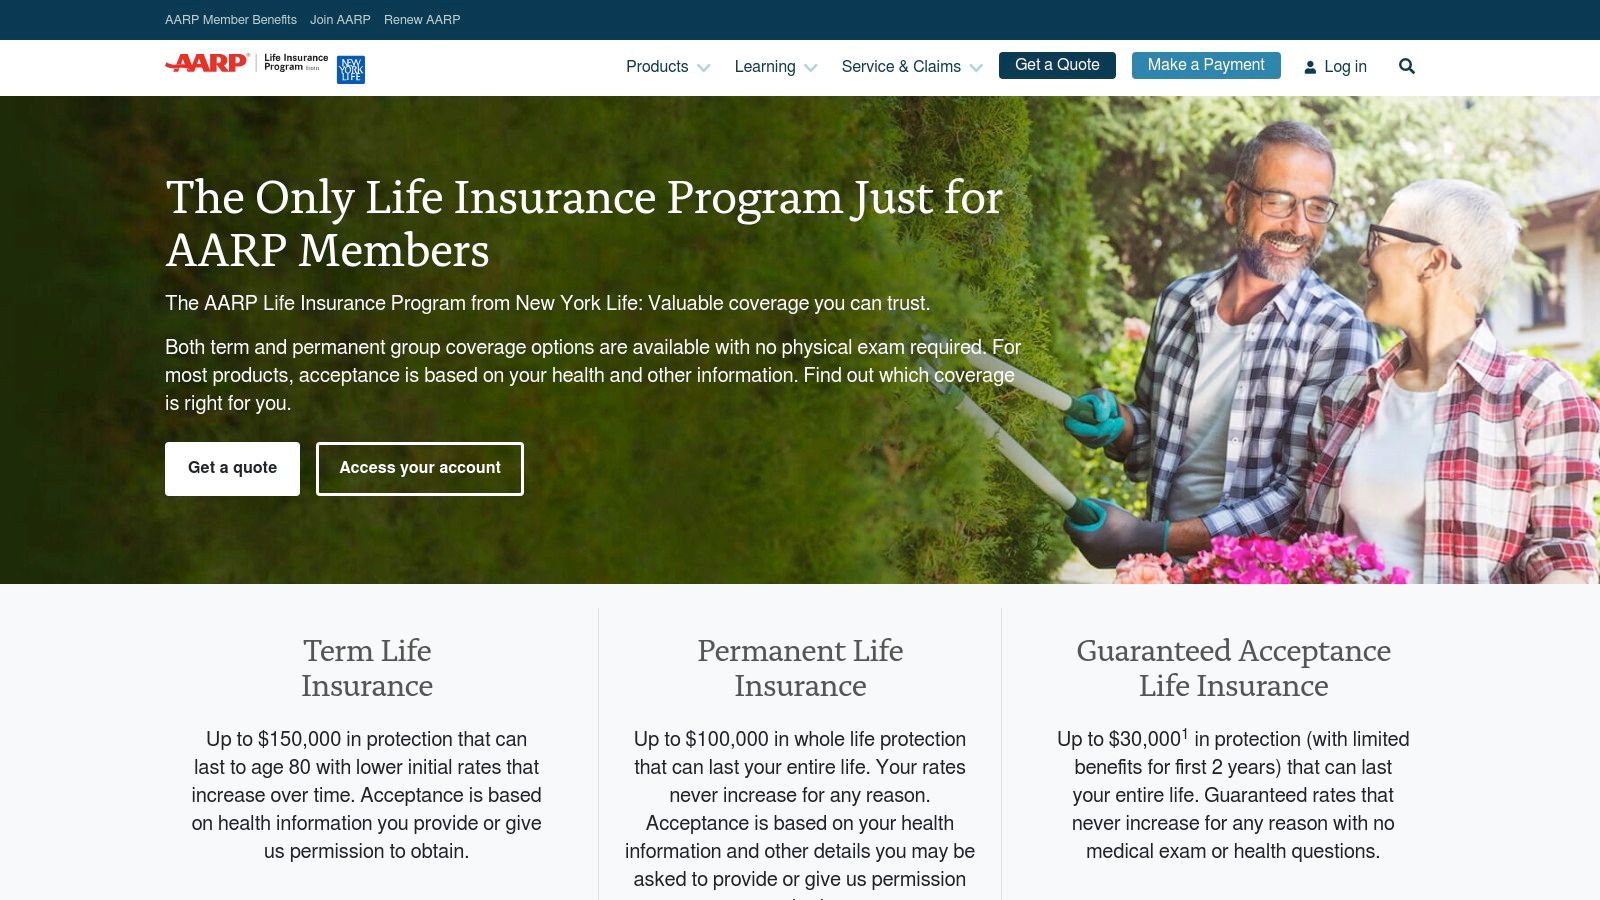
AARP life insurance monthly premiums, underwritten by New York Life, are determined primarily by the specific policy type, the coverage amount selected, and the applicant's age at the time of enrollment. While Term Life premiums increase every five years as you enter new age brackets, Permanent and Guaranteed Acceptance plans offer level premiums that remain fixed for the duration of the policy.
The AARP Life Insurance Program, specifically tailored for members aged 50 and older, remains one of the most recognized senior-focused financial products in 2026. Because these policies are underwritten by the New York Life Insurance Company, they carry significant financial backing, yet the structure of the premiums can be complex for those unfamiliar with "age-banded" pricing. Understanding how these monthly costs are calculated—and how they change over time—is essential for long-term financial planning and ensuring that your beneficiaries are protected without straining your monthly budget.
The Relationship Between AARP and New York Life
It is a common misconception that AARP is an insurance company. In reality, AARP acts as a massive group policyholder that negotiates terms and provides a platform for its members. The actual insurance is provided by New York Life Insurance Company, a firm with a long-standing reputation for financial stability and high ratings from agencies like A.M. Best and Fitch.
When you evaluate AARP life insurance monthly premiums, you are looking at rates negotiated specifically for the AARP membership base. These rates often feature "simplified issue" underwriting, meaning many applicants do not have to undergo a physical medical examination. Instead, they answer a few health-related questions. While this convenience is a major selling point, it also influences the premium structure, as the insurance company assumes a slightly higher risk than they would with a fully medically underwritten policy.
Breakdown of AARP Life Insurance Plan Types and Costs
To understand what you will pay each month, you must first identify which of the three primary AARP products fits your needs. Each has a distinct pricing philosophy and premium trajectory.
1. AARP Level Benefit Term Life Insurance
The Term Life plan is designed for individuals who need high coverage amounts for a specific period—typically until they reach age 80. In 2026, coverage amounts for this plan generally range from $10,000 to $150,000.
- Premium Structure: This plan uses "stepped" or "age-banded" premiums. Your monthly cost is not fixed for life. Instead, it is set based on your current five-year age bracket (e.g., 55–59, 60–64).
- The Cost Increase: Every time you enter a new five-year age bracket, your monthly premium increases. For many seniors, this can lead to a "price shock" in their 70s, where the premium may double or triple compared to what they paid in their 50s.
- Termination: It is important to note that AARP Term Life coverage typically ends once the insured individual reaches age 80, regardless of how much has been paid in premiums over the years.
2. AARP Permanent Life Insurance (Whole Life)
Unlike term insurance, Permanent Life insurance is designed to last your entire life, provided the premiums are paid. It also builds a small amount of cash value over time.
- Premium Structure: These are "level premiums." Once you are accepted into the plan, your monthly premium is locked in for life. It will never increase, regardless of your health or age.
- Coverage Limits: Because the risk to the insurer is higher (as a payout is guaranteed eventually), coverage amounts are lower, usually topping out at $50,000.
- Value Proposition: While the monthly cost per thousand dollars of coverage is higher than Term Life initially, the predictability of the fixed premium makes it a popular choice for those on fixed incomes who want to cover final expenses or small debts.
3. AARP Guaranteed Acceptance Life Insurance
This plan is designed for AARP members who may have significant health issues that disqualify them from other policies. There are no health questions and no medical exams.
- Premium Structure: Like the Permanent Life plan, these premiums are level and fixed for life.
- The Two-Year Rule: Because there is no medical screening, these policies feature a "graded death benefit." If the insured dies of natural causes within the first two years of the policy, the beneficiaries typically receive only the premiums paid plus a small percentage of interest (usually 10%). After two years, the full face value is payable.
- Monthly Cost: This is generally the most expensive way to buy life insurance on a per-dollar basis because the insurer is taking on the highest level of risk.
Estimated Monthly Premium Comparison (2026 Rates)
The following table provides a generalized estimate of monthly premiums for non-smokers to illustrate how age and plan type impact cost. Note: Actual rates depend on specific state regulations and individual health questions where applicable.
| Age at Issue | Plan Type | $10,000 Coverage | $25,000 Coverage | $50,000 Coverage |
|---|---|---|---|---|
| 55 | Term Life | $12.00 | $24.00 | $44.00 |
| 55 | Permanent (Whole) | $32.00 | $76.00 | $148.00 |
| 65 | Term Life | $26.00 | $58.00 | $112.00 |
| 65 | Permanent (Whole) | $54.00 | $130.00 | $255.00 |
| 75 | Term Life | $72.00 | $175.00 | $340.00 |
| 75 | Guaranteed Acceptance | $78.00 | $190.00 | N/A (Max $25k) |
These figures are illustrative of 2026 market trends and should be verified via a direct quote from the AARP Life Insurance Program site.
Factors That Influence Your Monthly Rate
Several variables beyond your age will determine exactly what New York Life charges you each month.
Tobacco Usage
AARP policies generally distinguish between tobacco users and non-tobacco users. In 2026, tobacco users can expect to pay significantly higher premiums—sometimes 30% to 50% more than non-smokers. To qualify for non-tobacco rates, you typically must have been tobacco-free for at least the past 12 to 24 months.
Gender
In most states, gender plays a role in life insurance pricing because women statistically have a longer life expectancy than men. Consequently, women often see slightly lower monthly premiums for the same amount of coverage compared to men of the same age.
State of Residence
Insurance is regulated at the state level. While AARP tries to keep pricing consistent nationwide, certain states have different requirements for "incontestability" periods or premium reserve requirements, which can cause minor fluctuations in the base monthly rate.
AARP Membership Status
You must be an active AARP member to apply for and maintain these specific policies. While the membership fee (currently around $16 per year in 2026) is separate from your insurance premium, it is a mandatory "cost of entry" that should be factored into your overall financial commitment.
The Pros and Cons of the AARP Premium Structure
Choosing an AARP plan requires balancing the ease of enrollment against the long-term cost.
Advantages:
- No Medical Exams: For many, the ability to skip a blood draw or physical is worth a slightly higher premium.
- Brand Trust: The partnership with New York Life provides peace of mind that the company will be able to pay out claims decades from now.
- Acceptance: Guaranteed acceptance plans ensure that even those with chronic illnesses can find some level of coverage.
Disadvantages:
- The Term Jump: The 5-year age bands can make Term Life unaffordable exactly when a senior might need it most (in their late 70s).
- Coverage Caps: With a maximum of $150,000 for term and $50,000 for permanent, these plans are not suitable for those looking to leave a massive inheritance or cover a large mortgage.
- Price: For a healthy individual willing to undergo a medical exam, "fully underwritten" policies from other carriers are almost always cheaper than AARP's simplified issue rates.
How to Manage Your Monthly Payments
In 2026, New York Life offers several ways to handle AARP life insurance monthly premiums to ensure policies do not lapse.
- Automatic Bank Draft (EFT): This is the most recommended method. It ensures that the premium is paid on time every month, preventing an accidental lapse in coverage which could be devastating if your health has declined since you first took out the policy.
- Credit Card Payments: Most major cards are accepted. This can be a way to earn rewards, though you must ensure the card's expiration date is updated in the system.
- Annual vs. Monthly: While this guide focuses on monthly premiums, paying annually often results in a small discount, as it reduces the administrative burden on the insurer.
If a payment is missed, AARP policies typically have a 31-day grace period. During this month, the coverage remains active. If the premium is not paid by the end of the grace period, the policy will lapse. For Permanent Life policies, there may be "non-forfeiture" options where the accumulated cash value is used to pay the premium, but this should not be relied upon as a primary strategy.
Common Mistakes to Avoid
When evaluating these premiums, many seniors fall into predictable traps. One major error is purchasing a Term Life policy for final expenses. Because the premiums increase every five years and the policy expires at age 80, a senior who lives to 85 will have paid thousands in premiums only to have the coverage vanish before it is needed. For final expenses, a Permanent Life policy with a fixed premium is generally the more appropriate choice, even if the initial monthly cost is higher.
Another mistake is failing to shop around. If you are in excellent health, you should get a quote for a medically underwritten policy from a broker. You may find that you can get double the coverage for the same monthly premium that AARP charges for their simplified issue product.
Frequently Asked Questions
Do AARP life insurance premiums increase every year?
No, premiums do not increase every year. For Term Life policies, premiums increase every five years as you move into a new age bracket (e.g., at age 60, 65, 70, and 75). For Permanent and Guaranteed Acceptance policies, the monthly premium stays exactly the same for as long as you own the policy.
Can New York Life cancel my AARP policy if my health declines?
No. As long as you continue to pay your monthly premiums on time and remain an AARP member, the insurance company cannot cancel your coverage due to changes in your health. This is known as "guaranteed renewability."
Is there a waiting period before the coverage begins?
For Term and Permanent (Whole) Life plans, coverage typically begins as soon as your first premium is processed and your application is approved. For Guaranteed Acceptance plans, there is a two-year "graded death benefit" period for natural deaths, though accidental deaths are usually covered from day one.
What happens to my premiums if I cancel my AARP membership?
To keep an AARP life insurance policy, you must maintain your AARP membership. If you allow your membership to lapse, New York Life may notify you that your insurance coverage is at risk of termination. It is vital to keep your $16/year membership active to protect your insurance investment.
Are the monthly premiums tax-deductible?
Generally, life insurance premiums paid by individuals are considered a personal expense and are not tax-deductible. However, the death benefit paid to your beneficiaries is typically free from federal income tax. You should consult with a tax professional regarding your specific 2026 tax situation.
Can I lower my monthly premium by reducing my coverage later?
Yes, in most cases, AARP allows you to reduce your face amount (the death benefit) to lower your monthly premium. However, you cannot usually increase your coverage without going through a new application process, which would be priced at your current (older) age.
Practical Recommendation
Before committing to an AARP life insurance policy in 2026, perform a "Five-Year Forecast." If you are considering the Term Life plan, look at what your premium will be in the next two age brackets. If the cost at age 70 or 75 looks unsustainable for your retirement budget, you are better off selecting a lower coverage amount in a Permanent Life plan now to lock in a fixed, level premium. Always prioritize a payment amount that you are certain you can maintain even if inflation affects your other living expenses.