Attleboro, Massachusetts drivers face a distinct auto insurance landscape shaped by state-mandated coverage minimums, local traffic density, regional claim frequencies, and individual driver profiles. Understanding the core elements influencing attleboro mass auto insurance costs helps motorists evaluate their policies, compare regional benchmarks against statewide averages, and implement practical strategies to secure competitive rates while maintaining necessary protection.
The Regulatory Framework of Massachusetts Auto Insurance
Massachusetts operates under a managed competition system for auto insurance, which differs significantly from states with purely open-market pricing or state-fixed rates. Under this regulatory model, insurance companies set their own rates independently, but those rates must be filed and approved by the Massachusetts Division of Insurance (DOI). This system is designed to foster price competition among carriers while protecting consumers from excessive, inadequate, or unfairly discriminatory pricing.
Furthermore, Massachusetts is a mandatory no-fault state. This designation impacts how claims are handled after an accident, regardless of who caused the collision. Under Personal Injury Protection (PIP), a driver's own insurance company pays for medical expenses, lost wages, and replacement services up to policy limits for the driver and their passengers, up to the statutory minimum of $8,000. Because of this structure, the legal framework itself exerts a baseline influence on attleboro mass auto insurance costs, ensuring that every legal vehicle on the road carries standardized core coverages.
Mandatory Coverages Required by Massachusetts Law
Every vehicle registered in Massachusetts must maintain four mandatory types of coverage. Failing to maintain these coverages results in severe penalties, including license suspension and fines. These mandatory components form the baseline of any policy pricing quote received by Attleboro residents:
- Bodily Injury to Others: This covers injuries to other people caused by your vehicle, but only when you are driving in Massachusetts. The statutory minimum is $20,000 per person and $40,000 per accident.
- Personal Injury Protection (PIP): As noted, PIP covers medical expenses, lost wages, and replacement services up to $8,000 for you, household members, and passengers, regardless of fault. Drivers can opt for a deductible ranging from $0 to $8,000 to lower their premium.
- Bodily Injury Caused by an Uninsured Auto: This protects you and your passengers if you are injured in an accident caused by an uninsured motorist or a hit-and-run driver. The minimum required limit is $20,000 per person and $40,000 per accident.
- Damage to Someone Else’s Property: Also known as property damage liability, this pays for damage your car causes to someone else’s property, such as another vehicle, a fence, or a building. The statutory minimum limit is $5,000 per accident.
Core Factors Influencing Attleboro Auto Insurance Rates
When insurance companies calculate premiums for residents in Attleboro, Bristol County, they evaluate a complex matrix of risk variables. While statewide trends matter, hyper-local factors specific to Attleboro play a major role in determining whether a driver pays above or below the Massachusetts average.
Geographic and Zip Code Risk Assessment
Insurance carriers analyze historical claims data down to the specific zip code. Attleboro sits in Bristol County, sharing borders with Rhode Island and acting as a commuter corridor via Interstate 95, Interstate 295, and U.S. Route 1.
- Traffic Density and Commuter Patterns: Heavy commuter traffic passing through Attleboro toward Providence, Rhode Island, or Boston increases the statistical probability of fender-benders and multi-car collisions.
- Weather-Related Claims: New England winters bring heavy snowfall, ice storms, and freezing rain, leading to a seasonal spike in slip-and-slide accidents, rear-end collisions, and property damage claims.
- Comprehensive Risk: Rates also account for local rates of vehicle theft, vandalism, and animal strikes (such as deer common in suburban-rural fringe areas of Bristol County).
Driver-Specific Rating Variables
Beyond geography, insurers look closely at the individual behind the wheel. In Massachusetts, the Merit Rating Board (MRB) maintains the Safe Driver Insurance Plan (SDIP), which tracks driving history statewide.
- Driving Record and SDIP Step: Massachusetts uses a 35-step rating system. New drivers typically start at Step 15. Clean driving records reward motorists by moving them down into lower steps, resulting in premium discounts, while at-fault accidents and major traffic violations move drivers up into surcharge steps that increase attleboro mass auto insurance costs.
- Driver Experience and Age: Inexperience correlates with higher risk. Teenagers and drivers under the age of 25 face significantly higher premiums due to statistical crash probabilities.
- Vehicle Make, Model, and Safety Features: The cost to repair or replace a vehicle directly influences collision and comprehensive premiums. Vehicles equipped with advanced driver-assistance systems (ADAS), anti-lock brakes, and high crash-test ratings from the Insurance Institute for Highway Safety (IIHS) often qualify for specific discounts.
- Annual Mileage and Vehicle Use: Commuting long distances to work or school increases exposure risk compared to vehicles driven strictly for pleasure or low-mileage recreational use.
Optional Coverages Worth Considering
While mandatory coverages keep a vehicle legal, they often leave significant financial exposure in the event of a severe accident or total loss. Attleboro drivers frequently supplement their policies with optional coverages to ensure robust financial protection.
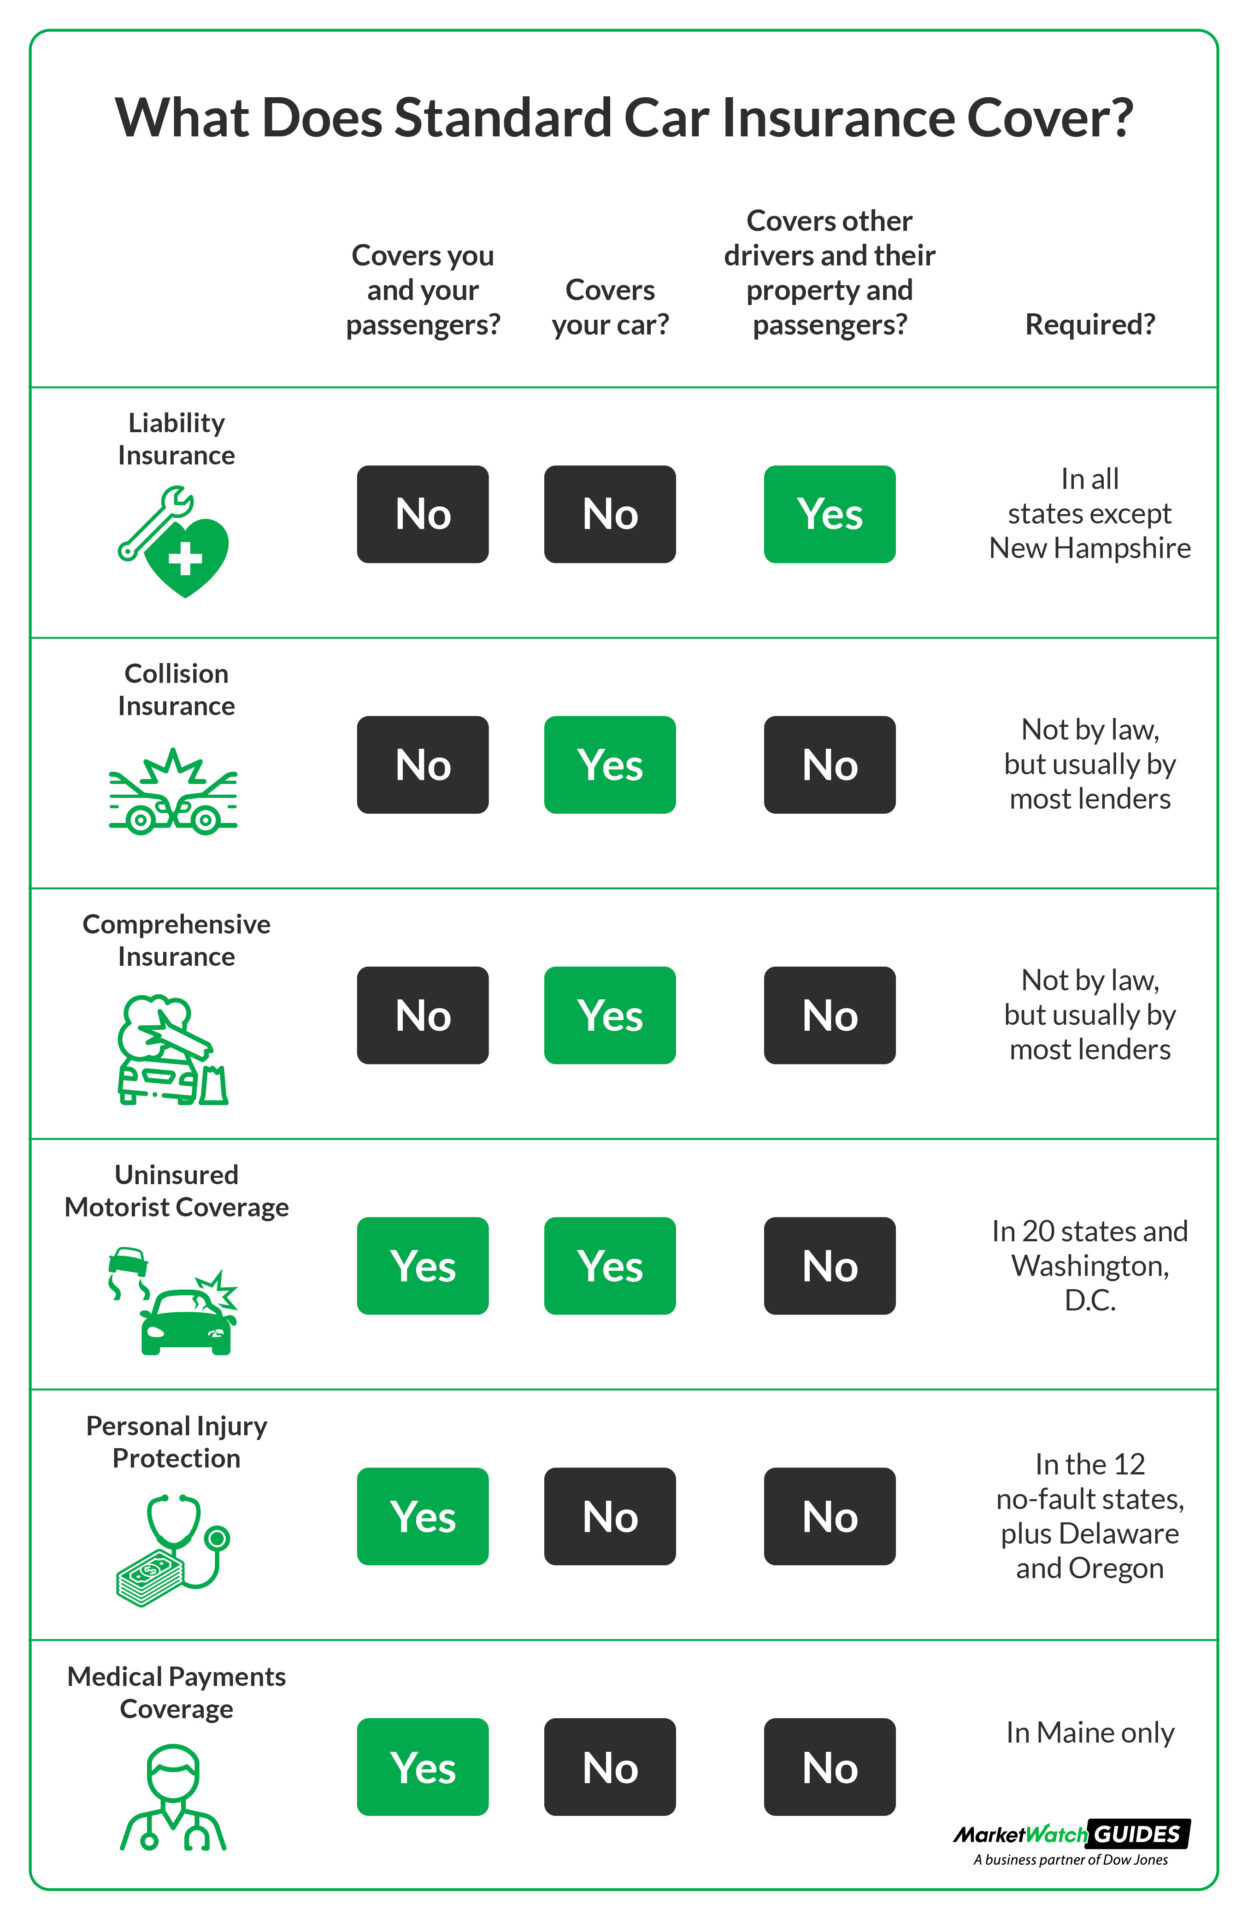
- Collision Coverage: Pays for damage to your car when it hits another car or object, such as a tree or guardrail, regardless of fault.
- Comprehensive Coverage: Protects against damage to your car caused by events other than collisions, including theft, fire, windshield cracks from road debris, vandalism, flood, or animal strikes.
- Medical Payments (MedPay): Supplements PIP by paying for medical and funeral expenses for you and your passengers, regardless of fault, and covers medical bills that exceed your PIP limit or health insurance deductible.
- Substitute Transportation / Rental Car Coverage: Pays for a rental car while your vehicle is being repaired following a covered claim.
- Roadside Assistance: Covers towing, flat tire changes, and emergency fuel delivery.
Comparing Insurance Options in Attleboro, MA
Navigating the marketplace requires understanding how different types of insurance providers operate within the Commonwealth. Consumers generally choose between direct writers, captive agents, and independent insurance agencies.
| Insurance Provider Type | Description | Pros for Attleboro Drivers | Cons |
|---|---|---|---|
| Direct Writers | Companies that sell policies directly to consumers online or via phone without local agents. | Often streamlined digital interfaces; potential savings on middleman fees. | Less personalized local advice regarding specific Bristol County road risks. |
| Captive Agents | Agents who represent only one insurance company (e.g., State Farm, Allstate). | Deep expertise in their specific company's products and discount structures. | Limited to quoting prices from a single carrier. |
| Independent Agencies | Local agencies in or near Attleboro that represent multiple insurance carriers. | Can compare rates across dozens of top-rated insurers simultaneously; localized advocacy. | Service quality and carrier options vary by agency. |
Proven Strategies to Lower Attleboro Mass Auto Insurance Costs
Drivers looking to optimize their monthly or annual expenditures can utilize several effective, legitimate strategies to reduce their premiums without sacrificing necessary coverage levels.
Adjusting Deductibles and Coverage Limits
Raising comprehensive and collision deductibles from $500 to $1,000 immediately lowers the cost of physical damage coverage. However, drivers must ensure they have sufficient emergency savings to cover the higher out-of-pocket expense if a claim occurs. Additionally, for older vehicles whose market value is low, dropping collision and comprehensive coverage entirely can yield substantial savings.
Maximizing Available Discounts
Massachusetts insurers offer a wide array of discounts that drivers can stack to reduce attleboro mass auto insurance costs. Common discounts include:
- Bundling Discounts: Purchasing home, renters, or condo insurance through the same carrier that insures your vehicle.
- Paperless and Automatic Payment Discounts: Enrolling in electronic document delivery and recurring ACH withdrawals.
- Anti-Theft Device Discounts: Installing certified alarms, tracking systems, or steering wheel locks.
- Good Student Discounts: Maintaining a B average or higher for high school and college drivers.
- Low Mileage Discounts: Verifying low annual vehicle utilization.
Maintaining a Clean Driving Record
Because Massachusetts utilizes the Safe Driver Insurance Plan, avoiding speeding tickets, surchargeable accidents, and moving violations is the single most effective long-term method for keeping insurance costs low. Surcharges typically remain on a driving record for six years, impacting rates over an extended period.
Frequently Asked Questions
How do Attleboro insurance rates compare to the rest of Massachusetts?
Attleboro auto insurance rates generally align close to or slightly below major urban centers like Boston or Worcester, but may be higher than rural towns in Western Massachusetts. Proximity to the Rhode Island border and heavily traveled regional commuting routes contribute to moderate-to-high risk indexing compared to quieter suburban municipalities.
Is it mandatory to have collision coverage in Massachusetts?
No, collision coverage is not required by Massachusetts state law. However, if you are financing or leasing your vehicle, your lender or leasing company will almost universally require you to carry both collision and comprehensive coverage with specified deductible limits until the loan is paid off.
What should I do if my insurance rates increase unexpectedly?
Insurance companies periodically adjust baseline rates across entire zip codes or rating tiers due to inflation, rising vehicle repair costs, and regional claims data. If your rates increase without a moving violation or at-fault accident on your record, contact your independent agent or broker to re-shop your policy across multiple competing carriers.
How does moving from Rhode Island to Attleboro affect my car insurance?
Moving across state lines requires you to register your vehicle with the Massachusetts Registry of Motor Vehicles (RMV) and secure a Massachusetts auto insurance policy within statutory timeframes. Because insurance regulations, minimum coverage limits, and rating systems differ between Rhode Island and Massachusetts, your premium will be recalculated based entirely on Massachusetts rating criteria.
Can my credit score affect my auto insurance premium in Massachusetts?
Unlike many other states where insurers heavily weight credit-based insurance scores, Massachusetts has stringent regulations regarding the use of credit history in rating auto insurance. Insurers are restricted in how they can use credit information, ensuring that driving record and risk factors play a more dominant role in pricing.
Next Steps for Attleboro Drivers
To secure the most competitive rate for your specific situation, gather your current policy declarations page, your vehicle identification number (VIN), and your driving history details. Reach out to local independent insurance agents in the Attleboro area or utilize online comparison tools to evaluate quotes from multiple carriers licensed by the Massachusetts Division of Insurance. Review your coverage limits annually to ensure your protection matches your current financial needs.