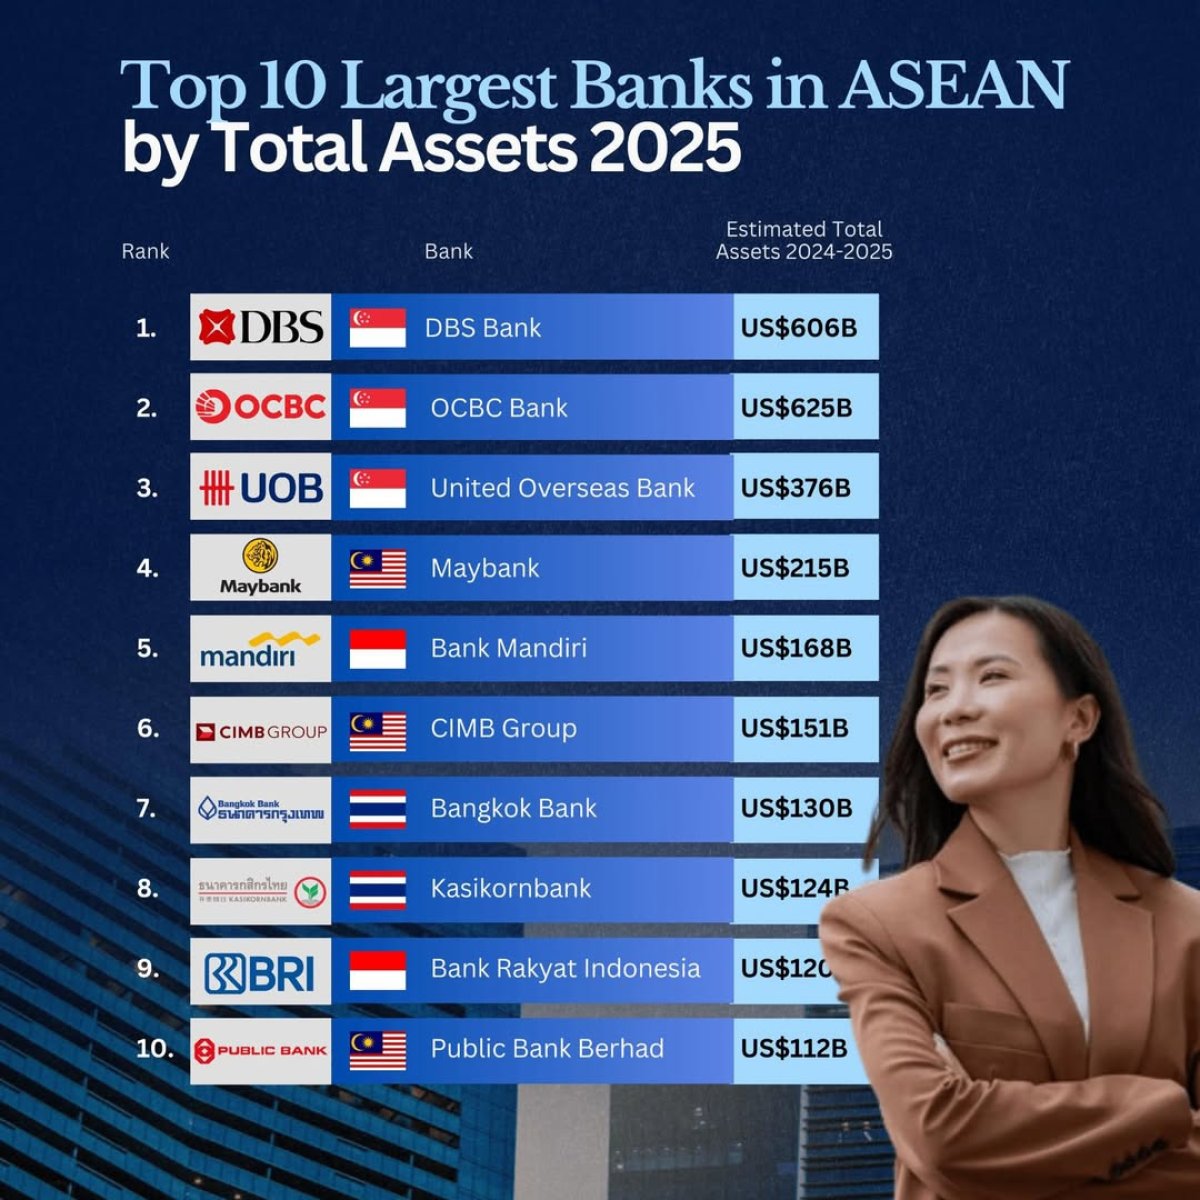
Contrary to common misconceptions, a bank's assets are not a direct measure of its net worth. In accounting, a bank’s net worth—also known as equity—is the difference between its total assets and its total liabilities. While assets represent what the bank owns or is owed, net worth represents the actual value remaining for shareholders.
The statement that "a bank's assets are a measure of the bank's net worth" is a frequent point of confusion for those new to finance. To understand why this is technically inaccurate, one must look at the fundamental structure of a bank’s balance sheet. In the world of banking, the relationship between assets, liabilities, and equity is governed by the accounting identity: Assets = Liabilities + Shareholders' Equity.
In this equation, net worth is synonymous with "Shareholders' Equity." Therefore, assets are only one component used to calculate net worth; they do not represent net worth on their own. For a bank, the vast majority of its assets are funded by liabilities (such as customer deposits), meaning a bank can have trillions of dollars in assets but a relatively small net worth.
The Fundamental Accounting Equation in Banking
To grasp the distinction between assets and net worth, we must first define the three pillars of the bank's balance sheet as they stand in 2026. Banking is unique because what an individual considers an asset, a bank often considers a liability, and vice versa.
Defining Bank Assets
For most businesses, assets are physical items like machinery or inventory. For a bank, assets are primarily financial contracts. As of 2026, the primary categories of bank assets include:
- Loans and Leases: This is usually the largest category. When a bank gives you a mortgage, a car loan, or a business credit line, that contract is an asset for the bank because it represents a legal claim to future interest and principal payments.
- Investment Securities: Banks hold government bonds (like U.S. Treasuries), municipal bonds, and mortgage-backed securities. These provide liquidity and interest income.
- Cash and Balances due from Depository Institutions: This includes physical currency in vaults and electronic balances held at the Federal Reserve or other central banks.
- Trading Assets: For large investment banks, this includes derivatives and securities held for the purpose of short-term trading.
Defining Bank Liabilities
Liabilities are what the bank owes to others. This is where the "net" in "net worth" becomes significant.
- Customer Deposits: This is the bank's primary liability. When you "put money in the bank," the bank is actually borrowing that money from you. They owe it back to you on demand or at a set date.
- Short-term and Long-term Borrowings: Banks often borrow from other banks or issue corporate bonds to raise capital.
- Accrued Expenses: Unpaid interest to depositors or taxes owed to the government.
Calculating Net Worth (Equity)
Net worth is the "cushion" that remains. If a bank were to sell all its assets today and pay off all its liabilities, the remaining cash would be the net worth. In 2026 regulatory environments, this is often referred to as Bank Capital. It is the owners' stake in the business and serves as the primary defense against insolvency.
Why Assets Alone Are a Misleading Metric of Health
If you only look at a bank’s total assets, you are looking at the size of the institution, not necessarily its strength or its value to shareholders. A bank with $1 trillion in assets and $990 billion in liabilities has a net worth of only $10 billion. Conversely, a smaller bank with $100 billion in assets and $80 billion in liabilities has a net worth of $20 billion. In this scenario, the smaller bank is actually "worth" more in terms of equity and has a much higher capital-to-asset ratio.
The Role of Leverage
Banking is a highly leveraged industry. Leverage refers to the use of borrowed money (liabilities) to acquire assets. Because banks operate on thin margins, they use high leverage to generate acceptable returns on equity. However, high leverage means that even a small percentage drop in the value of assets can completely wipe out the bank's net worth.
For example, if a bank has $100 in assets and $90 in liabilities, its net worth is $10. If the value of its assets drops by just 10% (to $90), its net worth becomes zero. This is why regulators in 2026 focus so heavily on capital requirements rather than just asset growth.
Net Worth as "Bank Capital" and Regulatory Frameworks
In the professional banking sector, net worth is discussed through the lens of Regulatory Capital. Under the current standards of 2026, which incorporate the final stages of the Basel III (and moving toward Basel IV) framework, regulators do not just care about total assets; they care about Risk-Weighted Assets (RWA).
Tier 1 and Tier 2 Capital
To ensure banks have enough net worth to survive economic shocks, capital is divided into "Tiers":
- Tier 1 Capital: This is the core measure of a bank's financial strength from a regulator's point of view. It consists primarily of common stock and retained earnings (the most "permanent" forms of net worth).
- Tier 2 Capital: This includes "supplementary" capital, such as subordinated debt and certain types of loan loss reserves. It is considered less reliable than Tier 1.
The Common Equity Tier 1 (CET1) Ratio is the most watched metric in 2026. It compares a bank's core net worth against its risk-weighted assets. If a bank’s assets are primarily "safe" (like cash or AAA-rated government bonds), the risk-weighting is low, and the bank needs less net worth to be considered stable. If the assets are "risky" (like unsecured personal loans), the bank must hold a much higher net worth to offset that risk.
| Category | Typical Items | Purpose on Balance Sheet | Relationship to Net Worth |
|---|---|---|---|
| Assets | Mortgages, Commercial Loans, Treasury Bonds, Cash | Generate interest income and provide liquidity | Adds to total value; base for calculations |
| Liabilities | Savings Accounts, CDs, Interbank Borrowing | Source of funds for lending | Subtracts from total value to find net worth |
| Equity (Net Worth) | Common Stock, Retained Earnings | Absorbs losses and protects depositors | The "Net" value or ownership interest |
How Asset Quality Impacts Net Worth
While the quantity of assets does not measure net worth, the quality of assets determines the future of net worth. This is a critical distinction for investors and auditors in 2026.
Non-Performing Loans (NPLs) and Impairment
If a bank has $500 million in commercial real estate loans (assets), but the borrowers stop making payments, those assets are "impaired." Accounting rules require the bank to write down the value of these assets. When an asset's value is written down, the reduction comes directly out of the bank's net worth.
This creates a "death spiral" for banks with poor asset quality:
- Asset values drop due to defaults.
- The bank must recognize a loss.
- Net worth (Equity) decreases.
- Regulatory capital ratios fall below required levels.
- The bank is forced to sell more assets or raise expensive new equity to survive.
Provisioning for Loan Losses
In 2026, banks use sophisticated forward-looking models (such as the CECL—Current Expected Credit Losses—standard in the U.S.) to estimate future losses on their assets. These provisions are essentially "pre-deductions" from net worth. By setting aside reserves today for loans that might go bad tomorrow, banks attempt to stabilize their net worth against sudden shocks.
Common Misconceptions: Size vs. Strength
It is a common error in mainstream media to rank the "top banks" solely by asset size. While asset size indicates a bank's market reach and power, it says nothing about its solvency or its actual value to shareholders.
Why a "Large" Bank Isn't Always a "Strong" Bank
Consider a bank that has rapidly expanded its asset base by offering high-interest rates on deposits to attract cash, then lending that cash out to risky startups. On paper, its assets are growing fast. However, if the cost of its liabilities (the interest paid to depositors) is higher than the income from its assets, its net worth will eventually erode.
Furthermore, if the market perceives that the bank's assets are overvalued or that its liabilities are too volatile, the bank's Market Capitalization (the market's version of net worth) might be much lower than the "Book Value" of its equity. In 2026, we frequently see large global banks trading at a "Price-to-Book" ratio of less than 1.0, meaning the market believes the bank’s net worth is actually lower than what is stated on its balance sheet.
Practical Guidance for Evaluating a Bank's Financial Position
Whether you are an investor, a business owner choosing a banking partner, or a student of finance, you should look beyond the total asset figure. To find the "true" measure of a bank, follow these steps:
- Locate the Shareholders' Equity: This is found at the bottom of the balance sheet. This is the official "Net Worth."
- Check the CET1 Ratio: This tells you the net worth as a percentage of risk. In 2026, a healthy ratio is typically above 10-12%, depending on the jurisdiction.
- Analyze the Loan-to-Deposit Ratio: If a bank's assets (loans) significantly exceed its stable liabilities (deposits), it may be relying on "hot money" or expensive wholesale borrowing, which puts the net worth at risk during a liquidity crisis.
- Review the Net Interest Margin (NIM): This measures how efficiently the bank uses its assets to generate profit. Profitability is the primary way a bank grows its net worth organically.
Frequently Asked Questions
Does an increase in assets always lead to an increase in net worth?
No. An increase in assets only leads to an increase in net worth if those assets are acquired through retained earnings or the issuance of new stock. If a bank increases its assets by taking on more debt (liabilities), such as by taking in more deposits, the net worth remains unchanged because the new asset is perfectly offset by a new liability.
Can a bank have negative net worth?
Yes. If the value of a bank's assets falls below the total amount of its liabilities, the bank has negative net worth. This state is known as technical insolvency. In such cases, regulators usually step in to close or merge the bank because it no longer has a capital cushion to protect depositor funds.
Why do people get confused between assets and net worth?
The confusion often stems from how individuals view their own finances. People often say, "My house is my greatest asset," and they associate that asset with their wealth. However, they often forget that the mortgage (the liability) must be subtracted to find their personal net worth (home equity). In banking, this distinction is magnified because banks are specifically designed to hold massive liabilities to fund their assets.
Is the "Market Cap" of a bank the same as its net worth?
Not exactly. Net worth (Book Value) is an accounting measure based on the recorded value of assets and liabilities. Market Capitalization is the total value of the bank's shares as traded on the stock exchange. Market cap represents what investors think the bank is worth, including future growth potential and "off-balance-sheet" factors, whereas accounting net worth is based on historical costs and current valuations of recorded items.
How do interest rates in 2026 affect bank net worth?
Interest rates have a dual impact. Rising rates can increase the income a bank earns on its assets (loans), which boosts profits and net worth. However, rising rates also decrease the market value of existing fixed-rate bonds (assets) held by the bank. If the bank is forced to sell those bonds, it must recognize a loss, which reduces its net worth.
Final Recommendation: Focus on the "Net"
When analyzing the phrase "a bank's assets are a measure of the bank's net worth," it is vital to remember that assets are only the starting point. To understand a bank's true financial standing in 2026, one must always subtract the liabilities.
For a practical next action, if you are reviewing a bank’s performance, skip the "Total Assets" headline and go straight to the Statement of Changes in Equity. This document tracks how the bank's net worth has grown or shrunk over time, providing a much clearer picture of financial health than the gross asset size ever could. Always prioritize capital adequacy and asset quality over mere scale; in the volatile financial landscape of 2026, a well-capitalized medium-sized bank is often safer and more valuable than an over-leveraged giant.