Age UK provides access to over 50s life insurance products arranged through third-party providers, specifically designed to offer guaranteed acceptance for UK residents within a set age range. These policies generally function as whole-of-life plans intended to cover funeral costs or provide a small cash sum to beneficiaries, functioning without the need for medical examinations or lengthy health questionnaires.
The Role of Age UK in Life Insurance Provision
It is essential to clarify that Age UK Enterprises Ltd does not act as the insurer itself. Instead, it operates by arranging insurance products through reputable, FCA-regulated financial institutions. When you explore "Age UK over 50 life insurance," you are engaging with a service that has vetted providers to ensure the products meet the standards and needs typical of the over-50 demographic.
The primary function of these arrangements is to simplify the process of obtaining life cover for individuals who might otherwise be concerned about medical underwriting. Because these plans are "guaranteed acceptance," they remove the barrier of entry common in traditional life insurance, where pre-existing conditions or age-related health changes might lead to high premiums or outright rejection.
How Over 50s Guaranteed Acceptance Plans Work
The core mechanism of these insurance products is the "guaranteed acceptance" promise. If you fall within the specified age bracket—typically 50 to 85—your application is accepted regardless of your medical history. You will not be asked to undergo a medical exam, and there are no intrusive health checks.
Key Operational Characteristics
- Whole-of-Life Coverage: Unlike term life insurance, which only covers you for a set number of years, these policies are designed to last for the remainder of your life, provided the premiums are maintained.
- Fixed Premiums: In most cases, the premium you agree to pay at the start remains the same throughout the life of the policy. This provides predictability, as you will always know exactly how much the cover will cost you each month.
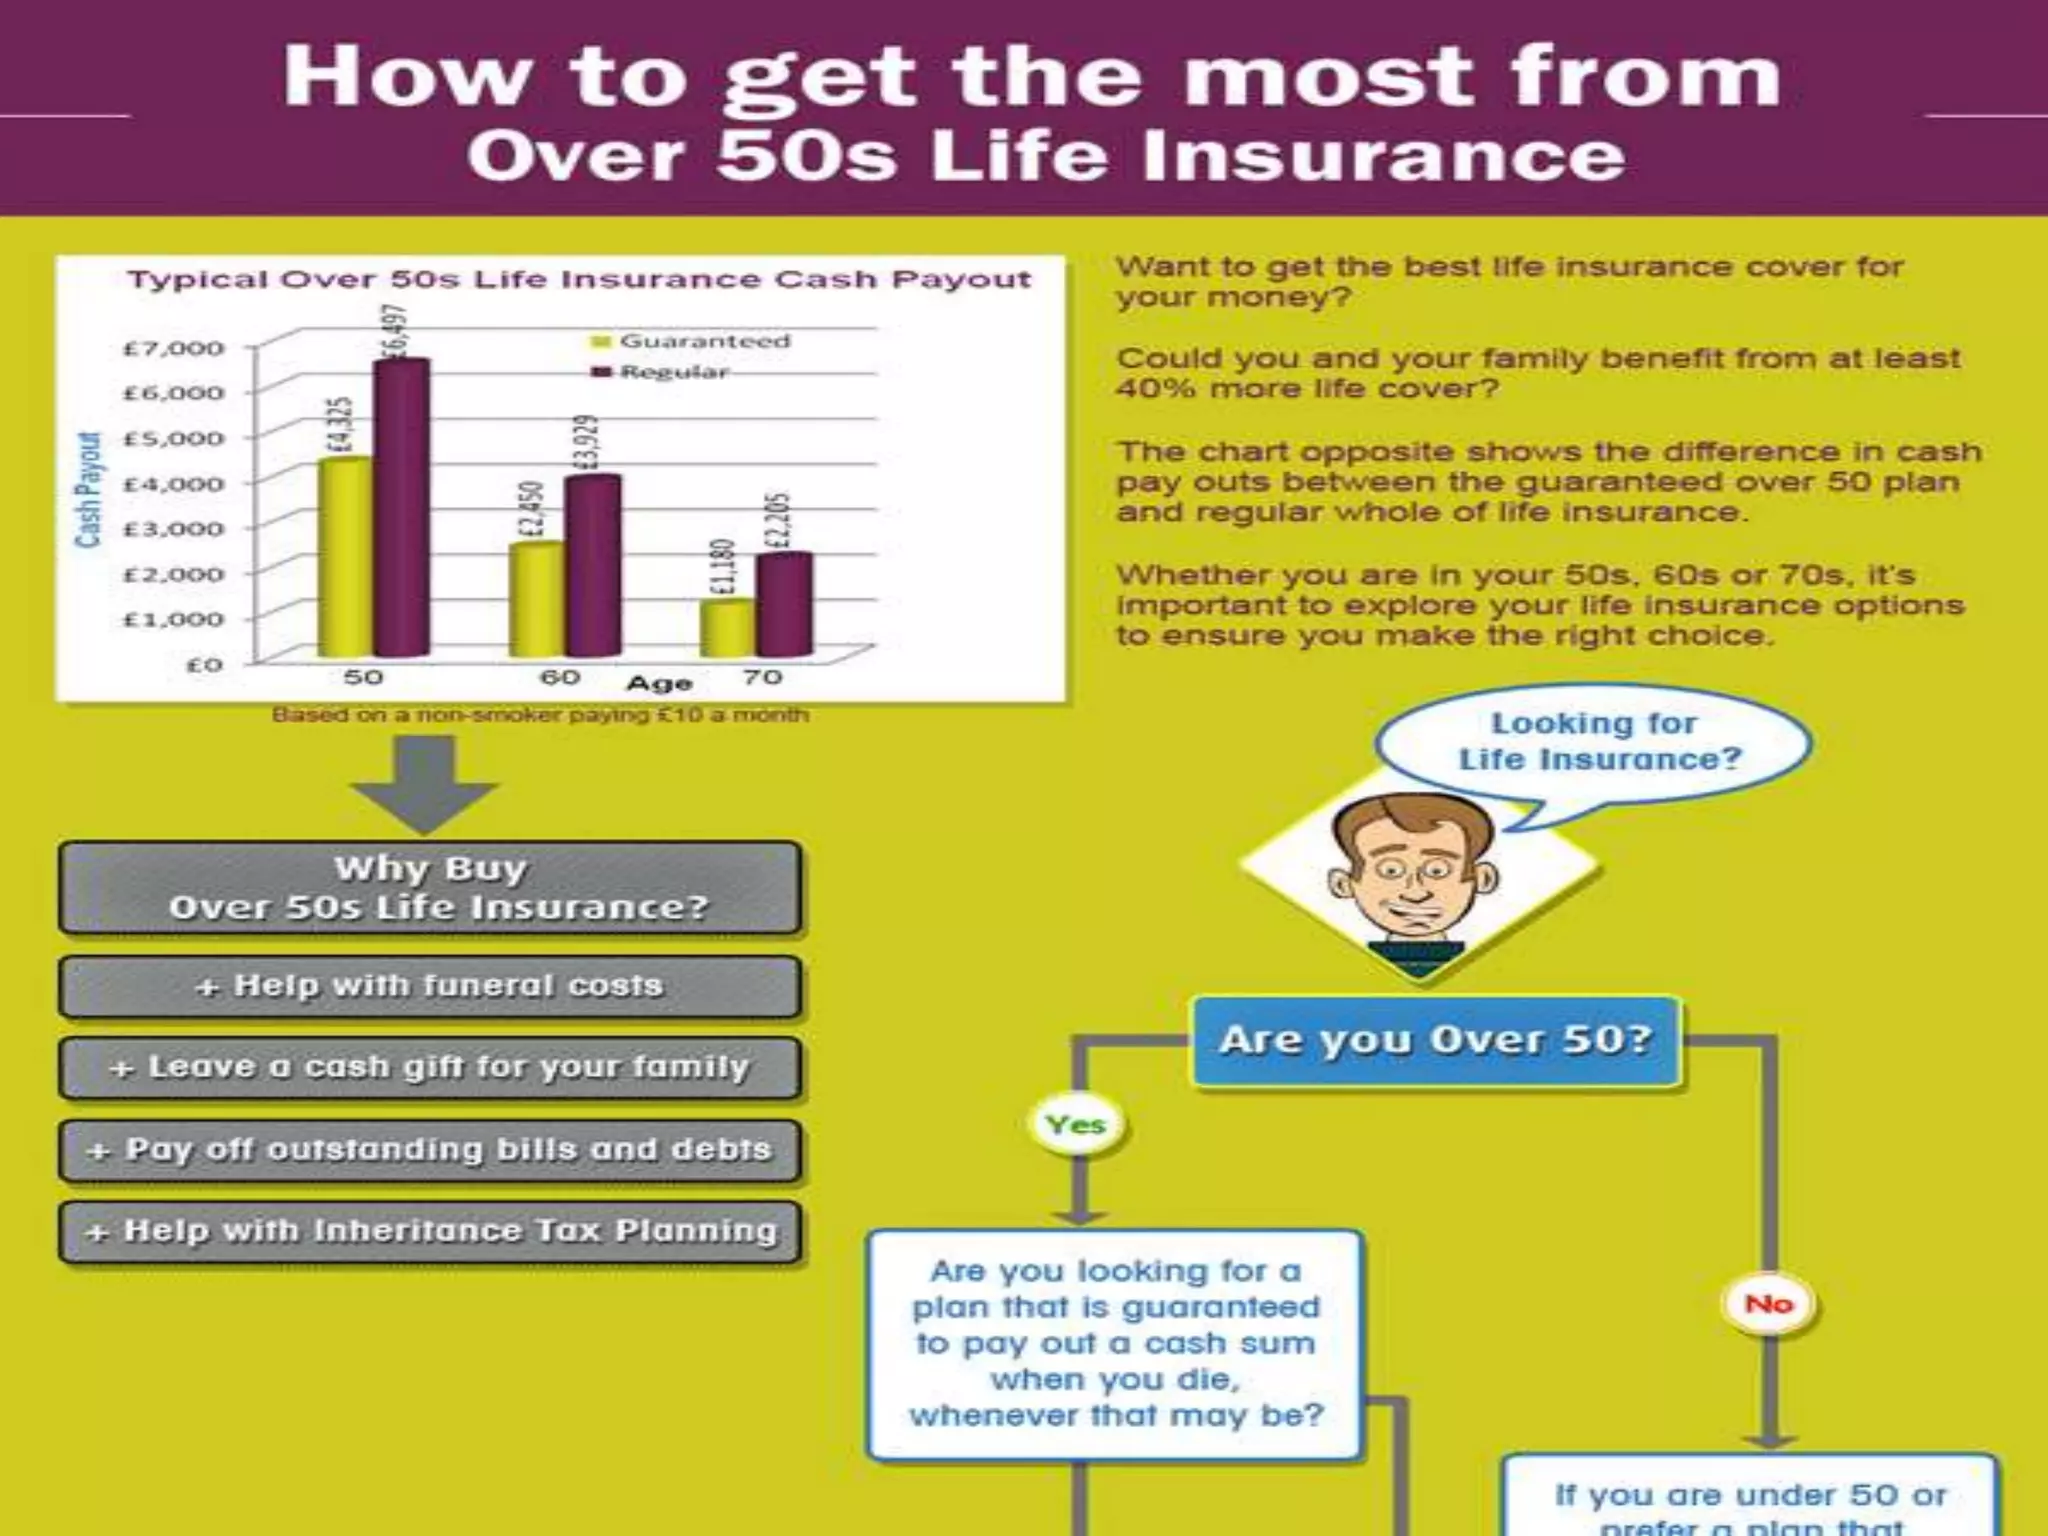
- Cash Benefit: Upon death, the policy pays out a lump sum to your nominated beneficiaries. Many policyholders specifically earmark these funds for funeral expenses, legal fees, or to provide a small inheritance.
Eligibility Requirements and Financial Constraints
While the "guaranteed" aspect simplifies entry, there are specific constraints that potential policyholders must understand before proceeding.
Age and Residency
To qualify for plans arranged through Age UK, you must be a UK resident. The age limits are strict; typically, you must be at least 50 but no older than 85 at the time of application. Ensuring you fall within these boundaries is the first step in the eligibility verification process.
The Impact of the Moratorium Period
Most over 50s life insurance policies include a "waiting period" or moratorium, usually lasting 12 to 24 months. If the policyholder passes away due to natural causes during this initial period, the provider typically does not pay the full death benefit. Instead, they will refund the premiums paid up to that point. It is crucial to note that this restriction usually does not apply to accidental death, where a full payout may occur from day one, depending on the specific policy terms.
Premium Duration
It is a common misconception that you pay for these policies only until a certain age. While some providers offer "capped" payment terms, many plans require you to pay premiums until you die. You must calculate whether the total premiums paid over time will eventually exceed the value of the lump sum payout. If you live a long life, you may end up paying more into the policy than your beneficiaries receive upon your passing.
Comparison: Over 50s Plans vs. Standard Life Insurance
Choosing between an over 50s plan and a standard, underwritten life insurance policy requires balancing the ease of access against the value of the benefit.
| Feature | Over 50s Guaranteed Plans | Standard Term Life Insurance |
|---|---|---|
| Medical Exam | Not required | Often required |
| Acceptance | Guaranteed within age limits | Based on health assessment |
| Cost | Fixed, usually higher per unit of cover | Variable, often lower if healthy |
| Duration | Whole-of-life | Fixed term (e.g., 20 years) |
| Payout Value | Lower lump sum | Higher potential payout |
The table above illustrates the trade-off. If you are in good health, a standard policy might provide a significantly larger death benefit for the same monthly premium. However, if you have health conditions that would make you "uninsurable" or significantly more expensive under standard underwriting, the over 50s product provides a reliable, guaranteed alternative.
Practical Steps to Application
When you decide to proceed with an application, follow these logical steps to ensure the policy meets your requirements:
- Assess Your Goal: Determine exactly why you need the insurance. Is it to cover specific funeral costs? If so, research current funeral prices to ensure the payout amount will be sufficient.
- Evaluate Affordability: Use the provider's quote tool to look at different premium levels. Ensure the monthly cost is sustainable for your long-term budget, as missing payments can lead to the policy being cancelled with no return of premiums.
- Review the Key Features Document: Every policy has a "Key Facts" or "Key Features" document. Read this in full before signing. It contains the essential details on the moratorium period, cancellation rights, and any circumstances under which the policy might not pay out.
- Nominate Beneficiaries: Make sure you understand how the payout will be handled. Using a trust can sometimes help keep the payout outside of your estate for inheritance tax purposes, though you should consult a financial advisor regarding your specific circumstances.
Common Pitfalls and Troubleshooting
Stopping Payments
A common error is assuming you can stop paying premiums once you retire. If your policy requires continuous payments, stopping will result in the loss of your cover. Always confirm if your plan has a "premium cessation" age—a point where you no longer need to pay but the cover continues.
Inflation Risk
Because the payout amount on many of these policies is fixed at the start, inflation can erode the "real" value of the sum over time. A payout that covers a funeral today may not cover the same services in 15 or 20 years. Consider whether your provider offers an "index-linked" option, though be aware this will increase your premiums over time.
Misunderstanding the Payout
Ensure that your family or executors are aware of the policy's existence. If they do not know the policy exists, they cannot claim the benefit. Keep your policy documents in a secure, accessible location and inform your beneficiaries about where to find them.
Frequently Asked Questions
Is medical advice required for Age UK over 50s life insurance?
No. One of the primary features of these plans is that they do not require medical examinations or health questionnaires, making them suitable for individuals who have pre-existing medical conditions.
What happens if I stop paying my premiums?
If you stop paying your premiums, your policy will generally be cancelled, and you will lose the cover. You will not receive any money back for the premiums you have already paid.
Can I get an over 50s plan if I have a serious illness?
Yes. Because these plans offer guaranteed acceptance within the specified age range, your health status—even if you have a terminal or serious illness—does not disqualify you from being accepted. However, remember the moratorium period for death by natural causes.
Are these payouts subject to tax?
Generally, the cash lump sum paid out upon death is not subject to income tax. However, depending on the size of your total estate, it could potentially be subject to inheritance tax. It is advisable to look into placing the policy into a trust to manage this.
What is the maximum age I can apply?
While terms vary by specific product, most over 50s plans arranged through Age UK services cater to applicants up to the age of 85. Always check the current product documentation for the precise upper age limit applicable in 2026.
Final Recommendation
Before committing to any over 50s life insurance policy, take the time to compare the total cost of premiums over your life expectancy against the guaranteed payout. If your health is generally good, seek professional financial advice to determine if a fully underwritten policy might offer better value. If your priority is a simple, guaranteed, and predictable way to cover end-of-life expenses without medical questions, ensure you have read the policy documentation thoroughly to fully understand the moratorium period and premium obligations.