The Elizabeth A. DiGeronimo 2011 Irrevocable Trust represents a specific legal arrangement designed to hold life insurance policies outside of a taxable estate. By transferring policy ownership to an irrevocable trust, the grantor aims to provide liquidity for estate expenses, taxes, or beneficiary distributions while ensuring the proceeds remain exempt from inclusion in the grantor’s gross estate for federal estate tax purposes.
The Purpose of Irrevocable Life Insurance Trusts (ILITs)
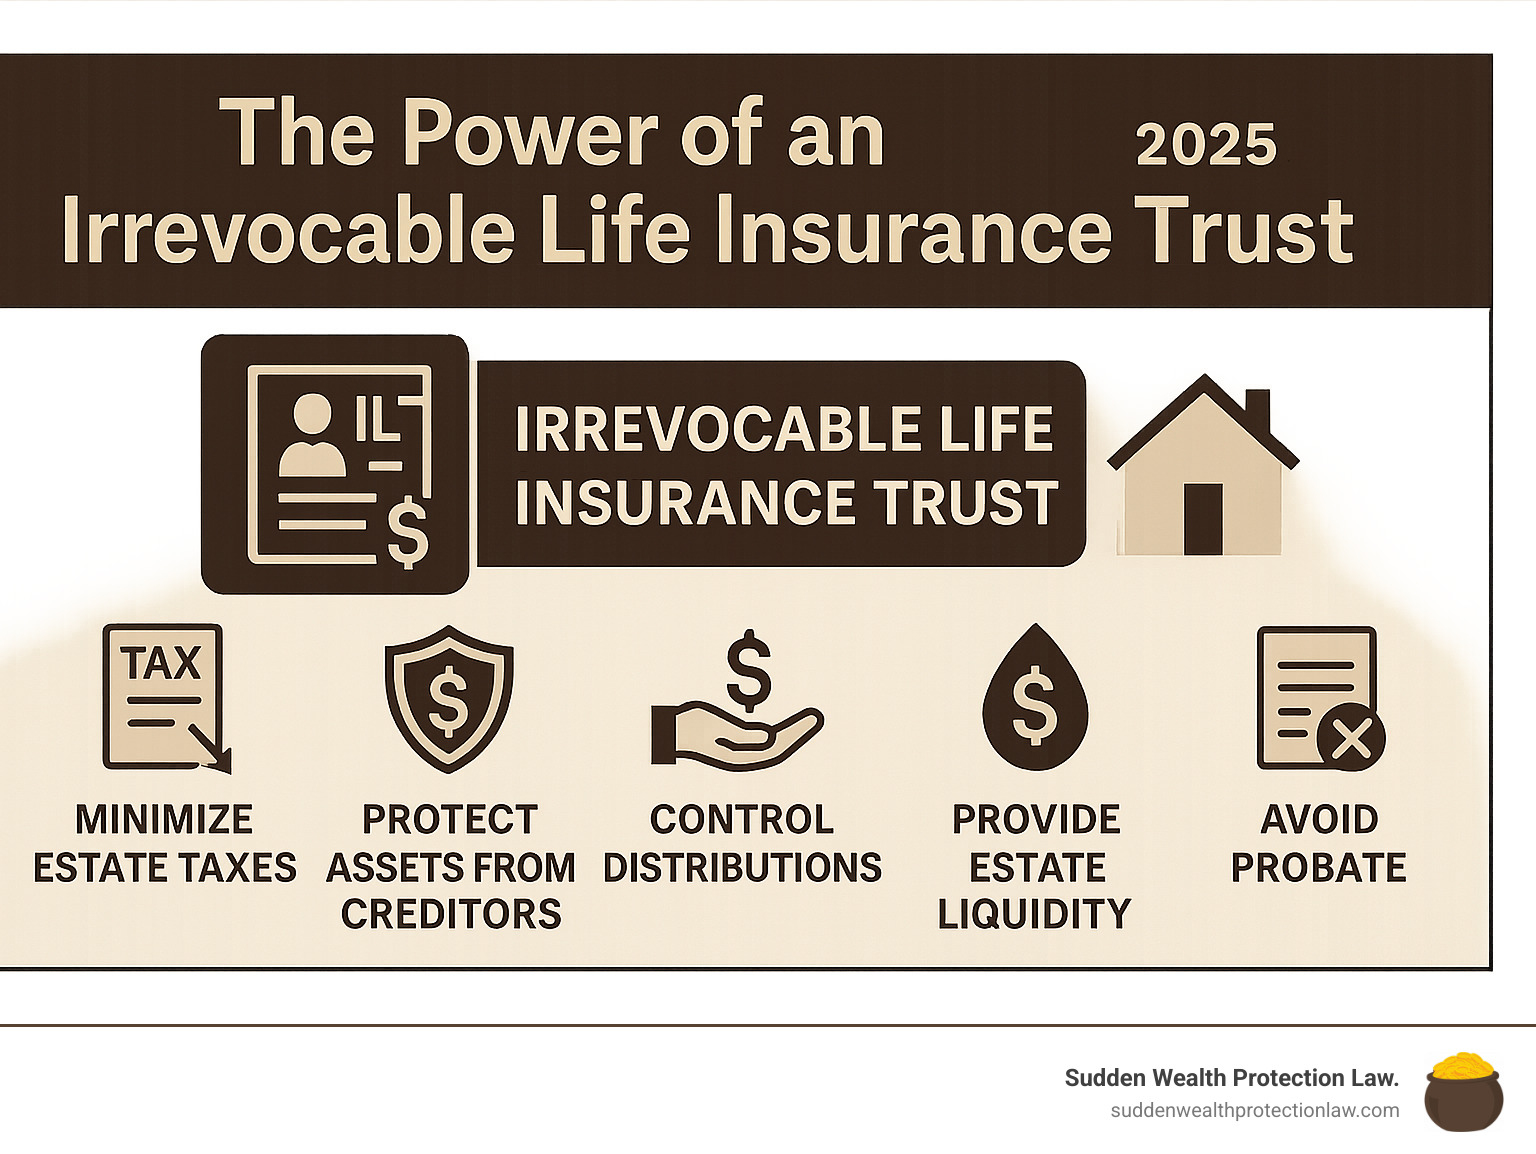
An Irrevocable Life Insurance Trust (ILIT) is a specialized legal vehicle used primarily in high-net-worth estate planning. When an individual owns a life insurance policy in their own name, the death benefit is generally included in their gross estate. If the total value of the estate exceeds federal or state exemption thresholds, that life insurance payout could be subject to significant estate taxes, effectively reducing the wealth transferred to heirs.
The Elizabeth A. DiGeronimo 2011 Irrevocable Trust functions as a mechanism to shift the "incidents of ownership" of a life insurance policy away from the insured. By irrevocably gifting the policy—or the cash required to pay premiums—to the trust, the insured relinquishes control. Because the insured no longer technically owns the policy or possesses the power to change beneficiaries or borrow against the cash value, the death benefit is legally excluded from their estate upon death.
This structural strategy serves several critical functions:
- Estate Liquidity: Providing cash to the estate to pay administrative costs and taxes without requiring the forced sale of illiquid assets like real estate or business interests.
- Tax Efficiency: Bypassing the inclusion of the death benefit in the taxable estate calculation.
- Asset Protection: Providing a layer of separation between the insurance proceeds and potential creditors of the beneficiaries or the insured.
Establishing the 2011 Trust Structure
The formation of an irrevocable trust in 2011 implies adherence to the regulatory landscape of that era, specifically regarding gift tax exemptions and trust law. While laws evolve, trusts established in a specific year are governed by the trust instrument drafted at that time and the prevailing tax codes.
An irrevocable trust is, by definition, permanent. Once the Elizabeth A. DiGeronimo 2011 Irrevocable Trust was signed and funded, the grantor generally could not revoke, amend, or terminate the trust. This permanence is the price paid for the tax benefits. The trust acts as a standalone legal entity with its own Tax Identification Number (TIN).
Key Roles within the Trust
- Grantor: The individual (Elizabeth A. DiGeronimo) who creates the trust and contributes the life insurance policy or premium funds.
- Trustee: The fiduciary responsible for managing the trust assets according to the trust document. The trustee must ensure premiums are paid on time and that the insurance company is notified of any changes in ownership.
- Beneficiaries: The individuals or entities entitled to receive the proceeds of the life insurance policy once the insured passes away.
The Role of Crummey Powers in Premium Funding
For an ILIT to be effective, the transfer of funds into the trust to pay premiums must be handled carefully to avoid triggering unintended gift tax consequences. Under federal law, gifts to a trust do not always qualify for the annual gift tax exclusion unless they are considered "present interest" gifts.
To bridge this gap, trust attorneys typically include "Crummey powers" (named after the Crummey v. Commissioner court case). These provisions grant beneficiaries a temporary window—usually 30 days—to withdraw the funds contributed to the trust. Because the beneficiaries have a legal right to access the money, the gift is classified as a present interest, allowing the grantor to use their annual gift tax exclusion to cover the premium payments.
If the beneficiaries choose not to exercise this withdrawal power (which is the intended outcome), the money remains in the trust to pay the insurance premium.
Operational Considerations and Maintenance
A common misconception is that an ILIT is a "set it and forget it" tool. In reality, the Elizabeth A. DiGeronimo 2011 Irrevocable Trust requires ongoing administrative attention to remain compliant and effective.
Annual Fiduciary Duties
The trustee must maintain a strict record-keeping system. This includes:
- Issuing Crummey Notices: Providing formal, written notification to beneficiaries each time a contribution is made to the trust, informing them of their right to withdraw the funds.
- Premium Payments: Ensuring that the insurance company receives the premiums on time. Failure to pay premiums can lead to the lapse of the policy, which would defeat the entire purpose of the trust.
- Tax Filings: Depending on the income generated by the trust assets, the trustee may need to file an annual income tax return (IRS Form 1041).
The Three-Year Rule
One of the most significant risks in life insurance planning is the "Three-Year Rule." Under Internal Revenue Code Section 2035, if an insured individual transfers an existing policy into a trust and dies within three years of that transfer, the IRS may pull the death benefit back into the taxable estate. This risk is typically mitigated by having the trust purchase the policy directly, rather than transferring an existing one, though the latter was common in existing trust structures.
Comparative Analysis: Traditional Ownership vs. ILIT
| Feature | Individual Ownership | Irrevocable Trust Ownership |
|---|---|---|
| Estate Tax Inclusion | Included in taxable estate | Excluded (if structured correctly) |
| Control over Policy | Full control (beneficiaries, loans) | Limited/None (Trustee control) |
| Asset Protection | Vulnerable to creditors | Generally protected |
| Administrative Burden | Minimal | Requires annual filings/notices |
| Flexibility | Highly flexible | Extremely rigid |
Limitations and Risks
While the Elizabeth A. DiGeronimo 2011 Irrevocable Trust serves a clear technical purpose, there are inherent risks to consider.
- Loss of Control: The grantor cannot reclaim the policy. If the grantor’s financial situation changes drastically, they cannot reach into the trust to tap the policy’s cash value.
- Administrative Complexity: Failing to follow formal procedures (such as failing to send Crummey notices) can lead to the IRS disallowing the annual gift tax exclusion, which could trigger gift tax liability.
- Changing Tax Laws: While the trust is governed by 2011 standards, federal estate tax exemptions change periodically. A structure that was highly relevant in 2011 may require a re-evaluation in 2026 to ensure it still serves the grantor's current wealth transfer goals.
Guidance for Beneficiaries and Successor Trustees
If you are a beneficiary or have been named a successor trustee for the Elizabeth A. DiGeronimo 2011 Irrevocable Trust, your responsibilities are significant. Beneficiaries should keep copies of any notices received from the trustee regarding contributions. These records are vital for tax purposes.
Successor trustees should ensure they have the following documents:
- The original Trust Agreement.
- The Policy Document(s) associated with the trust.
- Records of previous tax filings and Crummey notices.
- Contact information for the insurance carrier and the legal counsel who originally drafted the document.
Professional legal and accounting guidance is almost always necessary when dealing with irrevocable trusts. As of 2026, many of these trusts are reaching a point where the insurance policies they hold may be nearing maturity or may require adjustments based on the current health of the policy (e.g., cash value performance or projected premium increases).
Frequently Asked Questions
Can the grantor of the Elizabeth A. DiGeronimo 2011 Irrevocable Trust change the beneficiaries?
Generally, no. Because the trust is irrevocable, the grantor does not retain the power to amend the terms. Any changes would typically require a court order or the consent of all beneficiaries, which is often difficult to obtain and may have negative tax implications.
What happens if the insurance policy inside the trust lapses?
If the policy lapses due to non-payment of premiums, the trust will lose its primary asset. The trustee has a fiduciary duty to monitor the policy's performance. If funds are not available to pay premiums, the trust may become an "empty" shell, effectively ending its utility.
Is the death benefit from this trust subject to income tax?
In most cases, life insurance proceeds are received income-tax-free by the beneficiaries. However, there are exceptions, such as the "transfer-for-value" rule. It is essential to ensure that the initial transfer of the policy into the trust did not violate these rules.
Why was a 2011 trust created specifically?
The choice of year often corresponds to specific federal estate tax exemption levels. In 2011, the Tax Relief, Unemployment Insurance Reauthorization, and Job Creation Act of 2010 was in effect, which significantly altered the estate tax landscape for that year. Planners often utilized these legislative windows to lock in tax-efficient structures.
Does the trustee have to be a professional?
No, the trustee can be a family member, a friend, or a professional entity like a bank or trust company. However, the trustee must be capable of fulfilling the complex administrative requirements, including the timing of notices and the proper handling of insurance premium payments.
Final Recommendations
If you are involved with or managing the Elizabeth A. DiGeronimo 2011 Irrevocable Trust, the priority should be a 2026 administrative audit. Review the current status of the insurance policy, verify that all premium obligations are being met, and ensure that your records of Crummey notices are complete for the last several years. If the trust has not been reviewed by a qualified estate attorney in the last five years, schedule a consultation to ensure the trust remains aligned with your family’s current financial objectives and that no administrative deficiencies have occurred.