Finding reliable and affordable auto insurance in Pontiac, Michigan requires balancing Michigan’s unique no-fault reform laws with individual coverage needs, local traffic realities, and provider reputation. Pontiac drivers face some of the highest insurance premiums in the state due to urban density, historical claims data, and regional risk factors. Choosing the right carrier involves comparing coverage levels, premium costs, and claims satisfaction across major providers serving Oakland County.
When searching for the 5 best auto insurance options in Pontiac, MI, drivers should evaluate major regional and national carriers including Progressive, AAA Michigan, State Farm, GEICO, and Allstate. These companies offer robust digital tools, flexible deductible options, and customizable policies designed to help navigate Michigan's mandatory Personal Injury Protection (PIP) choices while keeping out-of-pocket costs manageable.
Understanding Michigan’s Auto Insurance Landscape in Pontiac
Michigan operates under a unique auto insurance system that fundamentally shapes how policies are structured in Pontiac. Unlike tort states where drivers rely entirely on at-fault liability, Michigan has historically been a mandatory no-fault state. This means that regardless of who causes an accident, your own auto insurance company pays for your medical bills and rehabilitation expenses up to your chosen policy limit through Personal Injury Protection (PIP).
Recent legislative reforms have altered how drivers select their PIP coverage. Instead of mandatory lifetime unlimited medical benefits—which historically drove Michigan's rates to be the highest in the nation—drivers now have multiple options for medical coverage levels. Pontiac residents can choose from options ranging from state-managed Medicaid exceptions to $50,000, $250,000, or unlimited medical coverage. Selecting lower medical limits can significantly reduce monthly premiums, but it shifts the financial burden of catastrophic injuries onto private health insurance or personal assets if health plans do not cover auto accident injuries.
In addition to PIP, Michigan law requires property protection insurance (PPI) and residual liability insurance. PPI covers up to $1 million for damage your vehicle does to other people's property, such as buildings, fences, or utility poles within the state. Residual liability insurance protects you if you are sued for causing an injury or death in an accident, with mandatory minimum limits of $250,000 for injury or death to one person and $500,000 for multiple people, though drivers can opt for lower minimums of $50,000 and $100,000 at their own legal and financial risk.
Top 5 Auto Insurance Providers Serving Pontiac
Evaluating the best auto insurance options in Pontiac involves examining carriers that consistently score well for financial stability, local claim processing efficiency, discount availability, and customer service ratings within Oakland County.
1. Progressive
Progressive is widely recognized for its aggressive pricing models and digital-first approach, making it a strong contender for Pontiac drivers looking for competitive rates. The company stands out for its Name Your Price tool, which helps budget-conscious consumers find coverage tiers that fit specific financial parameters. Progressive also offers the Snapshot program, a telematics device or mobile app tracking driving habits such as speed, braking, and phone distraction. For safe drivers in Pontiac, Snapshot can yield substantial discounts, though aggressive or late-night driving habits can occasionally cause rates to increase.
2. AAA Michigan (Auto Club Group)
AAA Michigan is a legacy insurer deeply rooted in the state, offering localized claims service and robust roadside assistance packages. Because AAA operates as a membership club, policyholders gain access to travel discounts, battery replacement services, and dedicated local agents who understand the specific municipal nuances of Oakland County. AAA Michigan provides comprehensive bundle discounts for homeowners and renters insurance, which is often the most effective strategy for lowering overall insurance expenditures in high-rate urban areas like Pontiac.
3. State Farm
State Farm maintains a massive market share across Michigan, anchored by an extensive network of captive agents who provide personalized face-to-face consultations. For Pontiac drivers who prefer dealing with a dedicated local representative rather than an automated call center, State Farm offers stability and structured customer service. The carrier features the Steer Clear program for young drivers and Drive Safe & Save for all ages, rewarding low-mileage and safe driving behaviors with premium reductions. State Farm's financial strength ratings consistently rank among the highest in the industry, assuring policyholders of reliable claim payouts.
4. GEICO
GEICO is a premier choice for drivers seeking straightforward, low-cost coverage managed primarily through an intuitive mobile application. While GEICO relies less on brick-and-mortar local agents, its digital platform allows Pontiac policyholders to modify coverages, print insurance cards, and file claims within minutes. GEICO offers standard discounts for military personnel, federal employees, good students, and accident-free driving records. Their rates tend to be very competitive for drivers with clean driving histories who reside within the Pontiac ZIP codes.
5. Allstate
Allstate is known for robust coverage add-ons and accident forgiveness programs that prevent rate hikes following a first at-fault collision. For Pontiac residents concerned about steep rate increases after a minor fender-bender, Allstate’s rewards programs provide valuable peace of mind. Allstate also features Milewise, a pay-per-mile insurance program ideal for remote workers, retirees, or individuals in Pontiac who commute short distances and drive less than average annual mileage.
Comparison of Top Pontiac Auto Insurance Providers
| Insurance Provider | Primary Strengths | Notable Discounts | Best Suited For |
|---|---|---|---|
| Progressive | Competitive base rates, flexible digital quoting tools | Snapshot telematics, paperless, multi-policy | Budget-conscious drivers and tech-savvy users |
| AAA Michigan | Local agent network, integrated roadside assistance | Membership perks, home bundling, safety features | Drivers seeking local support and roadside benefits |
| State Farm | Dedicated agents, high financial stability ratings | Drive Safe & Save, good student, multi-car | Customers preferring personal agent relationships |
| GEICO | User-friendly mobile app, streamlined claims process | Military, federal employee, accident-free | Drivers wanting fast digital management and low rates |
| Allstate | Accident forgiveness, customized coverage options | Milewise pay-per-mile, safe driving bonus, bundling | Drivers prioritizing accident protection and flexibility |
Key Factors Influencing Insurance Rates in Pontiac
Insurance premiums in Pontiac are calculated using a complex algorithm that weighs personal driver profiles against regional statistical risk. Understanding these variables helps consumers identify areas where they can control costs.
ZIP Code and Hyper-Local Risk Factors
Where you park and drive your vehicle heavily influences your rate. Pontiac features higher population densities, busier commercial corridors, and statistical traffic patterns that insurers categorize as higher risk compared to surrounding rural or affluent suburban townships in Oakland County. Vehicle theft rates, uninsured motorist percentages, and historical accident frequencies within specific Pontiac ZIP codes are factored directly into underwriting models.
Driving Record and Claims History
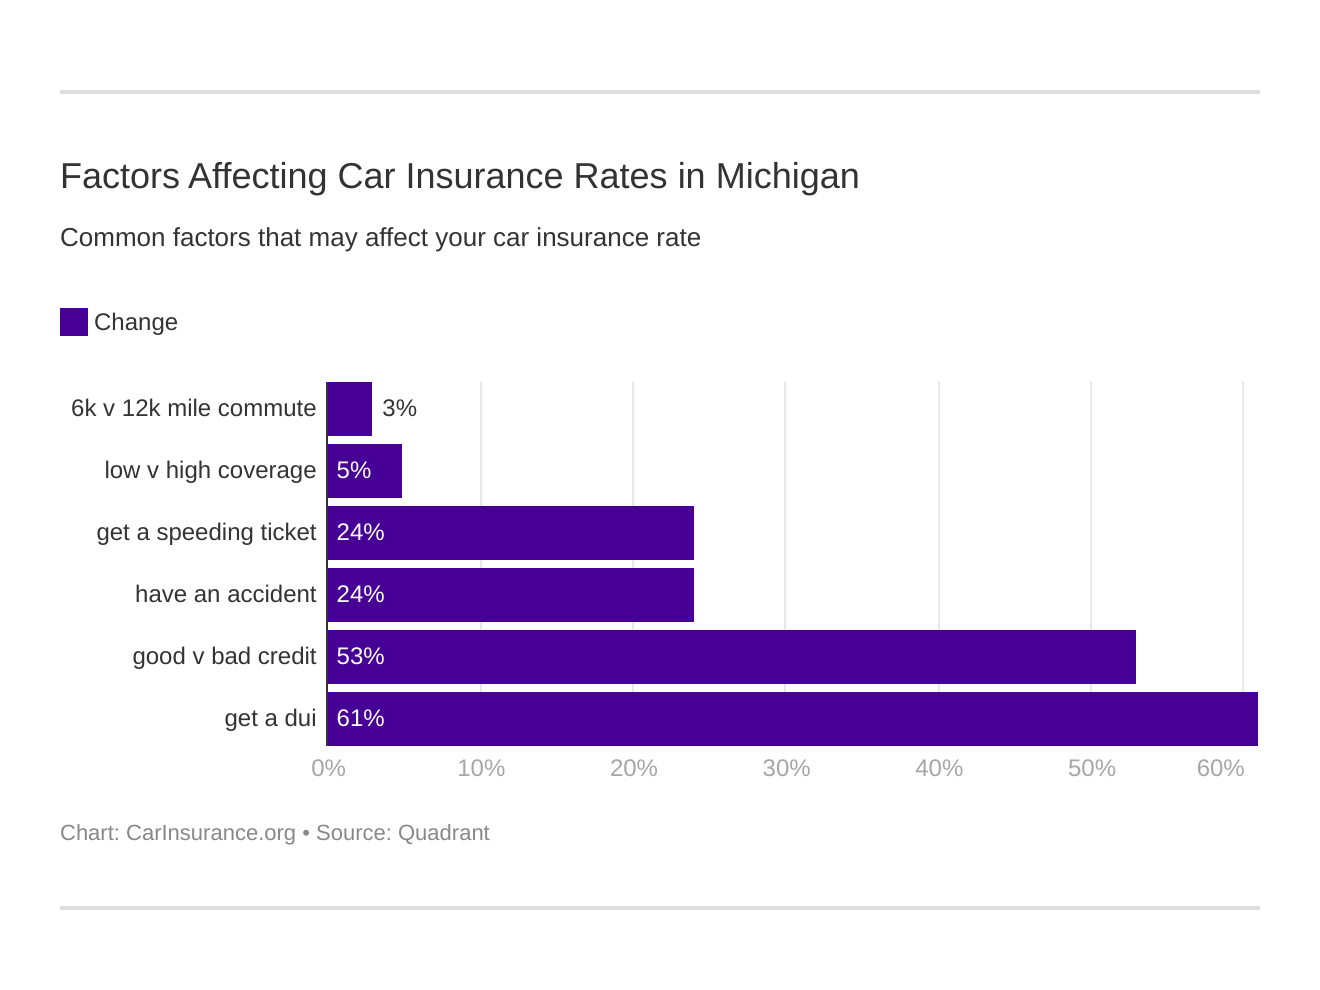
A clean driving record is the single most effective tool for keeping auto insurance affordable. Moving violations such as speeding tickets, reckless driving charges, and DUI convictions result in significant premium surcharges or classification as a high-risk driver. In Michigan, at-fault accidents stay on your record for multiple years, directly impacting your eligibility for preferred tier pricing with top-tier carriers.
Vehicle Make, Model, and Safety Ratings
The vehicle you drive dictates the cost of physical damage coverage (collision and comprehensive). High-performance sports cars, luxury vehicles with expensive electronic sensors embedded in windshields, and models frequently targeted by thieves cost more to insure. Conversely, vehicles equipped with advanced driver-assistance systems (ADAS), high crash-test ratings from the Insurance Institute for Highway Safety (IIHS), and standard safety features generally qualify for lower comprehensive and collision premiums.
Strategies to Lower Auto Insurance Costs in Pontiac
Because Pontiac rates tend to exceed state and national averages, actively managing policy structures and applying for available discounts is essential for financial efficiency.
Opting for Telematics Programs
Programs like Progressive Snapshot, State Farm Drive Safe & Save, and Allstate Drivewise monitor actual driving behaviors via a plug-in device or smartphone application. Safe acceleration, moderate speeds, smooth braking, and avoiding late-night driving can yield discounts of 10% to 30%. However, drivers with erratic commutes or heavy night driving schedules should evaluate whether their habits align with telematics scoring metrics before enrolling.
Adjusting Deductibles Wisely
Raising your comprehensive and collision deductibles from $500 to $1,000 can reduce your annual premium by 10% to 20%. Before making this adjustment, ensure you maintain an emergency fund capable of covering the higher out-of-pocket expense in the event of an unexpected claim.
Bundling Policies
Insurance carriers frequently offer deep discounts when you purchase auto insurance alongside homeowners, renters, condo, or umbrella policies. Consolidating your insurance portfolio with a single provider like AAA Michigan or State Farm often results in lower combined billing totals.
Frequently Asked Questions About Auto Insurance in Pontiac
Why are auto insurance rates so high in Pontiac, Michigan?
Pontiac insurance rates reflect urban density, higher litigation rates, regional accident frequency, and the historical cost structure of Michigan's mandatory no-fault medical benefit system. Urban environments statistically experience more traffic congestion, vehicle thefts, and property damage claims, which insurers factor into baseline pricing.
What is the minimum auto insurance required in Pontiac?
Michigan law requires all registered vehicles to carry Personal Injury Protection (PIP) medical coverage, Property Protection Insurance (PPI) up to $1 million for out-of-state or specific property damage, and residual liability insurance with minimum limits of $250,000/$500,000 (or lower options of $50,000/$100,000 if elected). Collision and comprehensive coverages are optional unless required by a vehicle lienholder or lease agreement.
Can I opt out of Michigan PIP medical coverage?
Drivers with Medicare Parts A and B can entirely opt out of Michigan PIP medical coverage. Drivers with qualified health insurance—meaning coverage that does not exclude auto accident injuries and has an individual deductible of $6,000 or less—can also opt out of PIP medical coverage entirely, transferring primary medical responsibility to their health plan.
How do I switch my auto insurance provider in Michigan?
You can switch auto insurance providers at any time during your policy term. Before canceling your current policy, secure and activate coverage with your new provider to avoid a coverage lapse, which is illegal and triggers severe state penalties. Request a prorated refund of any unused prepaid premium from your previous insurer.
Are there assistance programs for low-income drivers in Pontiac?
The Michigan Automobile Insurance Placement Facility (MAIPF) operates the Michigan Assigned Claims Plan (MACP), which provides basic no-fault benefits to uninsured individuals who are injured in accidents involving uninsured vehicles, though this is a claims-assistance mechanism rather than a subsidized standard insurance policy. Low-income drivers should carefully compare quotes from budget-focused carriers and maximize all available discounts to manage baseline costs.
Conclusion and Next Action
Securing the best auto insurance in Pontiac, MI requires balancing mandatory state regulations with personal financial protection. Start by gathering official quotes from at least three of the top providers listed above—such as Progressive, AAA Michigan, and State Farm—ensuring that you compare identical coverage limits and deductible structures. Review your health insurance policy to determine whether you qualify to adjust your PIP medical selections safely. By combining strategic deductible adjustments, telematics enrollment, and multi-policy bundling, Pontiac drivers can secure reliable coverage that fits both their driving habits and their household budget.