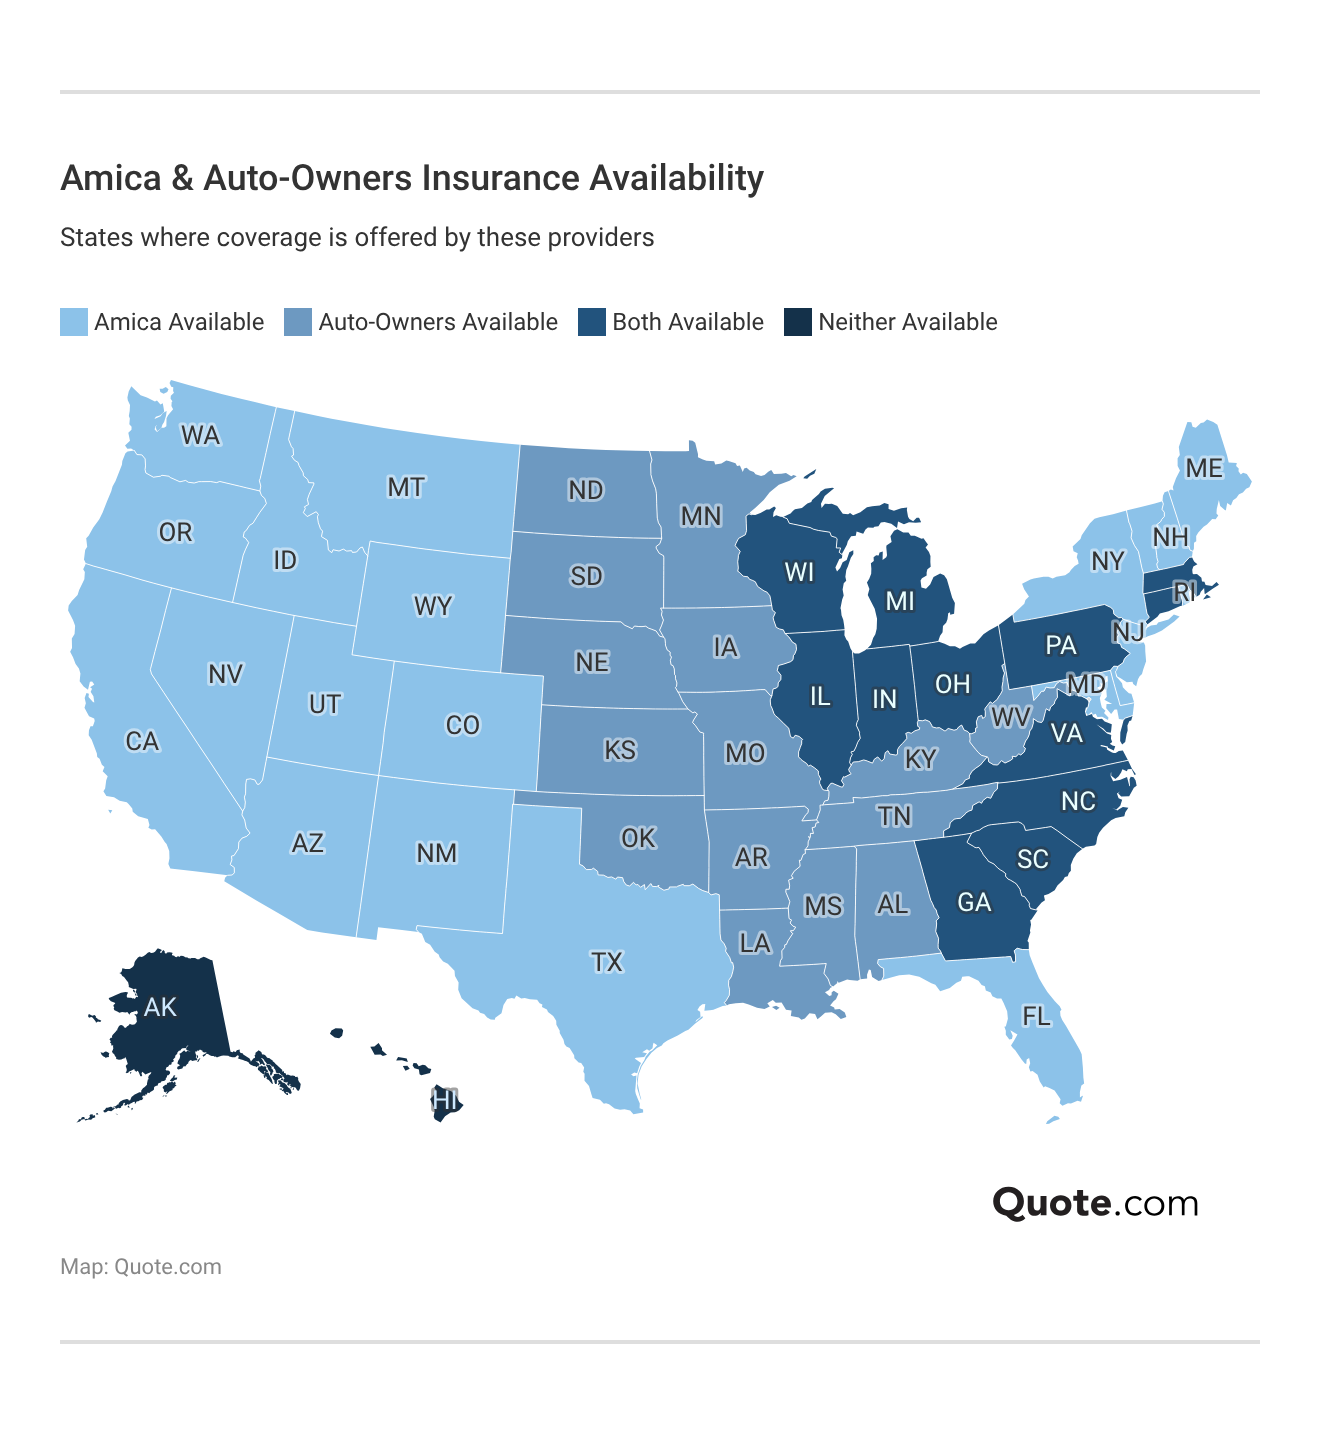
Amica Mutual Insurance offers auto coverage in Washington that prioritizes high levels of customer service, dividend-paying policies, and robust claim support. Residents of Washington seeking to evaluate Amica must navigate the state’s specific financial responsibility laws, regional rating factors, and the company's unique approach to bundling and long-term customer loyalty.
Understanding the Washington Auto Insurance Landscape
Washington State maintains a regulatory environment overseen by the Office of the Insurance Commissioner (OIC). Under state law, all drivers are required to carry liability insurance with minimum limits of $25,000 for bodily injury or death of one person, $50,000 for bodily injury or death of two or more persons, and $10,000 for property damage. While these figures represent the absolute legal minimum, financial experts and industry analysts frequently recommend higher limits to protect personal assets in the event of a significant liability claim.
Amica operates within this framework by offering standard and premium policy tiers. Unlike some insurers that prioritize low-cost, high-volume acquisition, Amica’s model emphasizes the "Platinum Choice" policy. This tier is designed to provide comprehensive coverage options that often exceed basic state requirements, including features like full glass coverage, replacement cost coverage for new vehicles, and identity fraud monitoring.
Core Policy Features of Amica in Washington
When you select an auto insurance provider in the Pacific Northwest, the specific features offered can significantly impact your financial recovery after an accident. Amica’s offerings in Washington typically include several core components that distinguish the company from direct-to-consumer digital-only carriers:
- Liability Coverage: This covers the costs if you are found at fault for an accident, including other parties' medical bills and vehicle repairs.
- Collision Coverage: This pays for repairs to your vehicle resulting from an accident with another object or vehicle, regardless of fault.
- Comprehensive Coverage: This protects your vehicle against non-collision incidents such as theft, vandalism, fire, or weather-related damage, which is pertinent given Washington’s diverse climate and occasional severe weather events.
- Uninsured/Underinsured Motorist Coverage: This is vital in Washington to protect against drivers who either lack insurance or have limits insufficient to cover your total losses.
Beyond these basics, Amica provides a suite of endorsements. For Washington residents, the "Rental Reimbursement" and "Towing and Labor" options are frequently utilized. The "Good Driving Reward" program and potential dividends—where policyholders may receive a portion of their premiums back depending on the company's annual performance—are significant differentiators.
Eligibility and Prerequisites
To secure a policy with Amica in Washington, you must meet standard underwriting criteria. The application process involves a review of your driving record, the type of vehicle you intend to insure, and your insurance history.
- Vehicle Information: Have your Vehicle Identification Number (VIN), current mileage, and primary usage details (e.g., commute distance, personal vs. business use) ready.
- Driver History: Amica assesses your history of moving violations, accidents, and insurance claims. Washington’s motor vehicle report data will be queried during the underwriting process.
- Credit-Based Insurance Scoring: While Washington has placed certain restrictions on the use of credit history in insurance rating, insurers still often utilize variables permitted by the OIC. Be prepared for a standard review process that aligns with current state regulations.
- Proof of Prior Insurance: Maintaining continuous insurance coverage is often a factor in securing competitive rates. If you are switching from another carrier, have your current policy's declarations page available for a smoother transition.
Cost Considerations and Premium Factors
Insurance premiums are not static. In 2026, Washington drivers may notice shifts in premiums driven by the rising cost of vehicle repairs and the increasing complexity of modern vehicle safety systems. Amica prices its policies based on a proprietary actuarial model that considers several local variables:
| Factor | Influence on Premium |
|---|---|
| Location (ZIP Code) | High-density urban areas like Seattle have different risk profiles than rural Eastern Washington. |
| Vehicle Safety Features | Advanced Driver Assistance Systems (ADAS) may lower repair costs or accident risk. |
| Annual Mileage | Lower annual mileage generally correlates with reduced exposure to accident risks. |
| Deductible Selection | Choosing a higher deductible lowers your premium but increases your out-of-pocket cost during a claim. |
| Bundling Discounts | Combining auto insurance with Amica homeowners or renters insurance significantly reduces overall costs. |
It is important to note that Amica’s premiums are often viewed as mid-to-high range compared to budget insurers. However, this is frequently offset by the company’s reputation for service quality and the potential for long-term savings through their dividend programs.
The Claims Process: What to Expect
If you are involved in an incident, the efficiency and transparency of your insurer’s claims process are paramount. Amica is consistently ranked highly for customer service in claims management.
Upon reporting a claim in Washington, you will be assigned a specific claims representative. This representative serves as your primary point of contact, coordinating inspections, damage assessments, and communication with auto repair shops. Amica’s network of "Direct Repair" shops in Washington can often streamline the repair process, as these facilities have pre-negotiated rates and billing protocols with the insurer.
If you choose an out-of-network repair shop, ensure the facility provides a detailed estimate that aligns with industry-standard labor rates. Amica’s adjusters will review these estimates to ensure they comply with your policy's terms. Always review your policy declarations page to understand your specific deductible and any limits on rental vehicle reimbursement before an emergency occurs.
Frequently Asked Questions
Does Amica offer accident forgiveness in Washington? Yes, Amica provides an Accident Forgiveness program as an optional feature. This allows your policy premiums to remain unchanged after a single at-fault accident, provided you have met the eligibility criteria, such as maintaining a clean driving record for a specific period prior to the accident.
Can I manage my Amica Washington policy online? Yes, Amica offers a comprehensive online portal and mobile application. You can view policy documents, make payments, update your contact information, and initiate the claims filing process directly through these digital platforms.
Are there specific discounts available for Washington drivers? Amica offers several common discounts, including multi-car discounts, multi-policy discounts (bundling home and auto), and discounts for safety features like anti-theft devices. Additionally, drivers who remain claim-free for a certain duration are eligible for loyalty-based pricing benefits.
How does Amica handle glass repair in Washington? Depending on the specific "Platinum Choice" coverage selected, Amica may offer full glass coverage with no deductible for repairs or replacements. It is advisable to verify your specific policy’s glass coverage limits, as regional laws and policy options can vary.
What should I do if I am moving to Washington from another state? If you are an existing Amica policyholder moving to Washington, you must update your garaging address immediately. Insurance rates are highly location-dependent, and your premium will be recalculated based on the risk profile of your new zip code and the requirements of Washington law.
Practical Recommendation for Prospective Policyholders
If you are considering Amica Auto Insurance in Washington, start by gathering your current insurance declarations page. Use this as a baseline to obtain a customized quote through the Amica website or by speaking with a representative. Request a breakdown of the "Platinum Choice" features versus standard options to determine if the additional cost provides enough value for your specific vehicle and risk tolerance.
When comparing quotes, do not look at the premium alone. Look at the total value, including the deductible levels, the potential for dividends, and the reputation of the insurer’s claims department. For many drivers in Washington, Amica’s stability and customer-first approach make it a strong candidate for those who value long-term reliability over the lowest possible monthly quote.